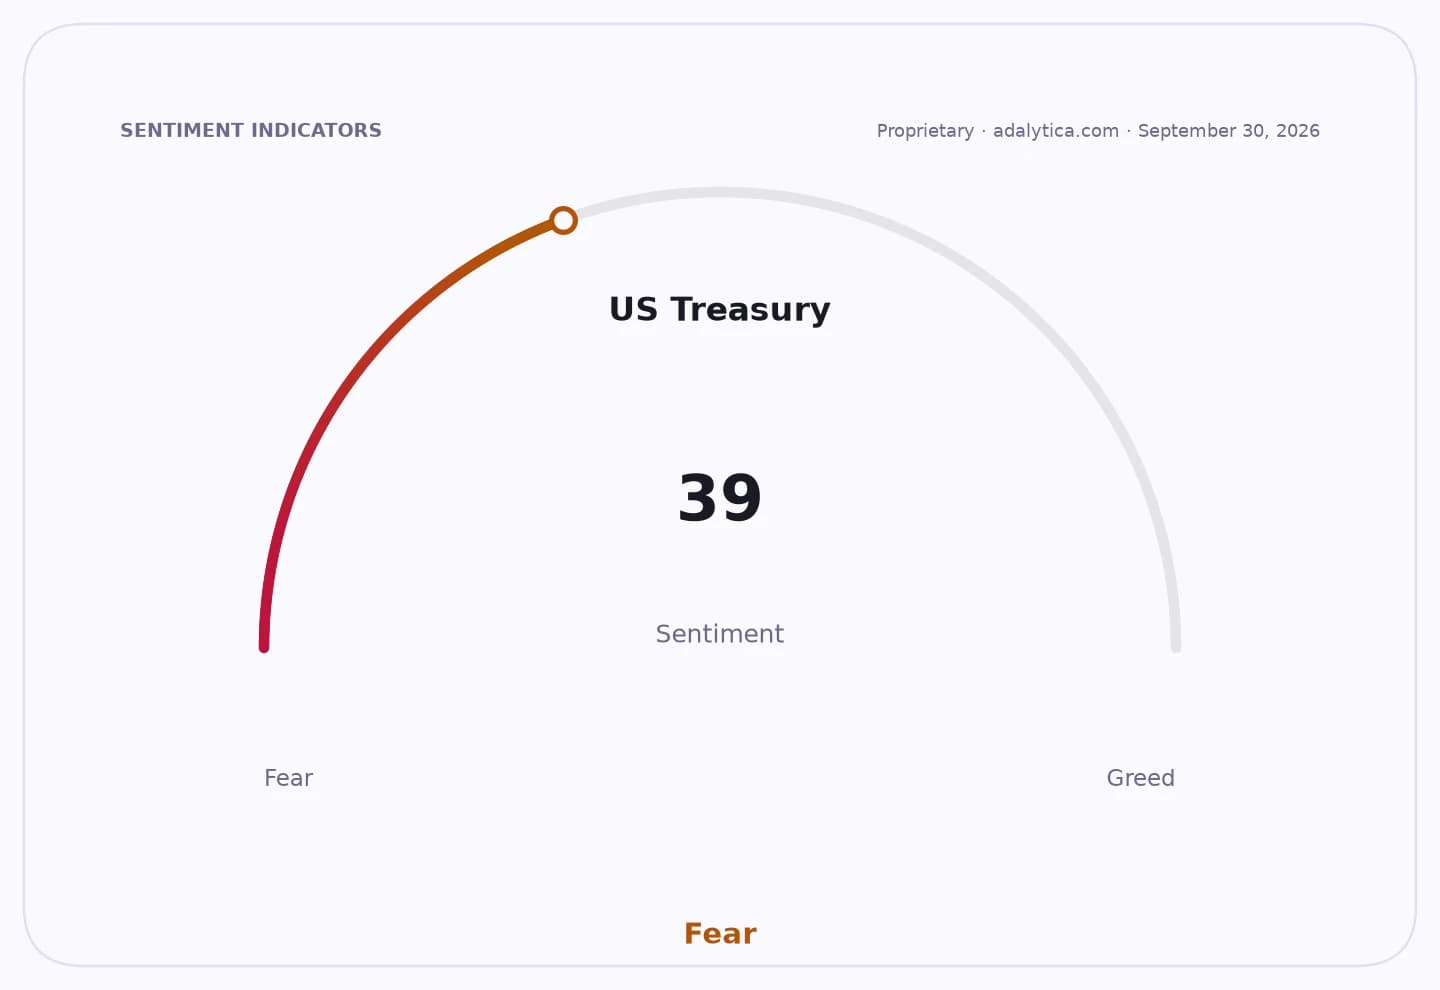
U.S. Treasury yields climbed toward multidecade highs on Monday as stronger-than-expected U.S. services data and fresh fiscal worries in Europe pushed investors to demand more compensation for holding government debt.
U.S. Treasury Yields Rise as Services Data Strong
The move matters because higher sovereign borrowing costs tighten financial conditions across the economy, raise the hurdle rate for corporate investment and pressure rate-sensitive assets from equities to long-duration bonds. It also underscores how markets are increasingly focused not just on central bank policy, but on the durability of government finances and growth.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 6, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The U.S. 10-year Treasury yield rose to 5.326% from 5.276% on Friday, while the 30-year climbed to 5.683% from 5.629%. The two-year yield, more sensitive to Federal Reserve policy expectations, edged up to 4.841% from 4.823% as markets continued to price in a hold at this month’s Fed meeting.
Part of the pressure came from data showing the U.S. economy remains resilient. The Institute for Supply Management’s services index came in at 54.9 in September, down only slightly from 55.4 in August and still comfortably above 50, signaling expansion. That reinforced the view that the Fed may be able to keep rates restrictive for longer, even as investors debate how far bond yields can rise before slowing growth and credit demand.
At the same time, Europe added another layer of stress to the global rate backdrop. French 10-year yields jumped to 4.873% in midday trade after touching 4.993% on Friday, the highest since 2002, as investors worried that the government’s budget proposal will struggle to pass in a fragmented parliament. The spread between French and German 10-year debt widened to 140.44 basis points after peaking Friday at a near 15-year high of 158.67 basis points.
Spanish bonds also sold off after Prime Minister Pedro Sanchez called snap elections for next month following protests over housing costs. Spain’s 10-year yield rose to 4.119%, after hitting 4.219% on Friday, the highest since 2013. The move reflected not only political uncertainty but also concern that a more volatile fiscal and policy mix could follow the vote.
The economic significance is broader than one day’s price action. A simultaneous rise in U.S., French and Spanish yields suggests investors are reassessing sovereign risk at a time when inflation remains sticky and growth is proving more durable than many expected. That combination is toxic for bond markets because it leaves central banks less able to cut aggressively while fiscal authorities face higher refinancing costs.
For investors, the immediate implication is a tougher environment for duration exposure. The iShares 20+ Year Treasury Bond ETF, which tracks long-dated U.S. government debt, has been under renewed pressure, with technical indicators showing a deeply oversold posture as the fund fell to 77.11 on Monday. The 10-year yield’s move back above 5.3% keeps focus on whether the market is repricing toward a higher-for-longer regime, or whether yields are nearing a level that will eventually choke off demand and trigger a reversal.
In Europe, the damage is more uneven. Germany’s Bunds remained relatively stable, with the 10-year yield little changed at 3.457%, highlighting that the selloff is being driven in part by spread widening rather than a uniform rise in euro-zone rates. That leaves France and Spain more exposed, while Germany continues to benefit from its relative safe-haven status.
The next catalyst is likely to be whether incoming U.S. inflation and labor data confirm the economy’s resilience or finally show enough cooling to cap yields. Until then, governments facing larger deficits, and investors holding long-duration debt, are likely to remain on the defensive.
| Entity | Gains | Losses |
|---|---|---|
| U.S. Treasury shorts | ▲Higher yields | ▼Bond prices |
| Long-duration bond holders | ▲None | ▼Portfolio value |
| French and Spanish governments | ▲None | ▼Borrowing costs |
| German Bunds | ▲Safe-haven demand | ▼Less relative spread benefit |