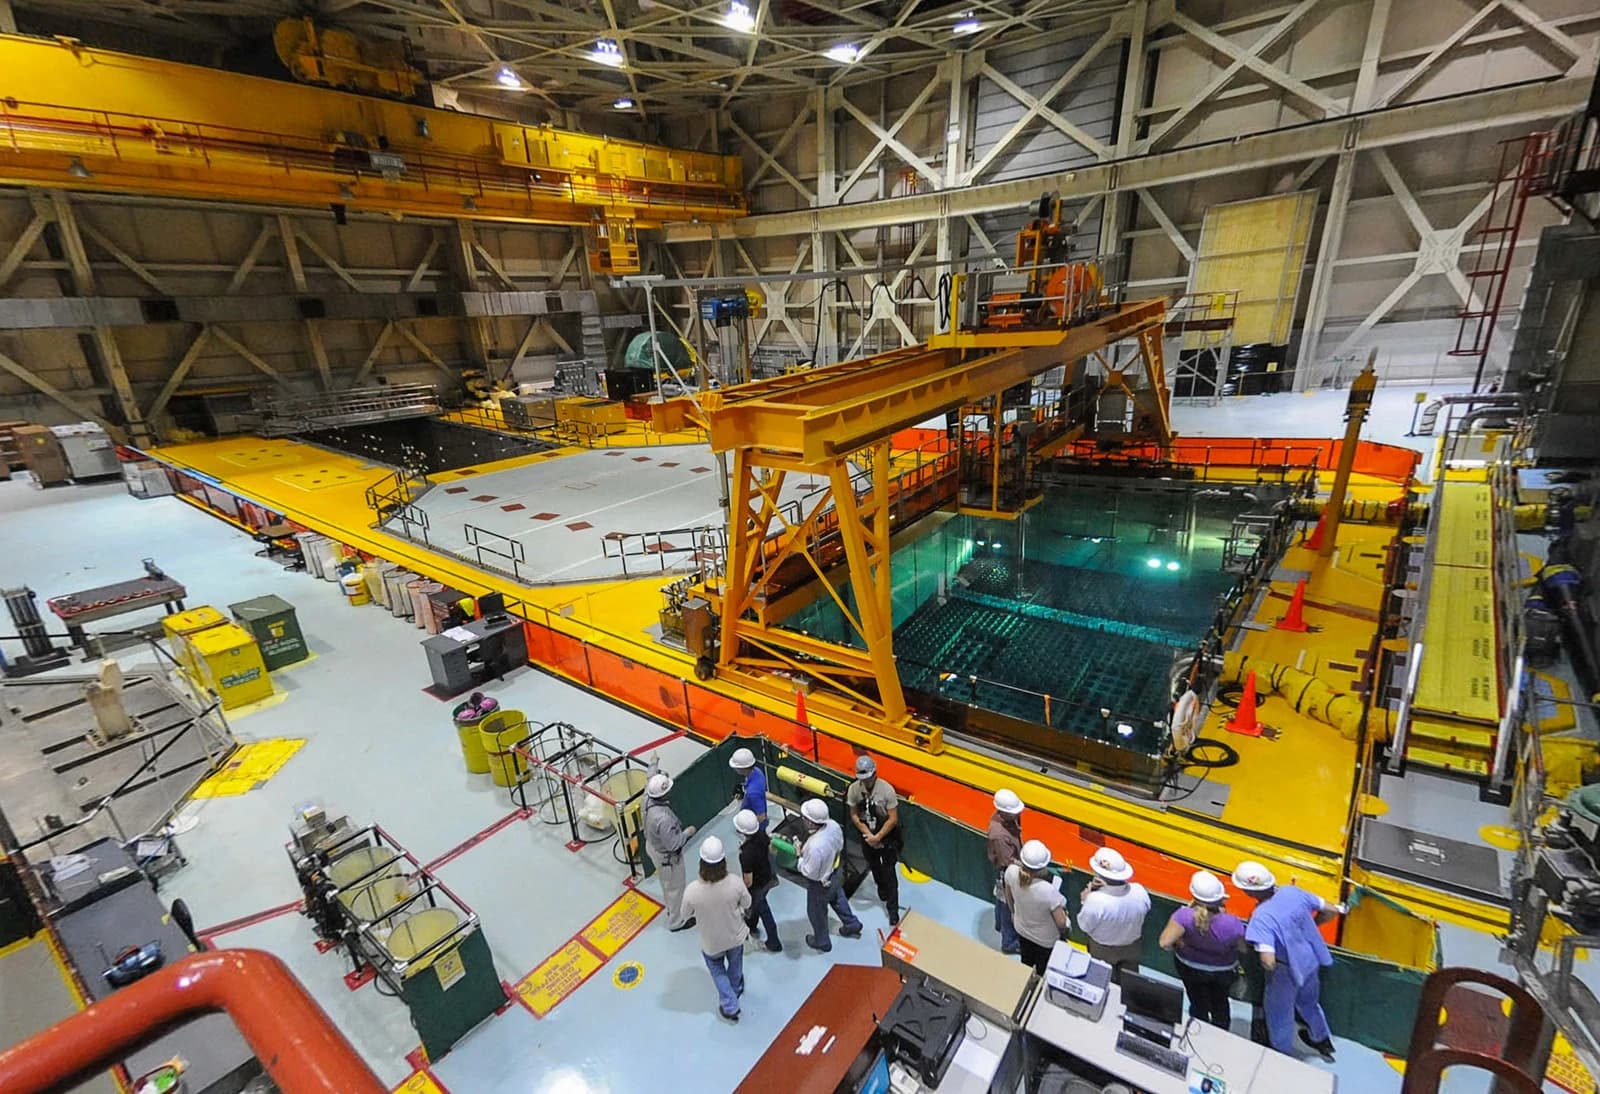
Utilities are still planning a major nuclear buildout to meet rising power demand from data centers, manufacturing and electrification, but investors have turned skeptical as the trade loses momentum and the public market pulls back.
U.S. Utilities Plan 33.6 GW Nuclear Buildout
A new Nuclear Energy Institute survey of 21 U.S. utilities covering 95 commercial reactors found companies are planning 33.6 gigawatts of new nuclear generation over the next 15 years, with roughly 28 gigawatts concentrated in 2035-2039. The same survey showed more than 97% of units are seeking or considering operating licenses for at least 80 years, underscoring how utilities are stretching the life of the existing fleet even as they talk about building more.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 26, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The long-duration nuclear push matters economically because power demand is being reshaped by AI data centers, domestic manufacturing and electrification, all of which require large, reliable baseload supply. NEI said uprates, restarts, longer refueling cycles and other upgrades could add more than 7 gigawatts from the current fleet over the coming decade, including about 2.2 gigawatts from the restarted Palisades, Three Mile Island and Duane Arnold plants.
That is a more immediate source of capacity than new construction, which remains largely in the planning phase. The industry’s ambitions are broadening beyond large reactors to small modular reactors, while there were no microreactor plans in the utility survey, even as private developers draw more than $1 billion in funding for microreactor projects aimed at defense and remote power markets.
For investors, the disconnect is stark. SPY is up about 12% this year and XLE has climbed more than 40%, but none of the three main nuclear-themed ETFs are positive in 2026. Uranium-heavy URA is down about 2% to 3%, the more concentrated NLR has fallen about 13%, and stocks tied to the theme have also suffered sharp recent selloffs after big 2024-2025 runs.
URA was trading at $40.91 on Sept. 25, below its 50-day moving average of $43.25 and its 200-day average of $48.19, with RSI readings near 33, a sign of weakening momentum. NLR closed at $105.78, also below its 50-day and 200-day moving averages, while UUUU was down to $11.35 and deeply oversold by RSI standards. Adalytica’s S&P 500 trade signals show the broader market in “Greed,” while Treasury bond signals also point to elevated risk appetite, leaving nuclear names outside the market’s current sweet spot.
The narrative is that utilities are laying the groundwork for a nuclear expansion that could eventually become meaningful for grid investment, equipment suppliers and uranium demand, but Wall Street wants actual construction, not just announcements. The sector’s next catalyst is whether utilities and developers can move enough projects from planning to permitting and financing to prove the renaissance is more than a theme trade.
| Entity | Gains | Losses |
|---|---|---|
| Utilities | ▲Future baseload supply | ▼Near-term capital costs |
| Nuclear developers | ▲Potential project pipeline | ▼Market credibility |
| Uranium miners/funds | ▲Long-term demand outlook | ▼Current share prices |
| Power-hungry data centers | ▲Grid-scale electricity access | ▼Timing uncertainty |