Commercial real estate is losing momentum just as housing affordability remains stretched, with the U.S. real estate ETF VNQ sliding back below key technical levels and sentiment around the sector turning neutral after a brief burst of optimism. For investors, the move points to a market where higher financing costs and softer pricing power are still outweighing the longer-term appeal of property income.
VNQ Falls Below Key Technical Levels
VNQ closed at 89.18 on Oct. 5, down from 97.55 in early July and well below its 50-day moving average of 95.21, while its 200-day moving average stood at 92.75. The relative strength index was 21.5, a reading that suggests the fund has been heavily sold, and the MACD remained negative. The technical setup underscores the strain on listed real estate as investors reassess earnings durability, refinancing risk and cap-rate pressure.
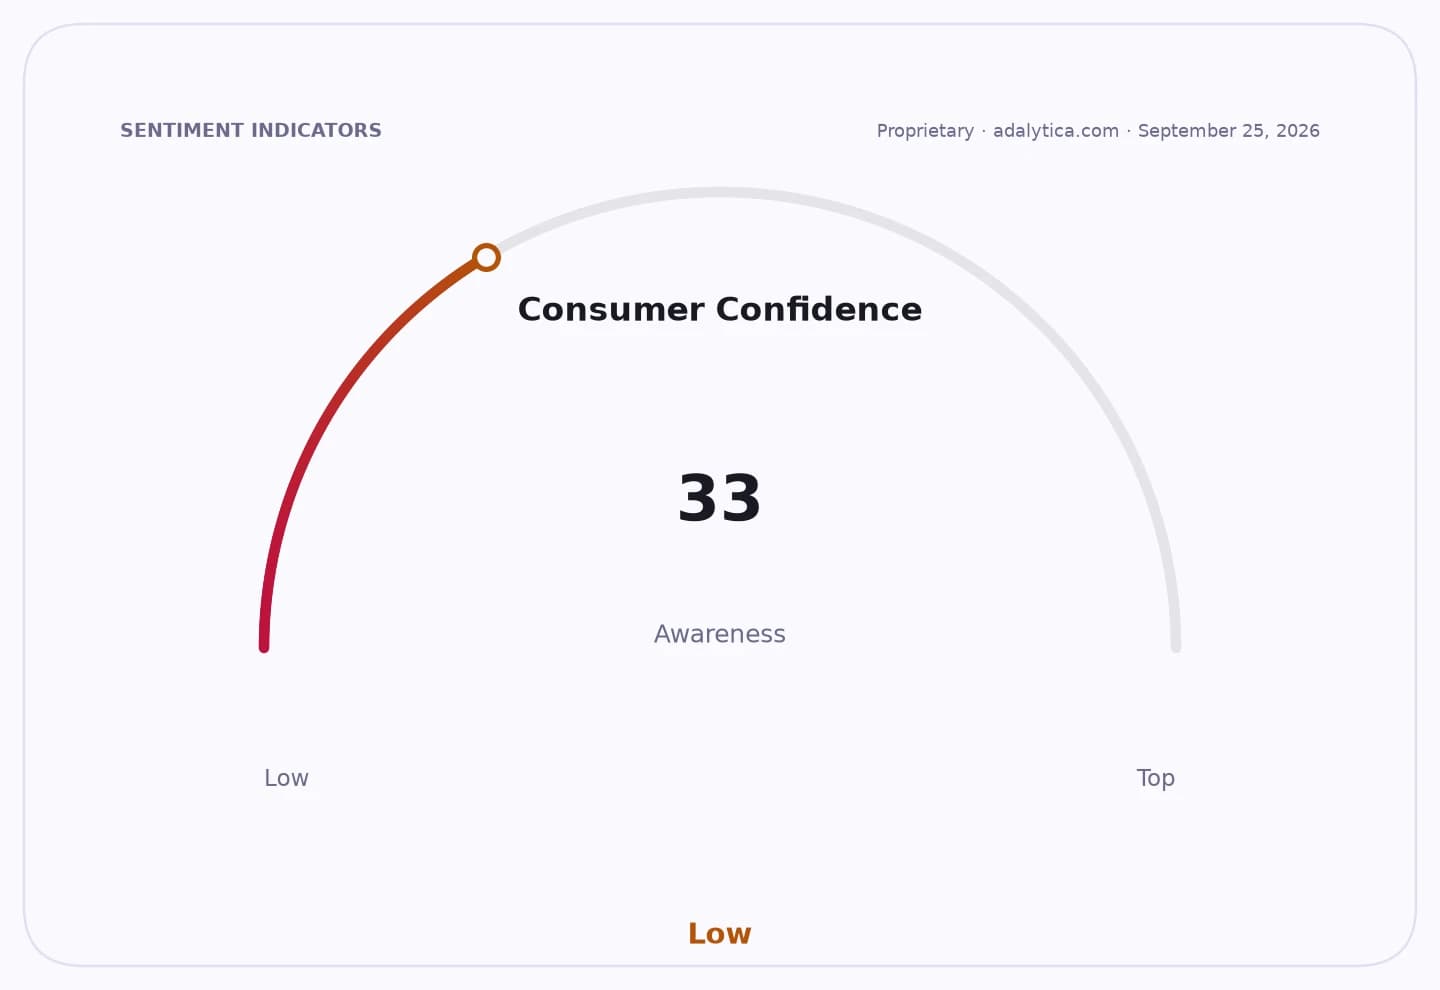
Sentiment IndicatorsⓘProprietary · adalytica.com · October 5, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The broader backdrop is not supportive. Adalytica’s commercial REIT sentiment gauge was neutral at 52, down from 53 on Oct. 3 and 44 on Oct. 4, while awareness remained elevated at 88, indicating the sector is still very much on investors’ radar even as conviction weakens. By contrast, the housing and rent inflation gauge was at 93, or “Extreme Greed,” reflecting persistent concern that residential costs will stay elevated even if transaction activity cools. That divergence matters: it suggests the market expects renters and buyers to keep facing pressure even as owners of listed property assets struggle to re-rate higher.
The theme extends beyond the U.S. ETF. In Romania, a 3-room apartment on Bulevardul Alex cel Bun, listed at 138,000 euros, illustrates how older housing stock in established urban areas is still being marketed on scarcity, location and upgrades rather than cheap financing. The unit, in a 1978 block with improvements and a new lift, is being sold as “fara risc,” or without risk — a phrase that speaks to buyer sensitivity in a market where safety, building quality and liquidity increasingly matter. That kind of pricing discipline fits a wider environment in which real estate sellers are leaning on quality and immediacy, while buyers remain selective.
For investors, the key question is whether this is a cyclical reset or the start of a longer valuation de-rating. Bullish holders will argue that falling rates later in the cycle could support transaction volumes and improve REIT funding conditions. Bears will point to weak technicals, negative momentum and still-sticky housing costs as evidence that property markets are not yet out of the woods. The next catalyst will be whether mortgage and bond yields ease enough to stabilize listed real estate — or whether buyers keep demanding lower prices across both commercial and residential markets.
| Entity | Gains | Losses |
|---|---|---|
| Rental property owners | ▲Higher rent pricing power | ▼Affordability backlash |
| VNQ longs | ▲Potential rebound on rate cuts | ▼Ongoing price weakness |
| VNQ shorts | ▲Momentum and negative technicals | ▼Oversold squeeze risk |
| Homebuyers/tenants | ▲More time to choose selectively | ▼Persistent high housing costs |