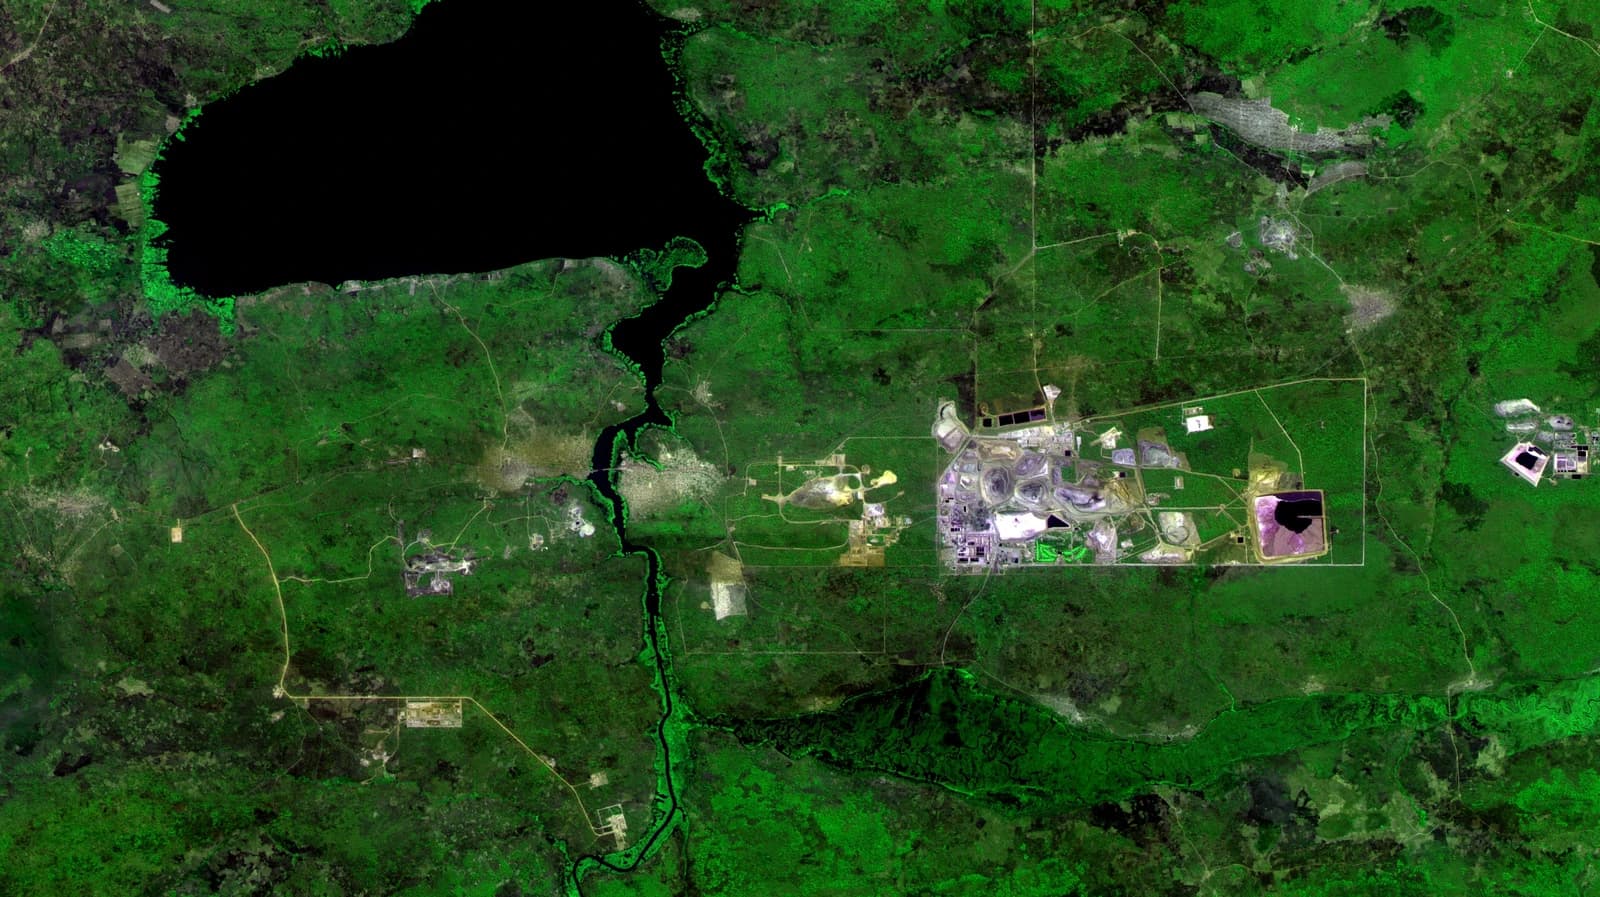
President Donald Trump’s latest semiconductor trade rules may shut a $2.5 billion polysilicon plant in Tennessee, a hit that would ripple through U.S. chip and solar supply chains and underline how Washington’s industrial policy can still backfire on domestic manufacturing.
Wacker Chemie Tennessee Plant Faces Shutdown Risk
Wacker Chemie’s Charleston facility, which employs about 600 people, is at risk after the White House regulations pushed out its last two customers, leaving the German company’s U.S. operation with no viable commercial base. For investors, the bigger issue is not just one factory’s fate: it is that the policy meant to strengthen U.S. supply security appears to be weakening the economics of domestic upstream materials at exactly the moment Washington is trying to reduce dependence on China.
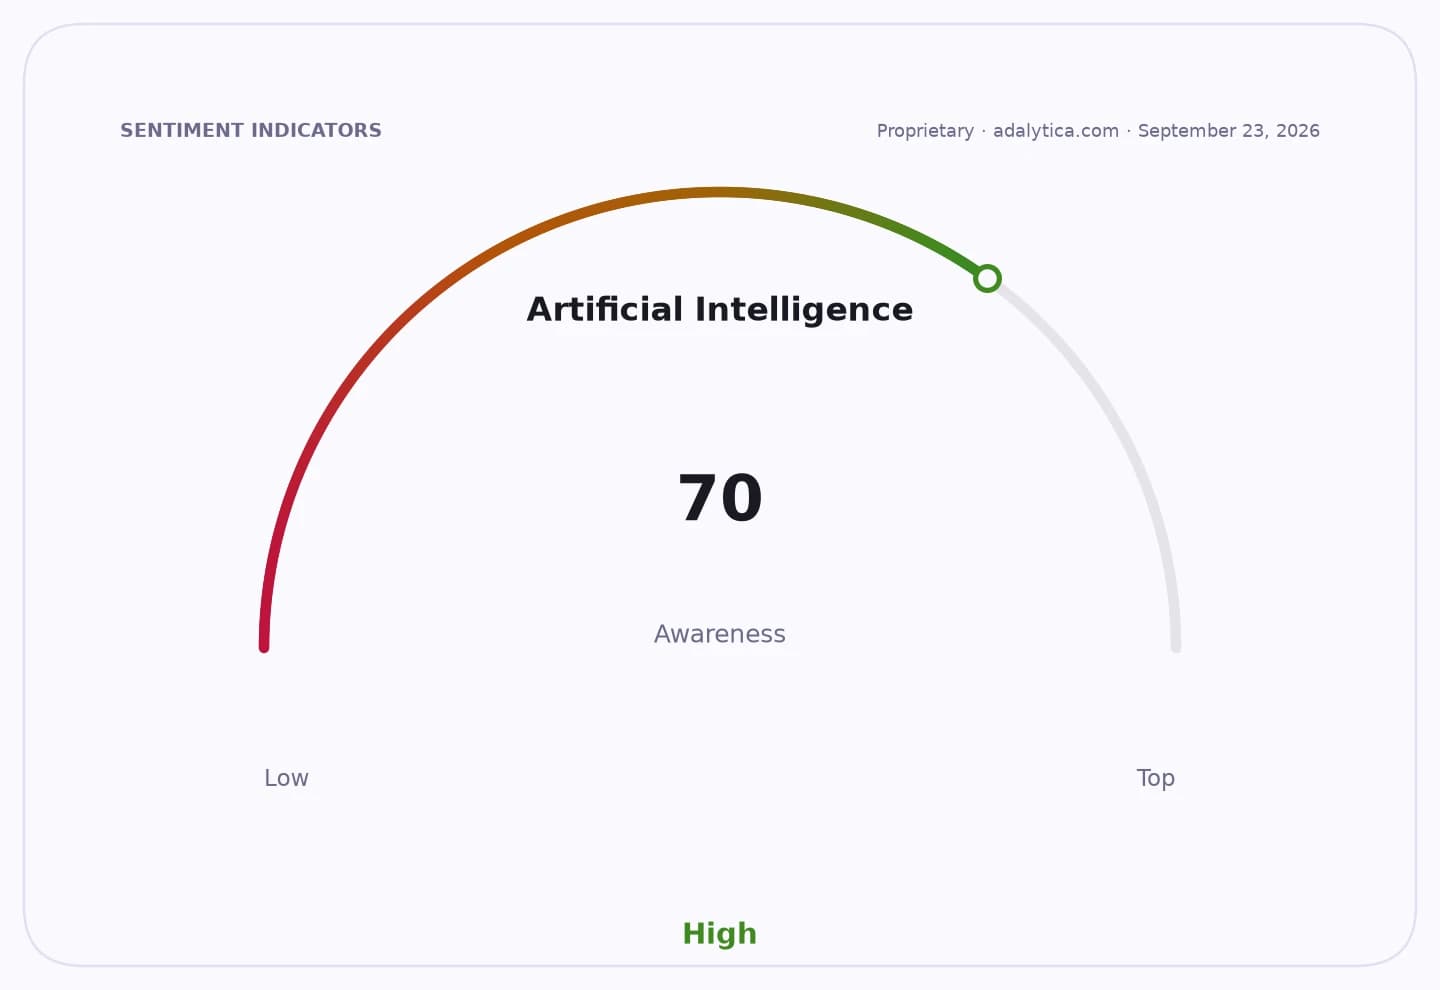
Sentiment IndicatorsⓘProprietary · adalytica.com · September 7, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That matters because polysilicon is a strategic input for both solar panels and, increasingly, advanced semiconductor supply chains. If U.S.-made material is priced at a severe disadvantage — the report says it can be roughly four times more expensive — then price floors and import barriers without a hard domestic-use mandate simply shift demand toward foreign suppliers. In practice, that can leave the U.S. subsidizing capacity that buyers still won’t use.
The market implication is clear: the beneficiaries are low-cost foreign producers and rivals with Chinese ties, while the losers are U.S. industrial assets built around the expectation of policy support. That is why the issue extends beyond Wacker. It speaks to a broader misalignment in U.S. reshoring strategy, where capex follows political rhetoric but not always durable demand.
For semiconductor investors, the story reinforces the need to own the picks-and-shovels winners with real pricing power, not just exposed upstream manufacturing. ETFs such as SOXX and SMH have already recovered sharply from summer weakness, but the latest data show the group is still volatile and sensitive to policy shocks. The market may be underestimating how much of the AI and chip buildout depends on a stable, profitable domestic materials base.
The next catalyst is whether Washington rewrites the rules to force real adoption of U.S. polysilicon or lets economics decide the outcome. If it does not, more “strategic” factories could become stranded assets, and capital will keep flowing to the lowest-cost, best-positioned suppliers rather than the politically preferred ones.
| Entity | Gains | Losses |
|---|---|---|
| Foreign polysilicon suppliers | ▲Lower-cost sales | ▼ |
| Wacker Chemie Tennessee plant | ▲ | ▼Utilization and jobs |
| U.S. chip supply chain | ▲Potential policy rethink | ▼Domestic materials risk |
| SOXX / SMH investors | ▲Long-term reshoring optionality | ▼Policy-driven volatility |