Yinson Holdings is tapping the bond market for $1.46 billion to refinance funding tied to its Agogo floating production storage and offloading vessel, a move that underscores how capital-intensive offshore oil infrastructure remains heavily reliant on debt markets even as project cash flows come into view.
Yinson Holdings to refinance Agogo FPSO with bonds
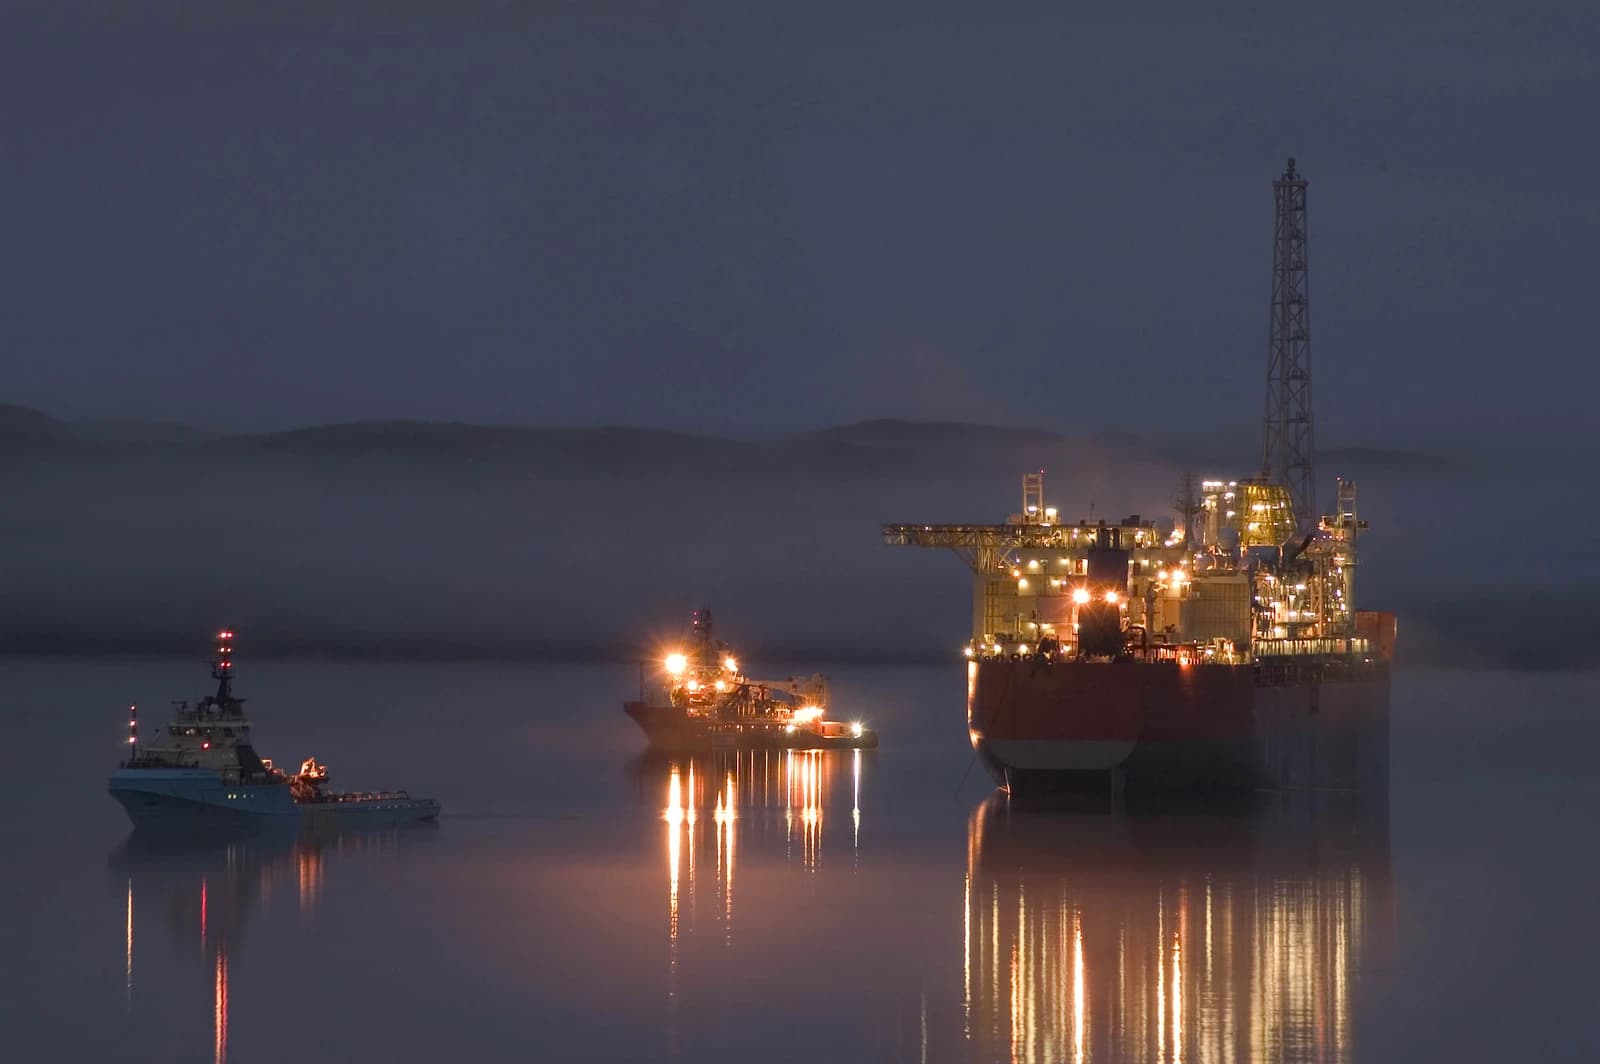
The refinancing matters because FPSO projects sit at the intersection of long-duration energy demand, engineering risk and balance-sheet strain. By replacing or extending earlier financing, Yinson can reduce near-term pressure on liquidity and better match debt service to the life of the Agogo contract, improving visibility on cash generation. For investors, that lowers execution risk around one of the group’s flagship assets and helps determine whether the company can keep financing growth without diluting equity holders or stretching leverage.
Agogo is part of Yinson’s broader offshore production portfolio, which has become increasingly important as the company positions itself as a recurring-income energy infrastructure player rather than a pure project builder. That shift depends on being able to lock in long-tenor funding at rates that do not overwhelm returns. A successful bond sale would also signal that credit markets remain open to large offshore energy assets, even in an environment where higher-for-longer funding costs continue to punish weaker balance sheets.
The deal lands at a time when global financing conditions remain uneven. Yinson’s ability to place a multibillion-dollar issue will be read as a test of appetite for asset-backed energy debt, particularly in a market that has recently been more selective on capital-intensive industrial and energy names. A strong reception could support further refinancing across the FPSO sector; a weak one would raise questions about funding costs and whether project economics remain attractive once debt is repriced.
For shareholders, the key issue is not just whether the bond sale clears, but on what terms. Tighter pricing would preserve equity value and support future dividends and growth investment. Wider spreads, by contrast, would eat into returns and could force management to slow expansion or reconsider its funding mix. The refinancing therefore goes beyond one vessel: it is a read on Yinson’s financing model, the resilience of offshore energy cash flows and the market’s willingness to fund long-dated oil infrastructure.
| Entity | Gains | Losses |
|---|---|---|
| Yinson | ▲Refi flexibility | ▼Higher interest burden |
| Bond investors | ▲Asset-backed yield | ▼Offshore project risk |
| Equity holders | ▲Lower near-term pressure | ▼Dilution risk if funding tightens |
| FPSO sector | ▲Better funding signal | ▼Weaker access if deal misprices |