Altyn Bank has launched a new mortgage program, “Altyn Uya,” designed to lower the upfront cash hurdle for homebuyers in Kazakhstan at a time when affordability remains a binding constraint on demand for housing finance.
Altyn Bank launches Altyn Uya mortgage program
The economic significance lies in the structure. Instead of requiring families to spend years building up a down payment in a savings scheme, the bank lets customers apply for a mortgage first, secure approval, and then place a guaranteed deposit starting at 20% of the property value. The bank lends against the full home price, while the deposit remains the borrower’s property and accrues 0.1% interest until maturity, when it is used to reduce the remaining principal. That makes the product closer to an immediate purchase financing tool than a traditional accumulation model, and it directly addresses one of the biggest frictions in mortgage markets: the time gap between wanting to buy and being able to assemble cash.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 8, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For borrowers, the appeal is obvious. The mortgage rate ranges from 7% to 16%, with an APR from 7.23% to 17.23%, terms extend up to 15 years, and loans can reach as much as 175 million tenge. Altyn Bank also said the structure allows for partial or full early repayment from the day after the loan is issued, which improves flexibility for households whose incomes may rise over time. By promising a fixed rate for the life of the loan, the bank is also trying to reduce refinancing uncertainty — a useful feature in a market where households are often exposed to changing funding conditions and policy rates.
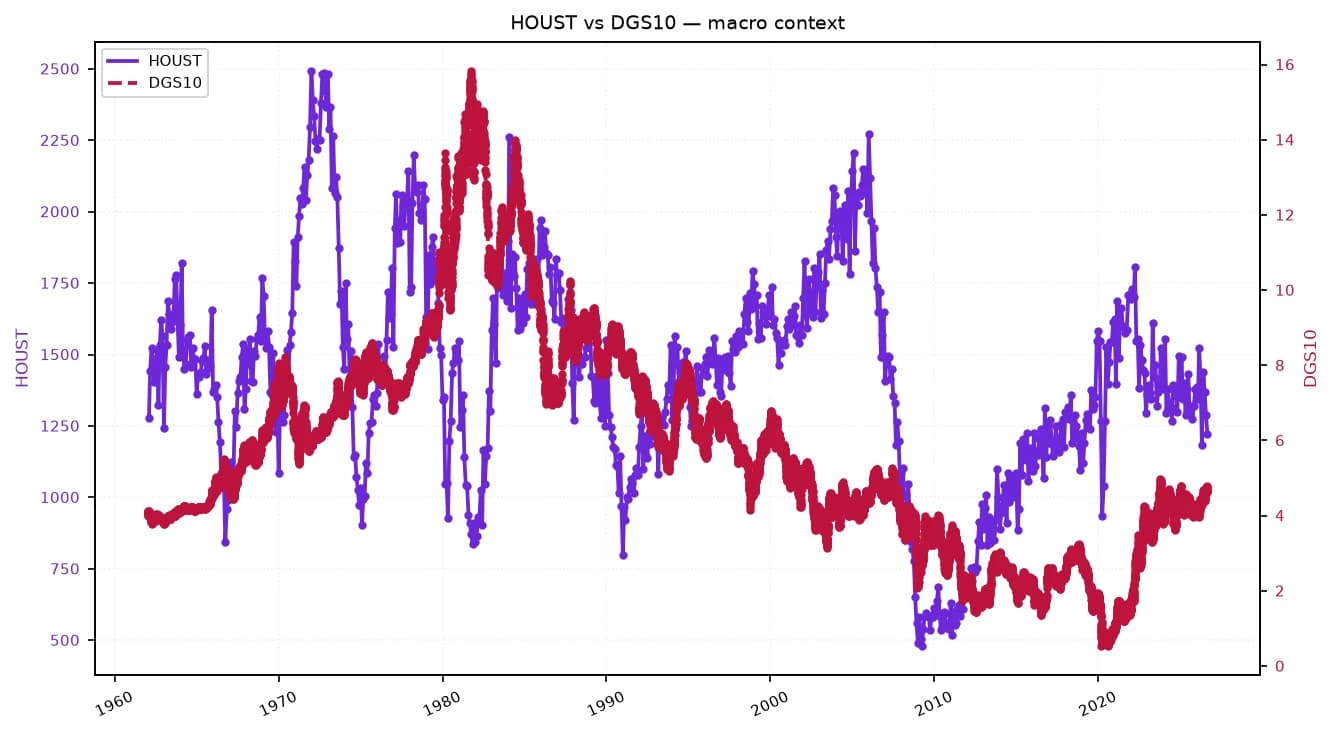
The launch comes against a broader backdrop of persistent pressure in the housing market. U.S. data in the context underscores the long-running tension between housing activity and financing costs: housing starts were forecast at 1,278.5 in September after a volatile run, while U.S. home prices have kept rising on a year-on-year basis even as affordability has tightened. In Kazakhstan, the issue is less about U.S.-style mortgage cycles and more about access. A product that cuts the waiting period for a home purchase could support transaction volumes in both the primary and secondary housing markets, and later in shared-equity and under-construction purchases once partner developers are added.
For investors, the story is about mortgage growth, margin discipline and credit quality. Altyn Bank is widening its product line in a segment that is typically sticky and balance-sheet intensive. If the program gains traction, it could lift loan growth and deepen customer relationships, but it also raises the usual risks around housing-cycle sensitivity and the bank’s ability to price long-duration fixed-rate credit while funding costs move around. The 20% deposit requirement provides some protection, yet the product still broadens exposure to property values and household repayment capacity.
The competitive implication is that Altyn Bank is trying to differentiate itself on ease of access rather than pure rate cutting. If it can build a network of construction partners, the bank could position “Altyn Uya” as a more complete housing-finance platform and win share from lenders that still force customers to save first and buy later. The key test will be whether the program can scale without sacrificing underwriting standards in a market where affordability is already stretched.
| Entity | Gains | Losses |
|---|---|---|
| Altyn Bank | ▲mortgage share | ▼simpler rivals |
| Homebuyers | ▲faster access | ▼long savings plans |
| Partner developers | ▲more demand | ▼slower sales channels |
| Competing lenders | ▲little immediate gain | ▼product differentiation |