Mortgage lenders in Austin are seeing a better flow of approvals and home sales, but the more important shift for the market is that credit stress is building at the same time, with bad loans up 14.8% in the first half of 2026.
Austin mortgage lenders see approvals rise as bad loans grow
That combination matters because Austin’s housing market has been supported by a steady labor market and still-firm home values, yet affordability remains stretched. Easier lending conditions can lift transaction volumes, but they also tend to expose lenders to higher future losses if borrowers are already carrying payments that absorb a growing share of income. For banks and mortgage originators, that is the difference between short-term fee growth and a more expensive credit cycle later on.
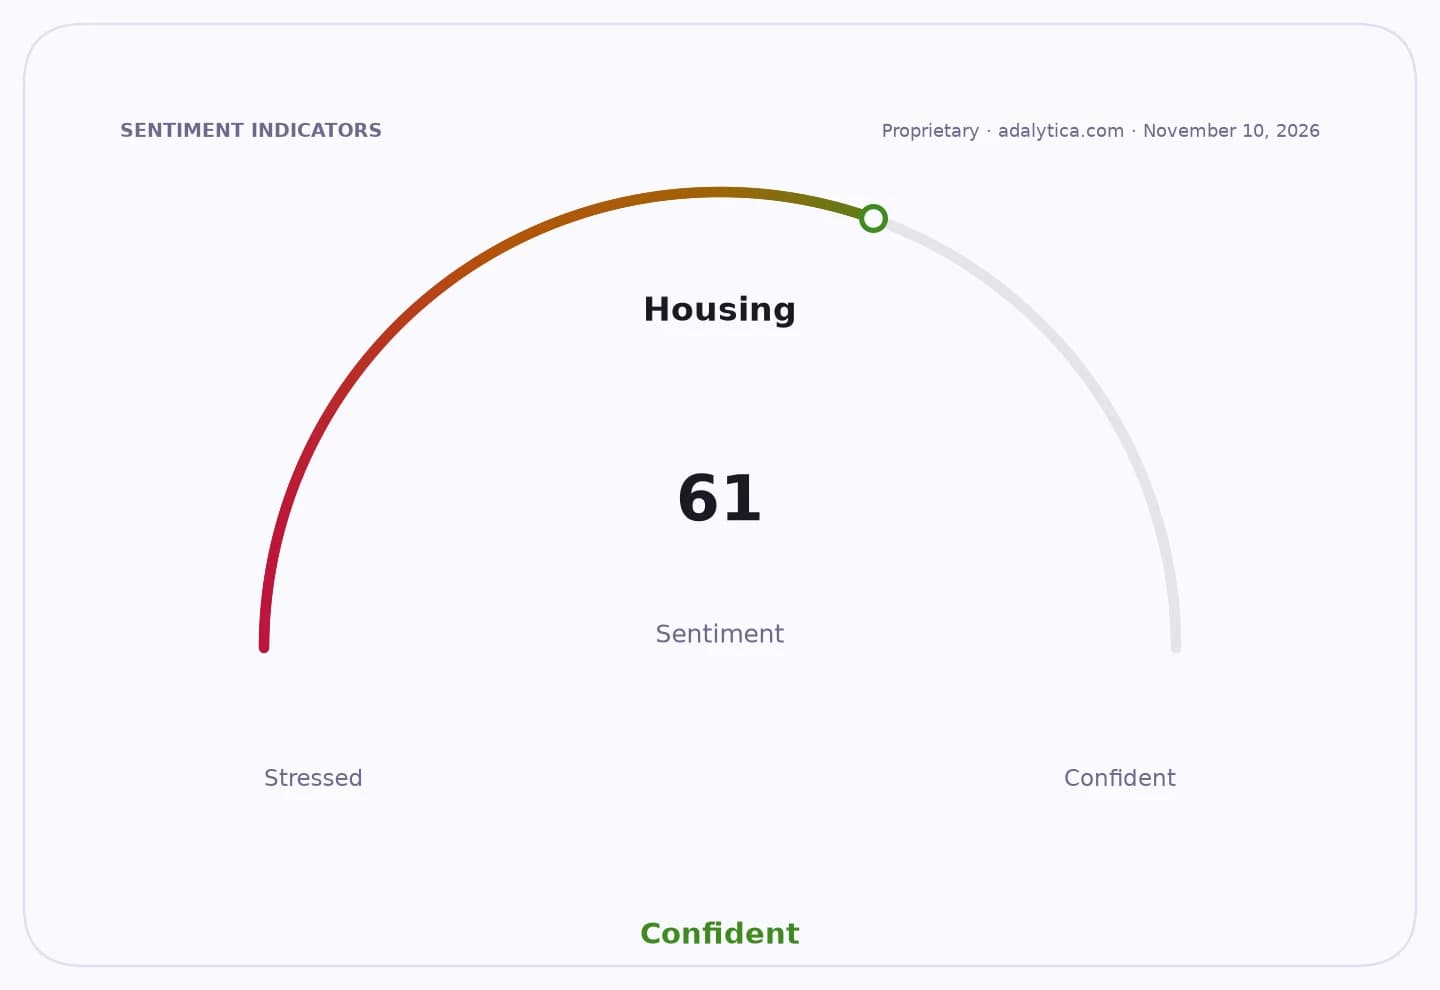
The latest signals point to exactly that tension. Mortgage approvals have increased and August home sales showed notable growth, suggesting demand is responding to better financing access. But the rise in delinquent and problematic loans shows that some households are reaching the limit of what they can service. In a market like Austin, where prices rose sharply in recent years and borrowing costs remain elevated by historical standards, even modest income pressure can quickly show up in late payments.
For lenders, the near-term bull case is straightforward: more approvals mean more originations, more refinancing activity and stronger volumes across mortgage desks. Banks with broader balance sheets can also use the rebound in housing activity to deepen customer relationships and cross-sell deposits, card products and wealth services. For homebuyers, looser conditions may open a window to get into the market before prices rebound further.
The bear case is more consequential. A 14.8% increase in bad loans in just six months suggests underwriting standards, borrower budgets or both are under pressure. If that trend continues, lenders may face higher loss provisions, tighter standards and lower appetite for marginal borrowers, which would slow the rebound in sales and undermine affordability gains. Regulators may also take a closer look if stress migrates beyond a handful of borrowers into a broader pattern.
The market message is that Austin housing is not simply healing; it is repricing risk. Investors should watch whether credit deterioration continues even as approvals improve, because that would indicate lenders are growing into a weaker asset-quality environment rather than a durable recovery. The key catalysts will be default rates, regulatory response and whether lower mortgage rates or income growth can offset the pressure on household finances.
| Entity | Gains | Losses |
|---|---|---|
| Austin mortgage lenders | ▲Higher approval volumes | ▼Rising credit losses |
| Homebuyers | ▲Easier access to loans | ▼Greater debt burden |
| Home sellers | ▲Stronger demand | ▼More price sensitivity |
| Regulators | ▲More incentive to monitor risk | ▼Less room for complacency |