Credit-card lenders are getting a lift as fresh data point to softer household stress, even as consumer finances remain under pressure and investors stay alert for any turn in delinquencies. Capital One, American Express and Mastercard have all outperformed in recent sessions, reflecting bets that consumers are still spending and that charge-off risk is not worsening as fast as feared.
Capital One, AmEx, Mastercard Rally on Softer Debt Stress
Debt Stress Indicators
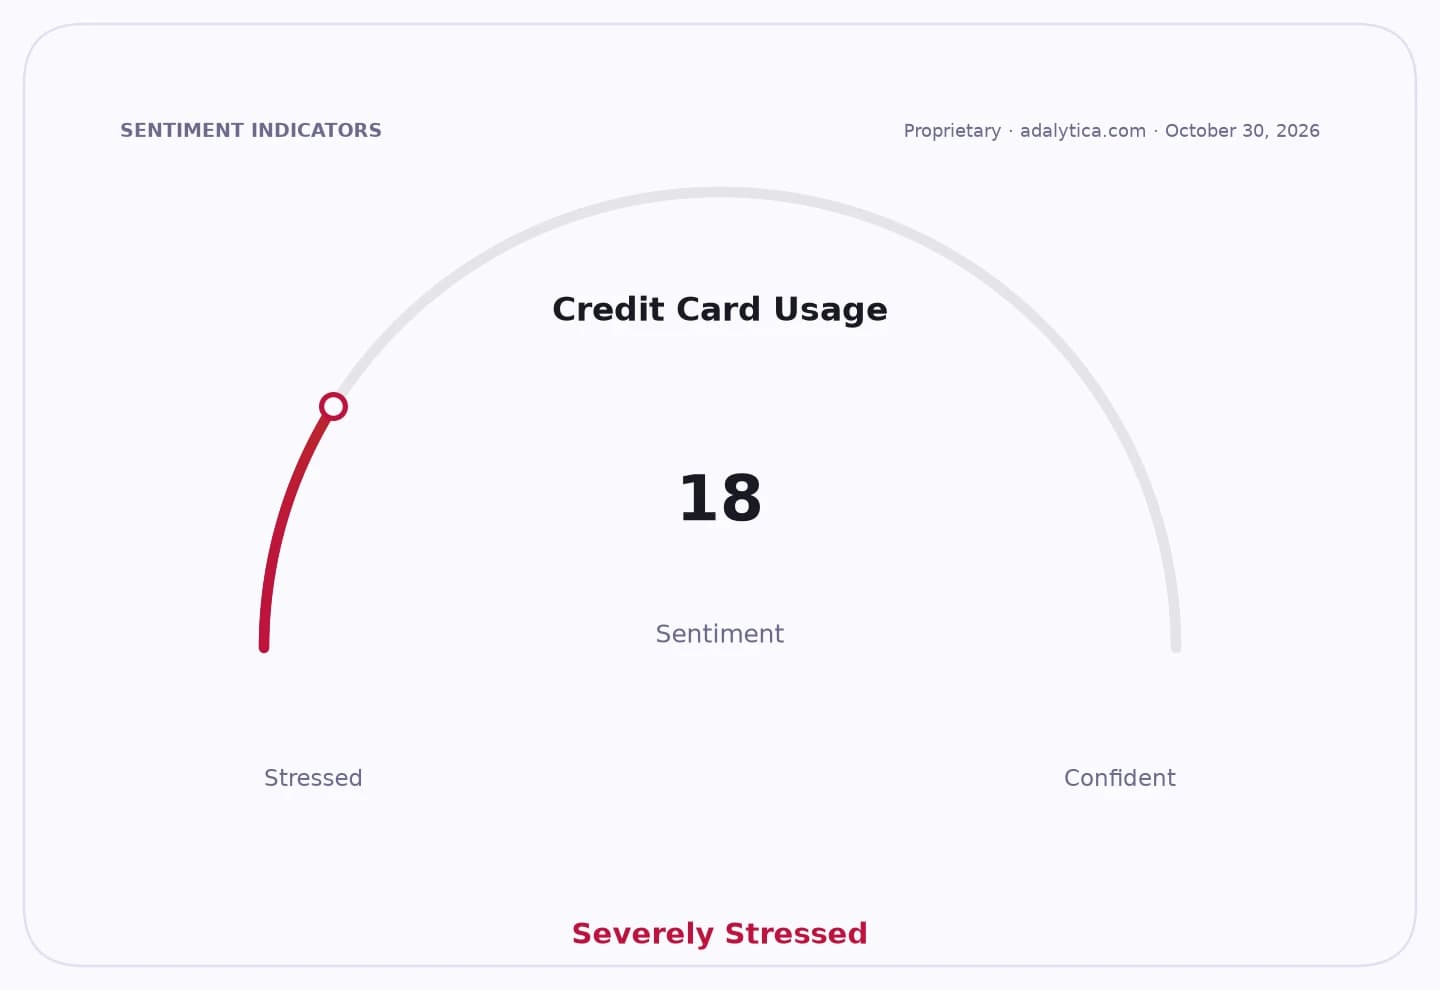
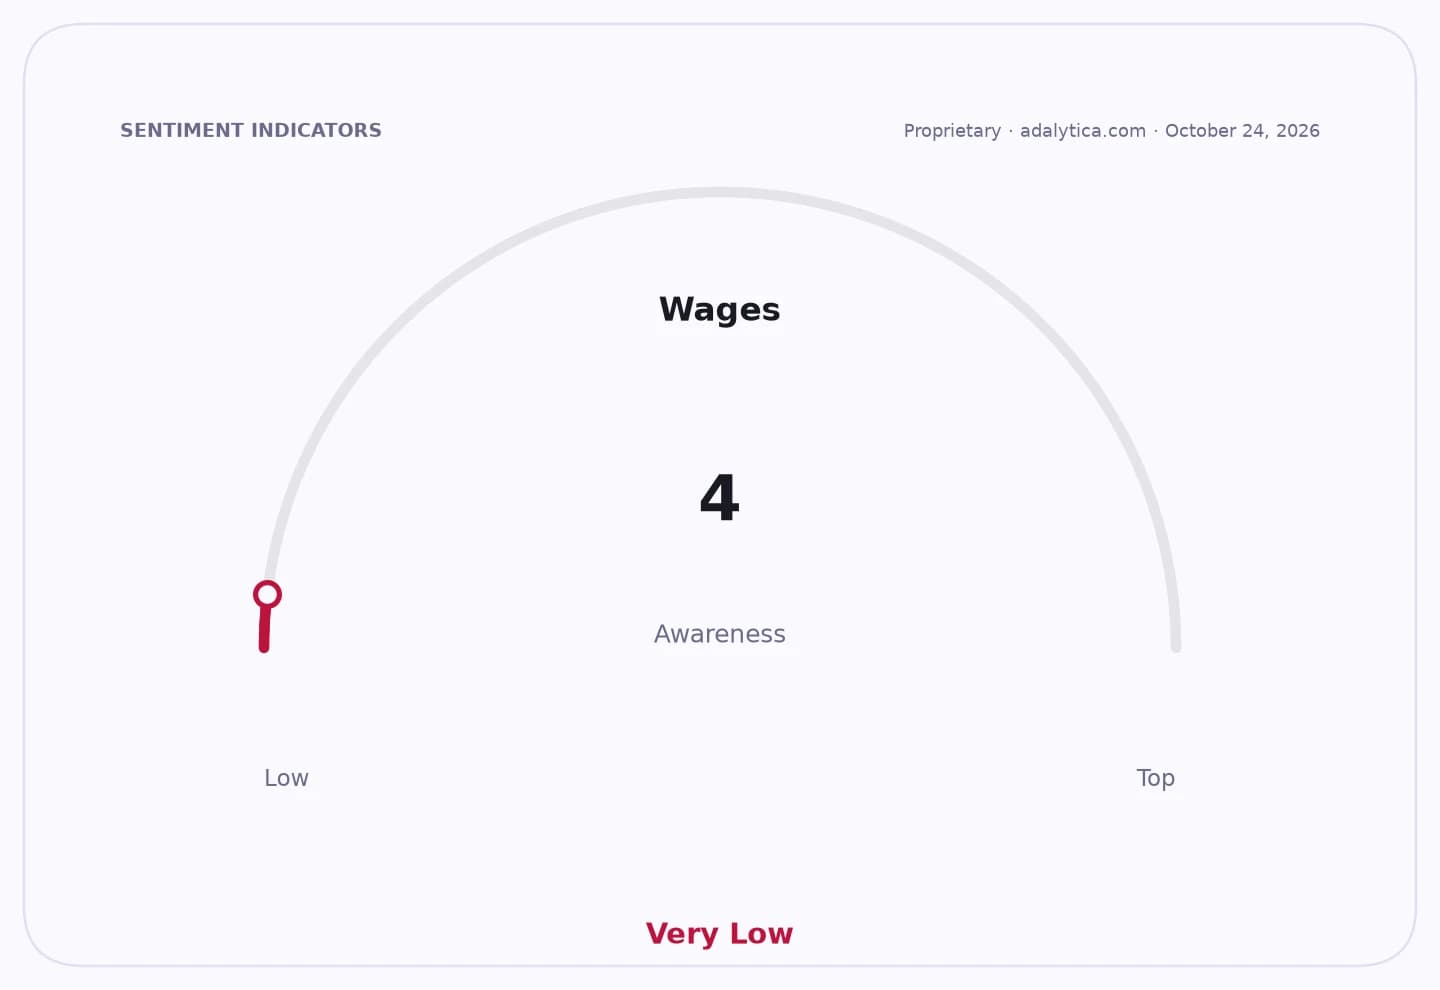
The latest read on household debt stress from Adalytica shows sentiment at 29, labeled “Fear,” but that is still off the extreme lows seen in early November and suggests the panic around consumer leverage has eased. Household savings-rate sentiment sits at 68, while awareness remains elevated at 79, a sign investors and consumers are still watching balance-sheet strain closely.
Sentiment Indicators
That matters because card issuers live and die by the health of the borrower. Capital One’s recent price action has been constructive, with the stock ending Nov. 3 at $208.58, above both its 50-day moving average of $204.39 and 200-day average of $199.99, while American Express closed at $326.39, also above its 50-day and 200-day averages. Mastercard finished at $649.53, above its 50-day average of $588.72 and 200-day average of $535.39, underscoring investor confidence in payment volume and credit quality.
The macro backdrop is mixed but not recessionary. The unemployment rate is forecast at 4.09% for October, from 4.2% in September, while the fed funds rate is seen at 3.89% next month. That combination points to a labor market that is cooling only gradually and monetary conditions that remain restrictive enough to keep pressure on revolving credit, but not so tight that it is derailing consumer spending.
Debt Stress Indicators — 30-day sentimentadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.
For lenders, the key issue is whether borrowers keep swiping or start missing payments. American Express warned in its latest filing that future credit performance depends in part on unemployment, GDP and consumers’ willingness to pay, while Capital One flagged the same risks around delinquencies, reserve builds and write-offs. Investors will be watching upcoming monthly credit-card performance data and year-end commentary for signs that the recent stabilization in consumer sentiment can hold.
| Entity | Gains | Losses |
|---|---|---|
| Capital One | ▲Lower perceived credit risk | ▼Less upside if spending slows |
| American Express | ▲Stronger investor sentiment | ▼Higher loss risk if delinquencies rise |
| Mastercard | ▲Durable payment volumes | ▼Slower transaction growth if consumers pull back |
| Overleveraged consumers | ▲Short-term relief from easing fear | ▼Continued pressure from high borrowing costs |