Chile’s main stock index was poised to extend its losing streak to a seventh session on Friday as stronger-than-expected relief from a weak US jobs report failed to push long-term Treasury yields lower for good.
Chile IPSA Falls as US Yields Stay High
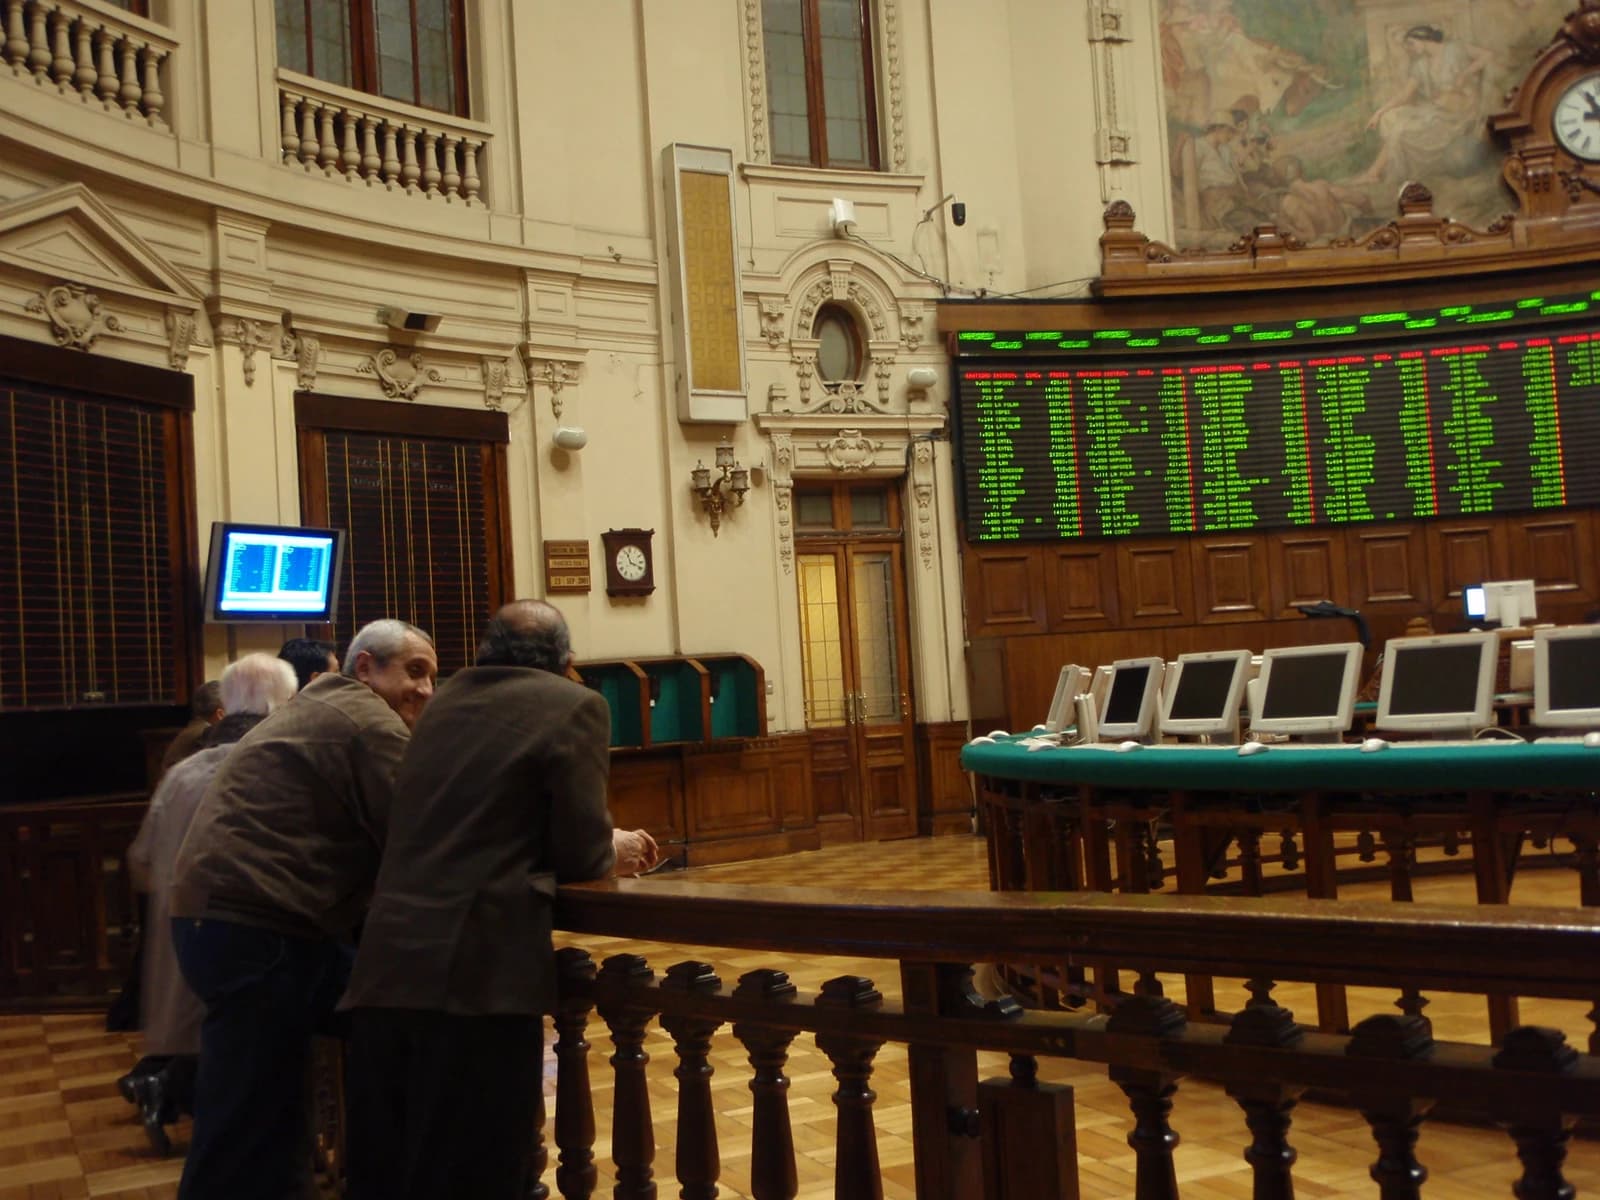
The MSCI IPSA slipped 0.3% to 10,879.59 in early afternoon trade after an opening bounce quickly faded, with gains in most of its 31 constituents overwhelmed by declines in heavyweight names Santander, Bci, Cencosud and Falabella. The move underscored a broader shift in global markets: investors are no longer treating softer US labour data as enough to restore the easy-money rally, because the real market constraint remains the level of long-dated rates.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 3, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That matters far beyond Chile. The 10-year US Treasury yield was at 5.28% and the 2-year at 3.99%, leaving a still-steep but uncomfortable curve and showing how little the weaker payrolls print did to change the rates backdrop. The 10-year yield has been grinding near multi-decade highs, a problem for equity valuations worldwide because it lifts the discount rate used on future earnings and squeezes financial conditions even when growth data softens.
The latest US non-farm payrolls report showed only 29,000 jobs created in September versus 90,000 expected, while prior months were revised down by a net 60,000 and unemployment edged up to 4.2%. Normally that kind of data would reinforce expectations for a more dovish Federal Reserve and support duration assets. Instead, Treasury prices briefly rallied and then reversed, as markets refocused on inflation, heavy funding needs and persistent demand for capital tied to artificial intelligence investment.
That reversal is exactly what has kept pressure on Latin American equities. Chile is particularly exposed because its market is dominated by rate-sensitive banks, retailers and domestic cyclicals that tend to weaken when global yields stay elevated and foreign capital becomes more selective. The peso was also under pressure, with USD/CLP rising to 989.6, adding another layer of caution for local investors and foreign buyers weighing returns in dollar terms.
Markets had already been pricing a smaller chance of another Fed rate increase this month, with money markets putting the probability at about 20%, down from nearly 30% on Thursday. That shift reflects a broader belief that the Fed is closer to the end of its tightening cycle. But for equities, especially in smaller and emerging markets, the more immediate question is not whether the Fed hikes again, but whether US long rates can stop rising. As long as they do not, the valuation ceiling on stocks stays low.
That tension also explains why Chilean shares could not hold on to their initial gains even as Wall Street rose and European benchmarks recovered part of the previous day’s losses. Brent crude’s decline to $100.50 a barrel and the pullback in diesel after the G7’s planned release of up to 100 million barrels offered some relief on the inflation side, but it was not enough to offset the rates shock. For investors, the message is that softer US data alone is no longer a reliable catalyst for broad risk-taking until the long end of the curve stops acting as the market’s main source of stress.
| Entity | Gains | Losses |
|---|---|---|
| US Treasury bulls | ▲Eventually benefit if yields peak | ▼Hurt by continued yield spike |
| Chilean exporters | ▲Gain from weaker peso | ▼Hurt by local equity pressure |
| Chilean banks/retailers | ▲— | ▼Lose from higher global rates and risk aversion |
| Fed doves | ▲Gain credibility from weak payrolls | ▼Lose if long rates keep tightening conditions |