China’s consumer inflation edged up to 0.9% in September, but the modest rise does little to dispel worries that the world’s second-largest economy is still flirting with deflation and needs more policy support to revive domestic demand.
China CPI Rises to 0.9% in September
The reading was better than outright stagnation, yet it remains far below levels that would suggest broad pricing power in the household sector. That matters because consumer inflation is the clearest gauge of whether Chinese households are spending enough to give companies room to lift prices and margins. The latest data instead points to an economy still reliant on exports and policy support, rather than self-sustaining private consumption.
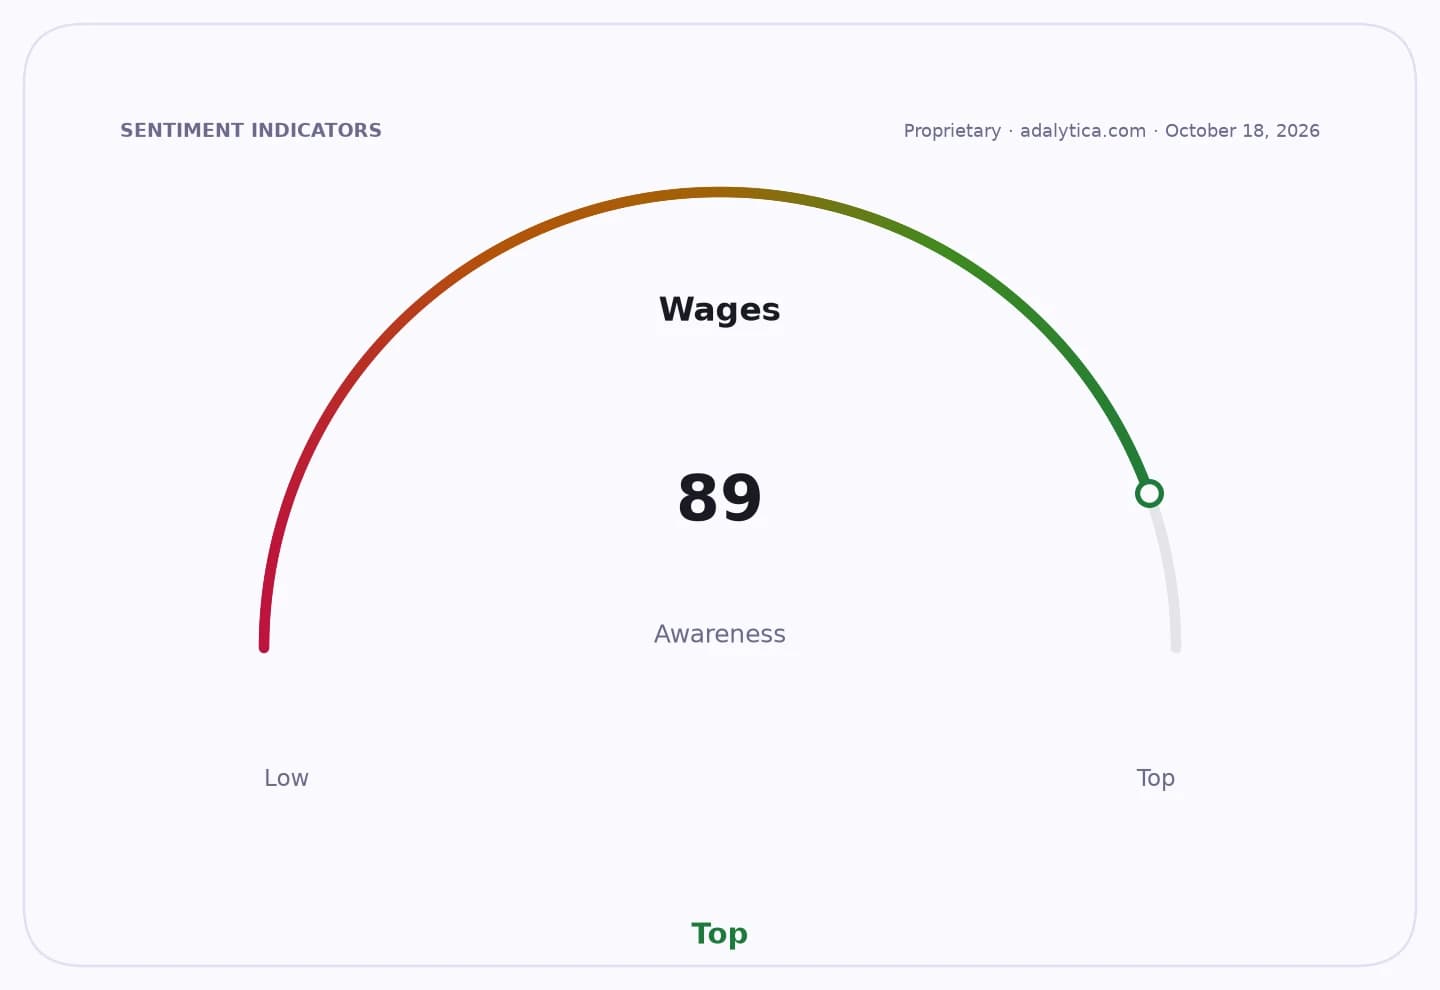
Sentiment IndicatorsⓘProprietary · adalytica.com · October 20, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The contrast with producer prices is stark. Factory-gate inflation has been running hotter, helped by supply-side factors and stronger external demand, but that has not translated into meaningful consumer price pressure. For policymakers, that split is uncomfortable: it suggests firms may be absorbing costs or moving goods abroad instead of passing gains through to Chinese consumers. It also reinforces the view, echoed by the IMF, that Beijing may need to do more on the fiscal side to bolster household demand.
For investors, the implications are mixed. A subdued CPI environment gives the central bank room to keep policy relatively accommodative, which is supportive for duration-sensitive assets and for sectors tied to domestic spending if stimulus arrives. But it also underscores the earnings risk for companies exposed to China’s local consumer market, from retailers to discretionary brands, where pricing power remains weak.
The market backdrop reflects that caution. China-focused exchange-traded funds have remained under pressure, with the FXI and KWEB both trading below their 200-day moving averages, while the leveraged YINN fund has been volatile, highlighting how quickly optimism about stimulus or growth can reverse. In technical terms, the recent weakness in those funds has come alongside softer RSI readings and negative MACD momentum, consistent with fading conviction rather than a decisive turnaround.
The broader narrative is that China’s growth model is still leaning too heavily on exports and industrial output while household demand lags behind. September’s inflation uptick is not enough to change that story. What investors will watch next is whether Beijing responds with larger fiscal transfers, support for services consumption or other targeted measures that can lift the consumer side of the economy before deflationary pressures become more entrenched.
| Entity | Gains | Losses |
|---|---|---|
| Chinese policymakers | ▲More room for stimulus | ▼Pressure to act on demand |
| Domestic consumers | ▲Potential fiscal support | ▼Weak pricing power persists |
| Exporters/industrial firms | ▲Stronger external demand | ▼Local demand stays soft |
| China-focused equities | ▲Easier policy backdrop | ▼Earnings growth remains fragile |