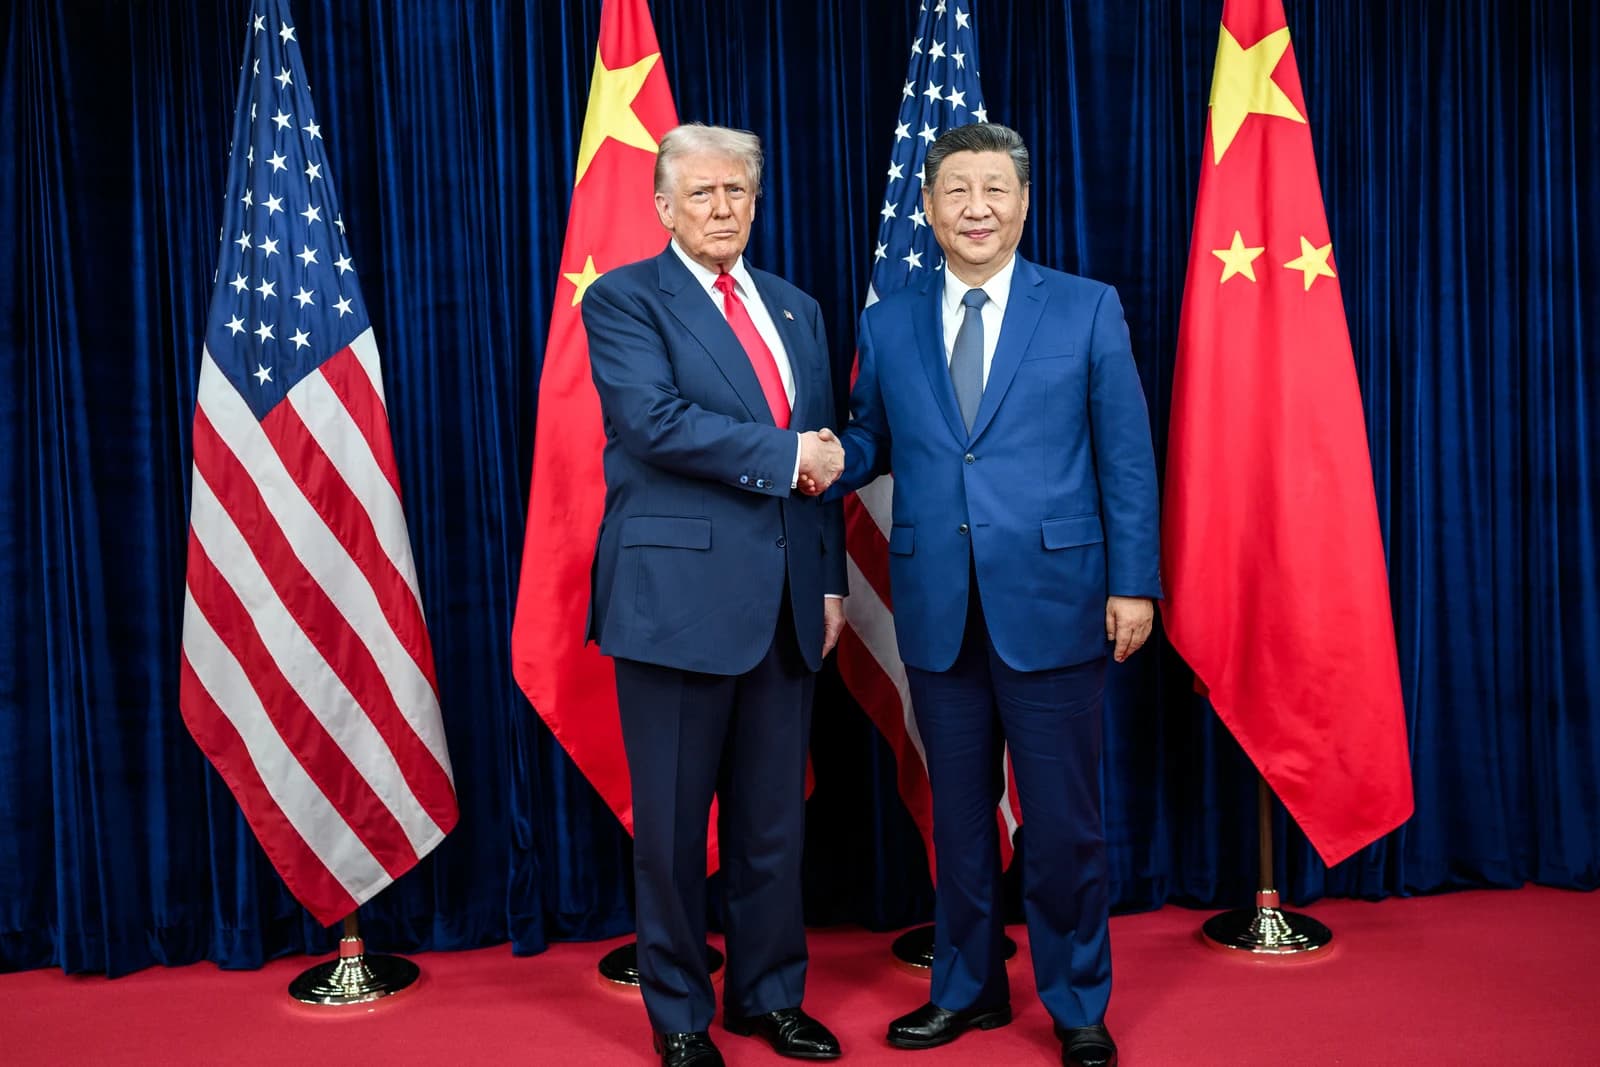
The United States has shut down five cultural-exchange programs with China, a move that deepens a widening policy break between Washington and Beijing and underscores how quickly non-military ties are being stripped back as the Trump administration leaves office.
U.S. shuts five China cultural exchange programs
The State Department said the programs were being used as Chinese propaganda and had no clear benefit to the U.S., making the latest step part of a broader effort to tighten scrutiny on China’s soft-power reach. It follows new visa restrictions that limit stays in the U.S. for members of China’s Communist Party, adding another layer of friction to an already strained relationship.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 20, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The economic significance is less immediate than a tariff hike or export ban, but it still matters. Cultural exchanges, educational links and people-to-people programs are among the lowest-cost channels for stabilizing bilateral relations. Closing them narrows the diplomatic off-ramps available just as the two economies remain deeply intertwined in trade, technology and capital flows. When those channels weaken, the risk premium around policy surprises tends to rise, from investment screening to visa rules to sector-specific restrictions.
For investors, the message is that U.S.-China relations remain a live geopolitical risk rather than a background issue. China-facing assets have already reflected that tension: the FXI China ETF has fallen to 33.53 from 35.88 in early September, while the leveraged YINN fund has dropped to 23.63 from 29.71 over the same period, even as both trade below their 200-day moving averages. FXI’s relative strength index sat at 46.3 on Oct. 19, suggesting neither oversold panic nor a strong rebound, while YINN’s RSI was 44.7, indicating only limited momentum despite recent volatility.
US-China Relations — 30-day sentimentadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
The policy move also fits a broader pattern of hardening economic boundaries. U.S. companies with exposure to China have repeatedly warned that sanctions, export controls and geopolitical shifts can affect demand and supply chains. That risk is especially relevant for semiconductors, cloud infrastructure and other sectors where Washington has already tightened rules. Any further deterioration in relations could reinforce pressure on companies with China revenue, including multinationals that depend on cross-border business travel, licensing and local partnerships.
The strategic narrative is straightforward: Washington is reducing the scope for engagement while keeping pressure on Beijing in areas it views as national security vulnerabilities. That may please hawkish lawmakers and officials who see cultural programs as instruments of influence, but it leaves little room for confidence-building at a time when regional flashpoints are also intensifying. For markets, the next catalyst will be whether the rhetoric spills into more material measures affecting trade, technology or capital access.
| Entity | Gains | Losses |
|---|---|---|
| U.S. hardliners | ▲tougher line on China | ▼fewer diplomatic channels |
| Chinese government | ▲domestic propaganda response | ▼softer access to U.S. ties |
| FXI / YINN longs | ▲tactical volatility opportunities | ▼weaker China sentiment |
| Multinationals with China exposure | ▲clearer policy pricing | ▼higher geopolitical risk |