China Telecom Corporation Limited is leaning harder into 5G infrastructure with a strategic partnership that underscores how China’s state carriers are still spending to defend network share and support industrial demand, even as the sector’s stocks remain technically weak.
China Telecom 5G Partnership, Shares Oversold
The move matters because 5G buildouts are capital-intensive and tied to longer-dated revenue streams from enterprise connectivity, cloud services and private networks. For China Telecom, partnerships can help spread costs, accelerate deployment and improve access to equipment and network resources in a market where scale and policy backing often determine winners.
That backdrop is showing up in the stock. China Telecom’s Hong Kong-listed shares closed at HK$10.05 on Aug. 18, extending a decline from HK$11.68 in mid-July and leaving the stock below both its 50-day moving average of HK$11.21 and its 200-day moving average of HK$11.54. The relative strength index was 19.4, a level that typically indicates deeply oversold trading, while the MACD remained negative, suggesting momentum is still fragile.
For investors, the partnership reinforces the view that China’s telecom majors are being pushed to balance spending discipline with strategic investment. The sector benefits from policy support for digital infrastructure, but higher capex can weigh on near-term cash generation and limit room for capital returns, even as it builds longer-term revenue optionality.
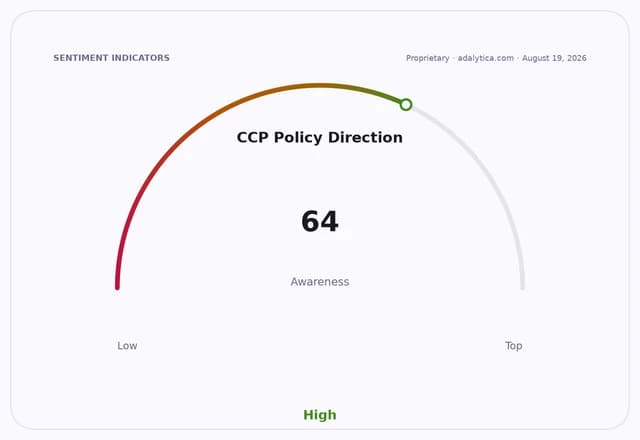
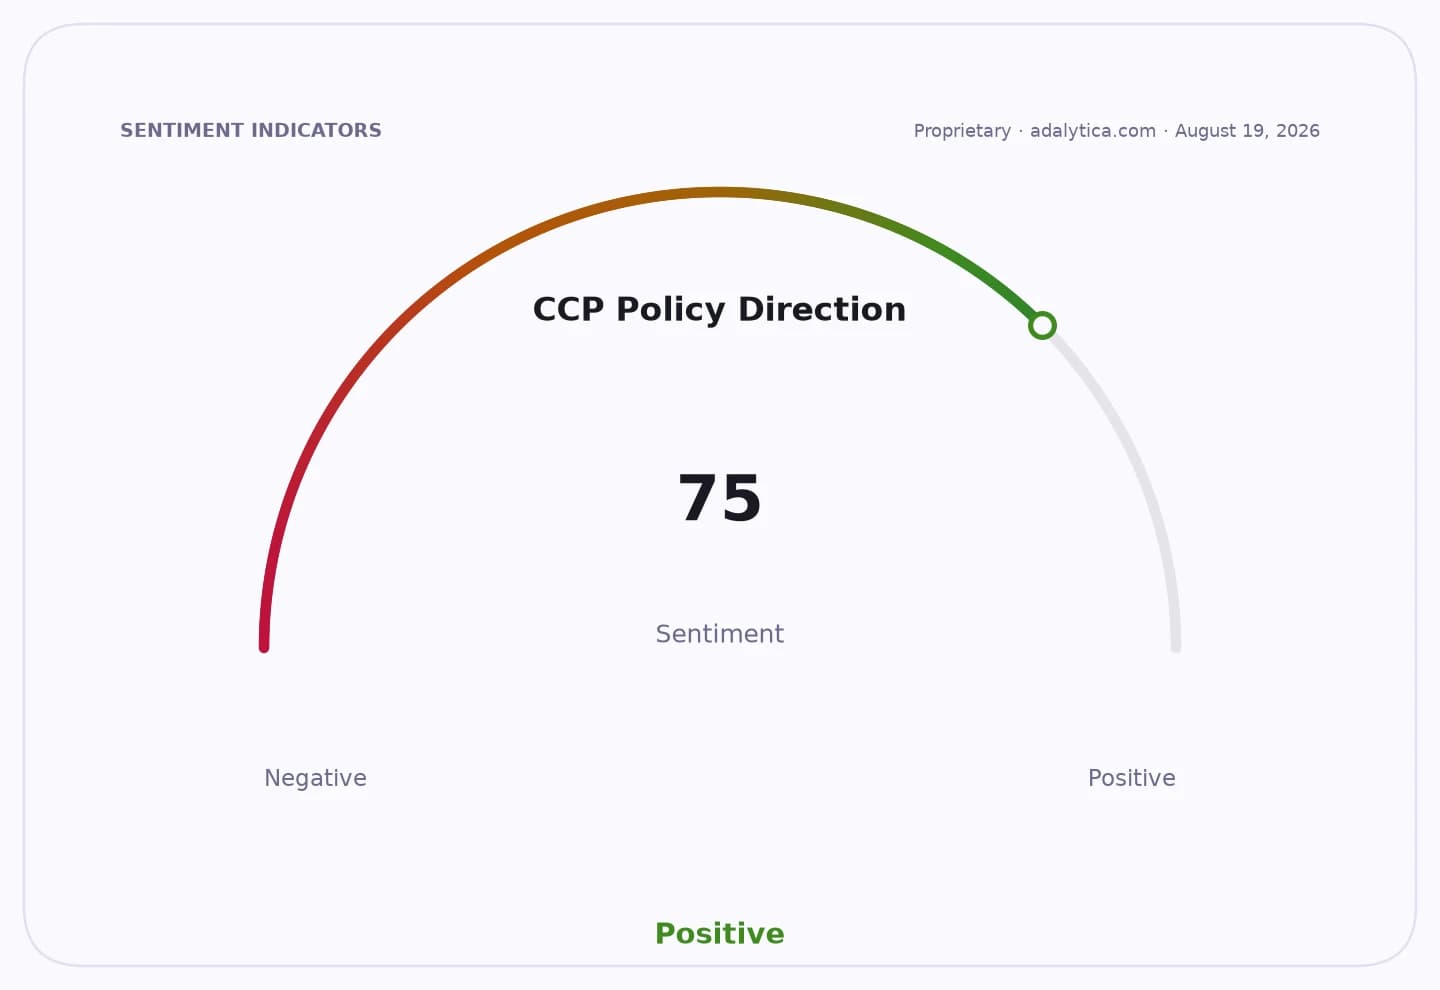
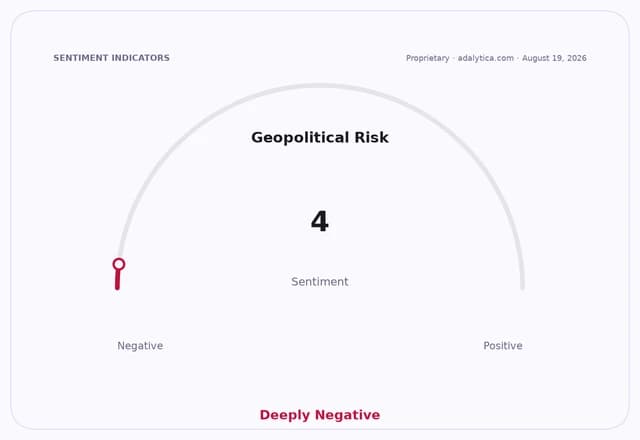
The deal also fits a broader China policy backdrop that remains constructive for infrastructure-heavy industries. Adalytica’s China CCP Policy Direction Sentiment sits at 75, or “Greed,” while U.S.-China relations sentiment is neutral, leaving telecom investors to focus more on domestic policy support and execution risk than on immediate geopolitical easing.
Near term, traders will watch whether the partnership translates into additional contract wins, faster network rollout or clearer capex guidance. Until then, the stock is likely to stay driven by execution headlines and the broader direction of China’s state-owned telecom spending cycle.
| Entity | Gains | Losses |
|---|---|---|
| China Telecom | ▲Faster 5G rollout | ▼Near-term capex pressure |
| Strategic partner | ▲Infrastructure demand | ▼Execution risk |
| Enterprise customers | ▲Better network access | ▼Less pricing flexibility |
| Shareholders | ▲Long-term growth option | ▼Short-term margin drag |