Climate change is moving from an environmental concern to a hard security issue as melting Arctic ice, tightening water supplies and the scramble for critical minerals reshape trade flows, state power and investment risks.
Climate risk reshapes commodities and supply chains
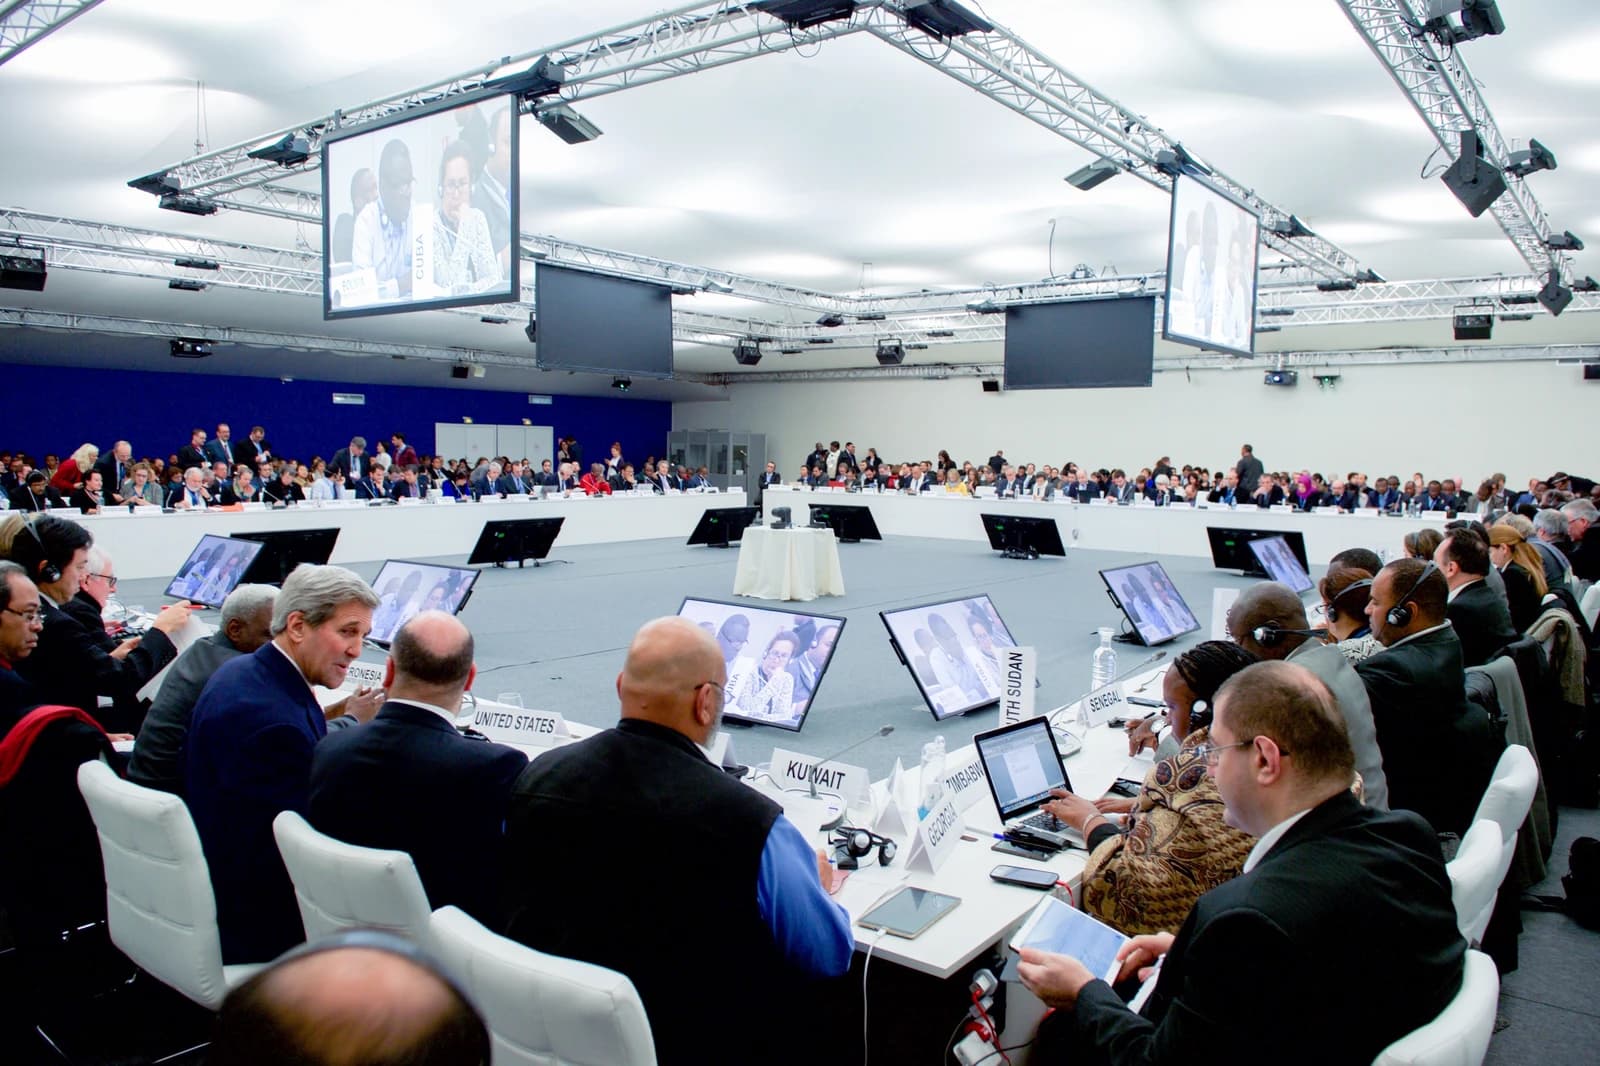
The most important shift for markets is that the climate transition is no longer just about emissions targets; it is about who controls the next generation of energy, materials and food systems. That makes climate policy a macro story with direct consequences for commodity prices, industrial supply chains, sovereign balance sheets and regional stability.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 26, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Emmanouela Doussi, a professor of international institutions and head of UNESCO’s chair on climate diplomacy, said the warming world is already redrawing geopolitical influence. The retreat of Arctic ice is opening new shipping routes, while competition is intensifying for lithium, cobalt and rare earths needed for electric vehicles, batteries and other clean-energy technologies.
Water stress is becoming just as strategic. Doussi said access to water will increasingly drive interstate tensions, especially where rivers cross borders, while climate pressure on agriculture raises the odds of food insecurity and migration flows. The Nile dispute between Egypt and Ethiopia is one example of how climate-linked scarcity can harden into diplomacy and security risk.
DCOILWTICO — macro contextadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
For investors, the implication is that climate exposure is now embedded across a wider set of assets than the obvious renewables trade. Energy exporters face long-term demand and policy pressure as economies shift away from fossil fuels, while countries rich in renewable resources and critical minerals stand to gain leverage. That reordering should support selective investment in grid infrastructure, electrification, transmission and mining, but it also raises execution and permitting risks.
The energy complex already reflects that tension. US crude futures have remained near $94 a barrel in the latest forecast, underlining how geopolitical risk and supply constraints can keep fossil fuels relevant even as the transition advances. At the same time, energy equities have held firm, with the XLE ETF trading around $62.54, above both its 50-day and 200-day moving averages, suggesting investors still want exposure to cash-generating producers as the transition unfolds.
Gold’s recent pullback tells a different part of the story. GLD ended the latest session at about $393.41, below its 50-day average and well under its 200-day average, as the metal cooled from earlier highs. That does not remove gold’s role as a hedge against instability, but it shows that climate-driven geopolitical risk is not yet translating into a one-way flight to safety across commodities.
Agriculture is a more direct pressure point. DBA, the broad agriculture ETF, has stabilized around $28.54, but the underlying theme is more worrying than the price action suggests: water scarcity, erratic weather and supply-chain disruption can tighten food markets quickly, pushing up costs for consumers and forcing policymakers to react.
The broader policy backdrop remains mixed. Doussi argued that existing climate diplomacy relies too heavily on national plans and lacks meaningful penalties for non-compliance, leaving cooperation dependent on political will. That is a problem at a moment when the biggest emitters — including China, the US, India and the EU — are moving at different speeds and often with different priorities.
China has poured capital into clean technology and treats green industry as a strategic sector, even as it continues to invest in fossil fuels. The US, by contrast, has seen growing skepticism toward climate policy and greater emphasis on hydrocarbons. That divergence matters because it influences where capital, manufacturing capacity and mineral supply chains migrate next.
| Entity | Gains | Losses |
|---|---|---|
| Mineral exporters | ▲Higher strategic value | ▼Resource nationalism risk |
| Fossil fuel exporters | ▲Near-term revenue support | ▼Long-term demand erosion |
| Renewable-rich states | ▲More energy leverage | ▼Infrastructure strain |
| Food importers | ▲None | ▼Higher food costs |