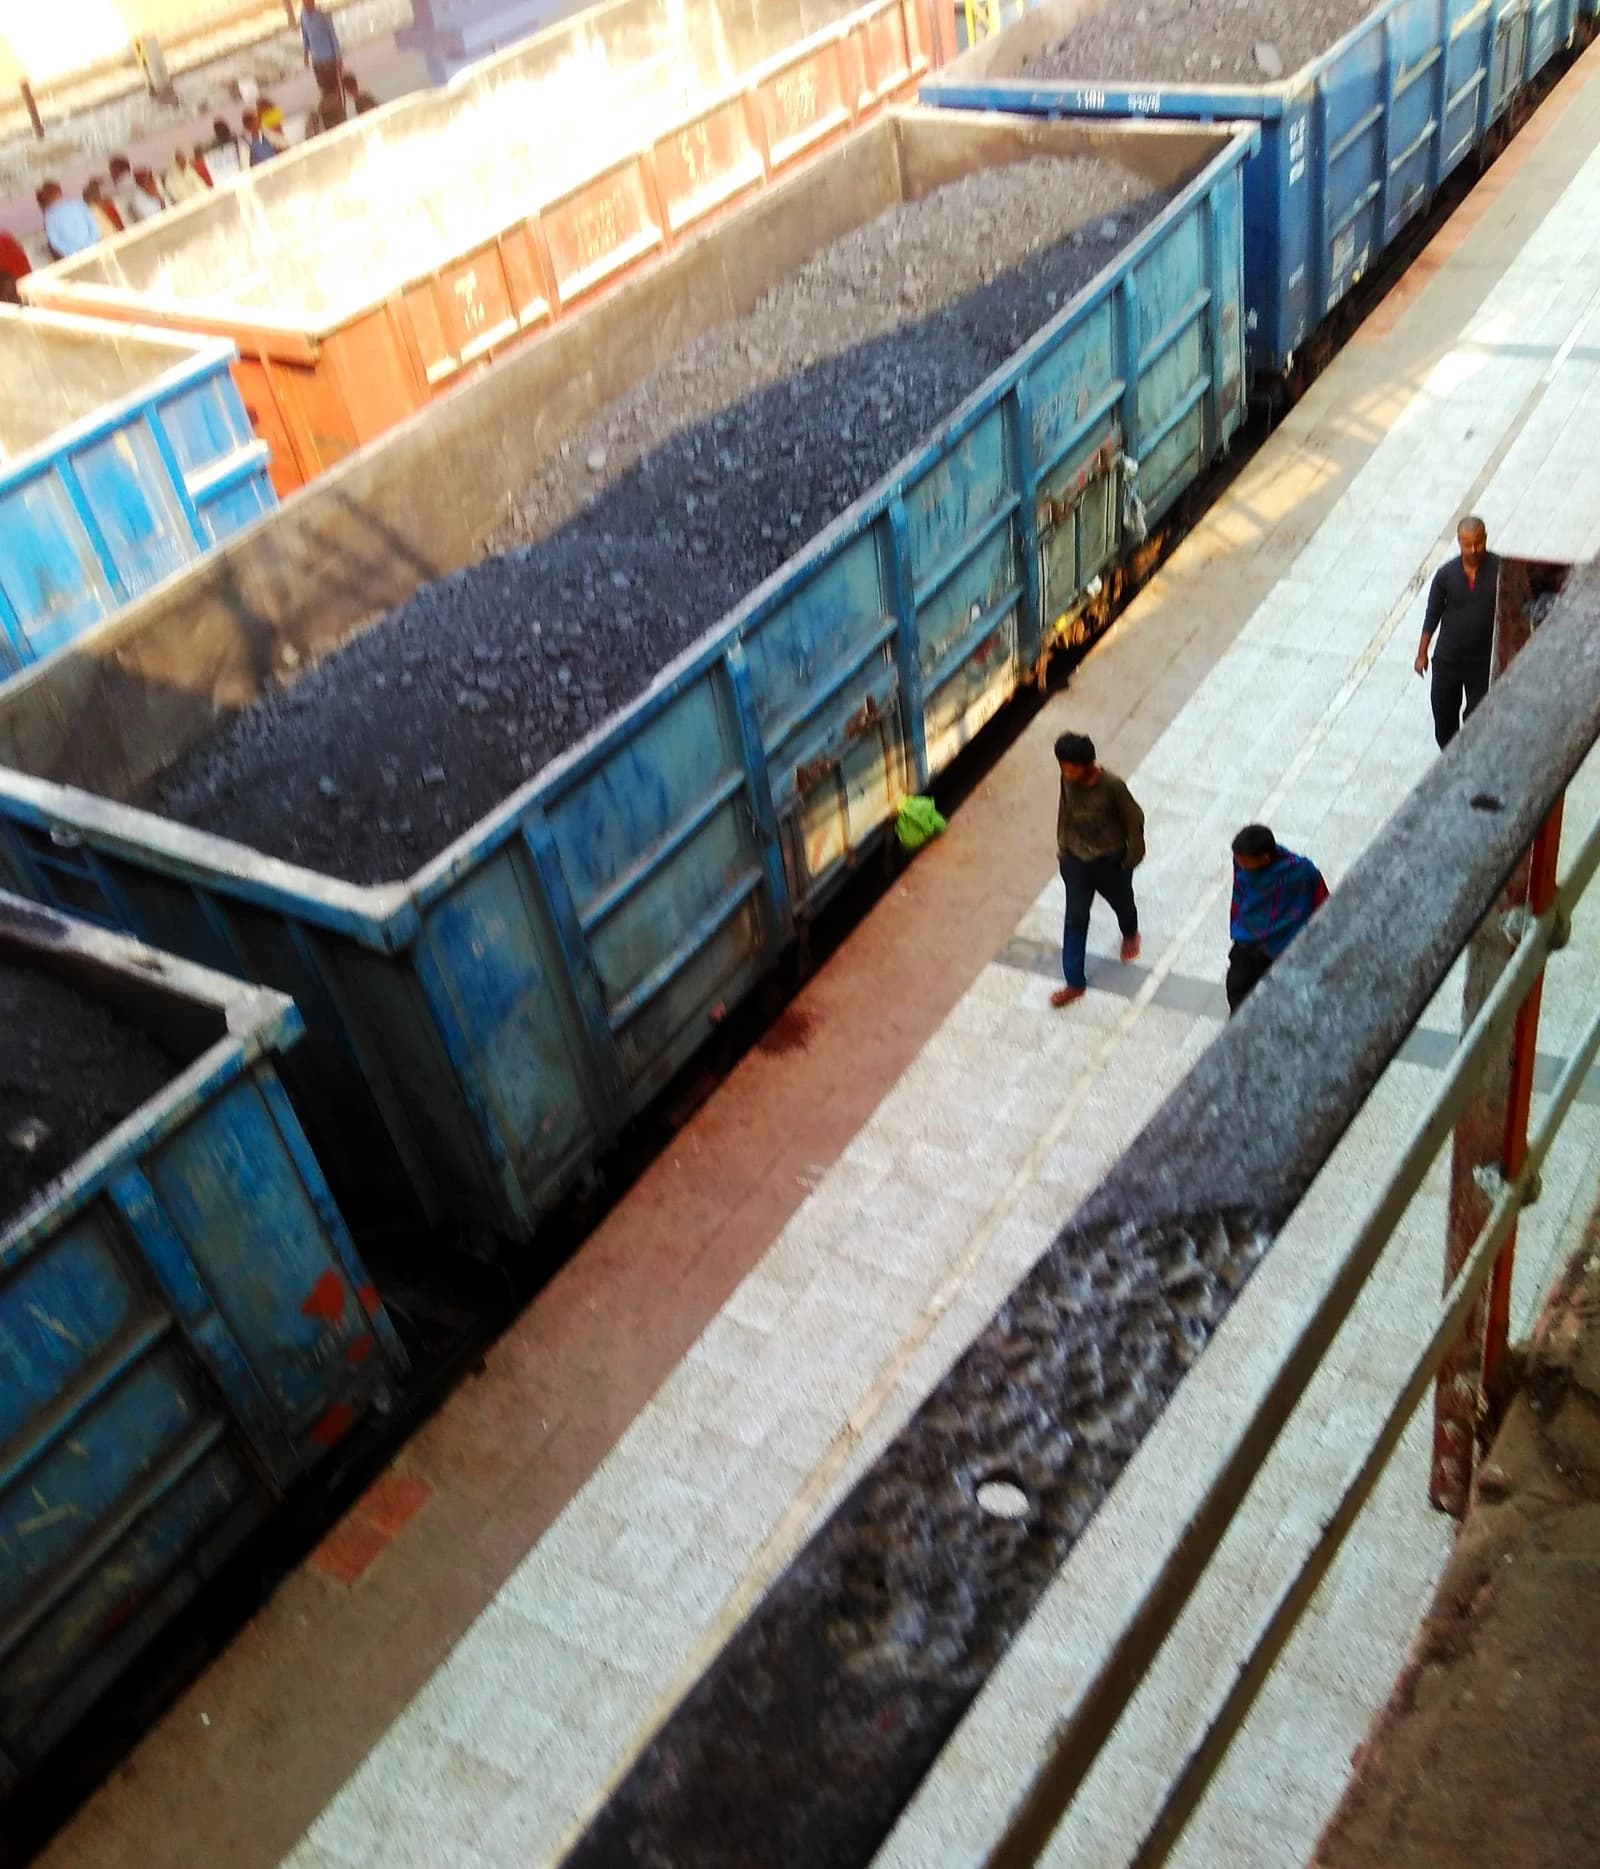
Coal for power generation has climbed about 40% since the start of the year as utilities in Asia and elsewhere switch from scarce liquefied natural gas to a cheaper and more available backup fuel, while supply risks from Indonesia and Australia keep the market tight.
Coal prices rise as LNG supply tightens
The rally matters because it shows how quickly geopolitics and gas-market stress are spilling into other parts of the energy complex. When LNG becomes harder or pricier to secure, coal demand rises almost immediately, lifting fuel costs for power producers and threatening to keep electricity prices elevated in markets that still rely heavily on imported energy.
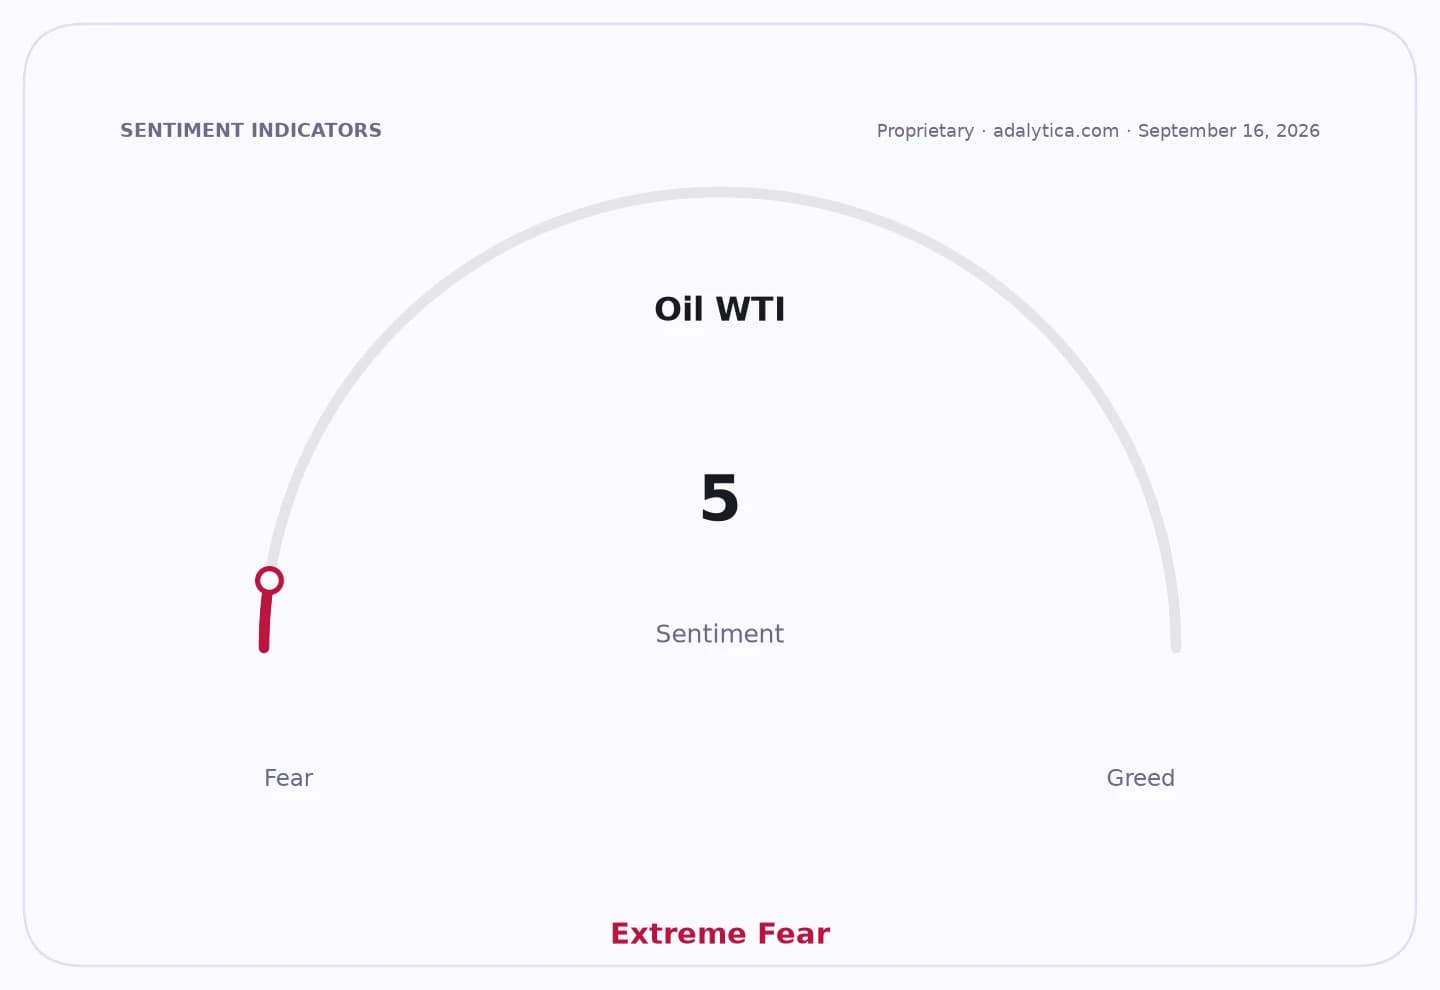
Sentiment IndicatorsⓘProprietary · adalytica.com · October 15, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The shift is being driven by disruption to LNG flows from the Middle East, including uncertainty around shipping routes through the Strait of Hormuz, which has reduced LNG availability for South Asia by an estimated 6 million tonnes. Europe has also seen gas prices stay near 2022 highs despite limited LNG flows from the region, reinforcing the sense that buyers are competing for a smaller pool of flexible supply.
That has sent some demand back to coal even as the market faces its own constraints. Indonesian exports have stagnated under tighter government controls and domestic supply obligations, while Australian miners face export curbs and other restrictions, limiting how much additional coal can reach the market just as buyers want more of it.
For investors, the move is a reminder that coal is still a relevant hedge when gas markets tighten. Producers exposed to seaborne coal pricing can benefit from the firmer backdrop, while utilities, industrial users and countries dependent on imported fuel face higher input costs and more volatility in power-generation margins.
Peabody Energy shares have come under pressure recently, with the stock closing at $24.02 on Oct. 15 after falling below both its 50-day and 200-day moving averages, and its relative strength index at 37.4 suggesting the recent pullback has not yet fully reversed. Even so, a sustained coal-price rally could support earnings expectations for exporters if export restrictions do not loosen and LNG remains tight.
The next catalyst is whether Middle East shipping risk eases and whether Indonesian or Australian supply policies change enough to bring more coal to market. Until then, the fuel switch away from LNG is likely to keep coal prices supported and preserve volatility across the global energy trade.
| Entity | Gains | Losses |
|---|---|---|
| Coal exporters | ▲Higher realized prices | ▼Export limits and policy risk |
| Power generators | ▲Fuel optionality | ▼Higher input costs |
| LNG sellers | ▲Some demand intact | ▼Lost volumes to coal |
| Utilities/importers | ▲Short-term supply backup | ▼Margin pressure and volatility |