Costco Wholesale is heading into its September sales report with Wall Street focused less on short-term stock swings than on whether its membership engine can keep delivering the predictable growth that supports its premium valuation.
Costco September Sales in Focus Ahead of Report
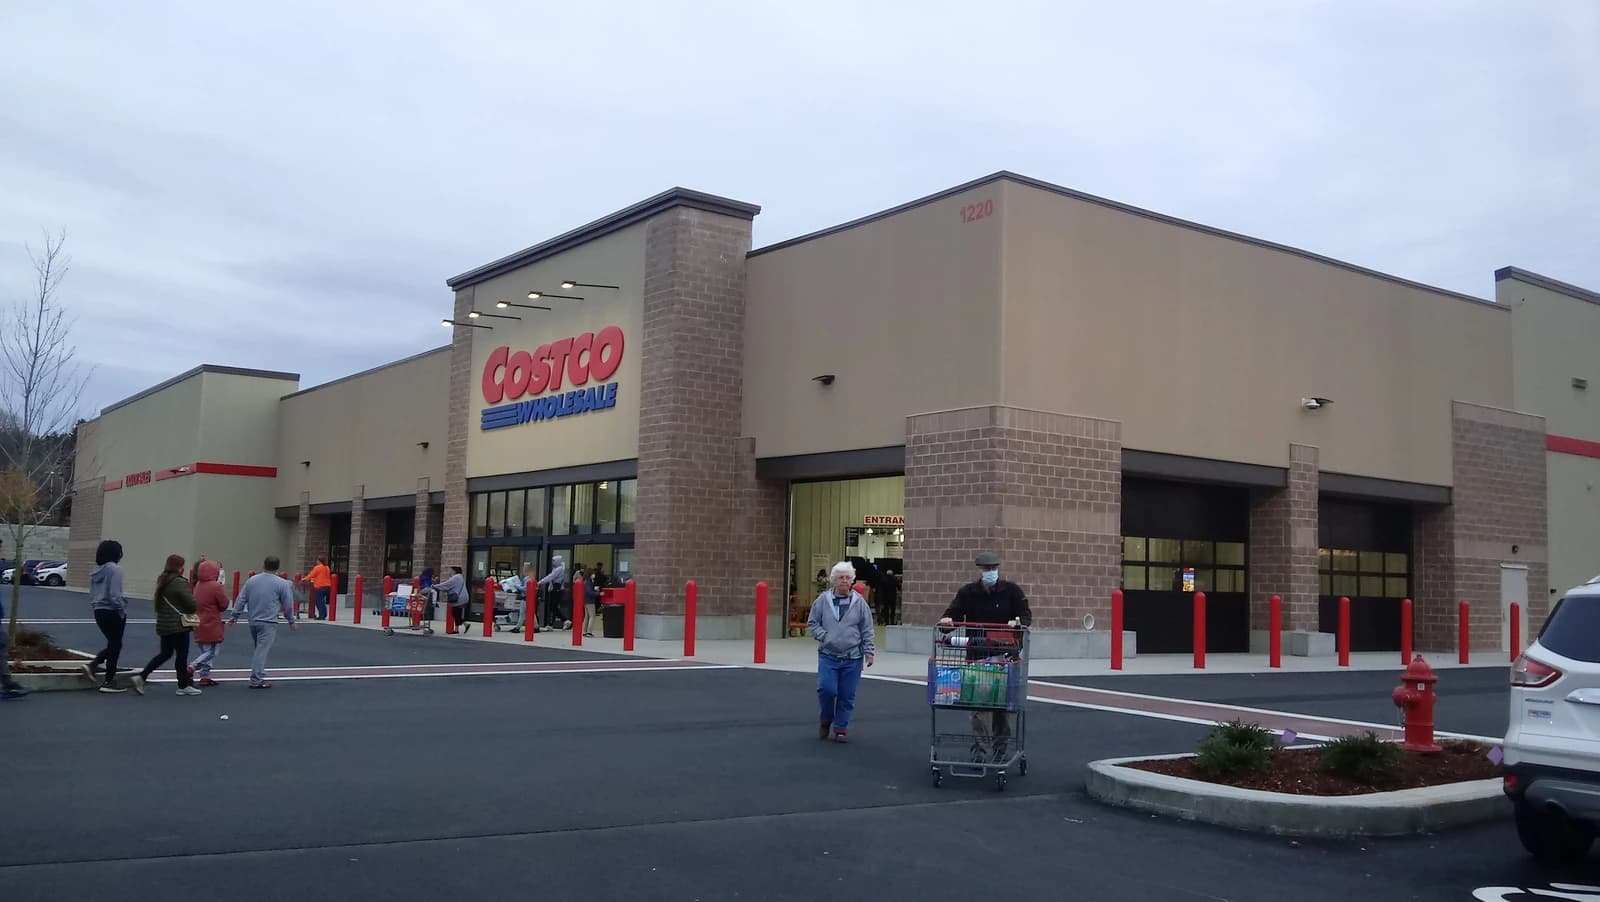
Telsey Advisory Group reiterated its positive view on the warehouse club ahead of the update, underscoring a familiar bull case: Costco’s subscription model, high renewal rates and growing executive memberships continue to make earnings more resilient than the average retailer’s. That matters because Costco does not need explosive same-store sales to justify investor confidence; it needs sustained traffic, disciplined pricing and steady fee income.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 8, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The company’s latest annual filing showed membership fee revenue rose 11% in fiscal 2026 to $5.907 billion, helped by new sign-ups, higher fees and upgrades to Executive memberships. Renewal rates remained exceptionally high at 92.3% in the U.S. and Canada and 89.8% worldwide, a level that keeps recurring revenue growing even when consumer spending turns uneven.
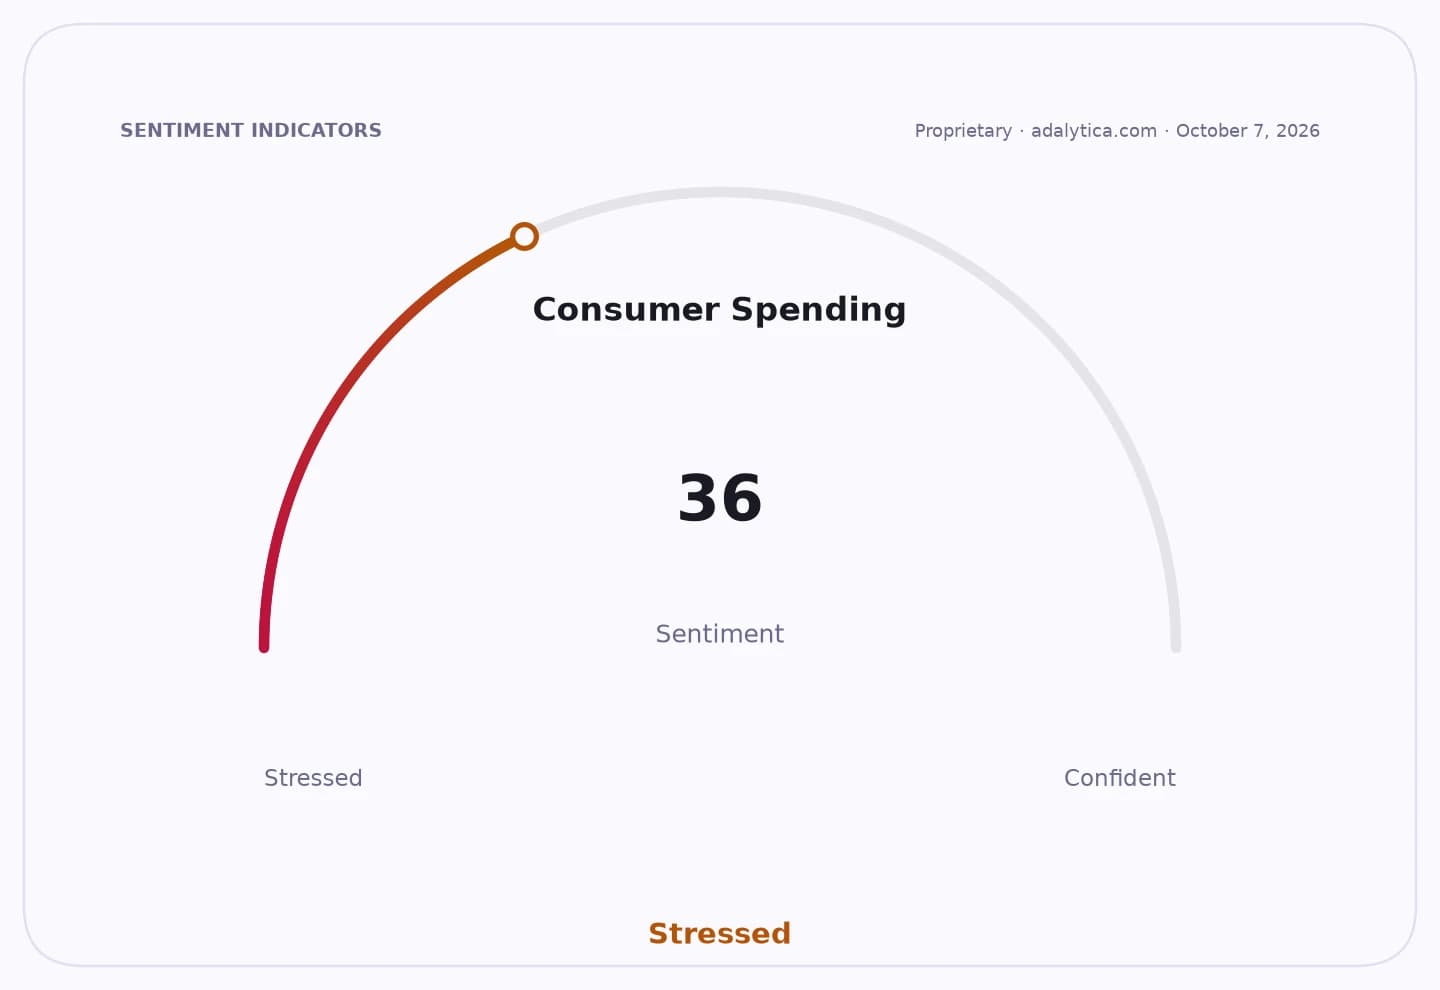
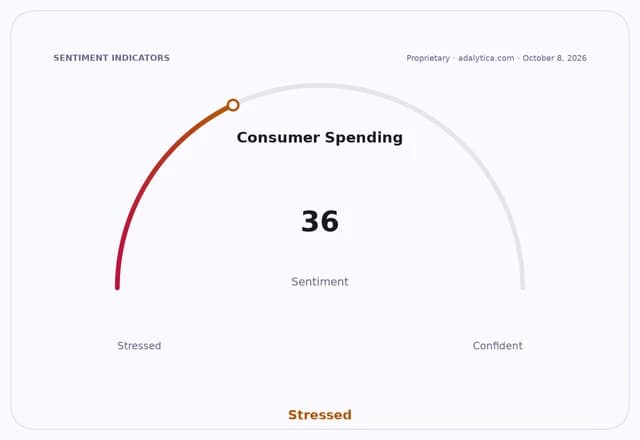
That durability is especially important now. Adalytica’s Consumer Spending Sentiment snapshot sits at 36, labeled neutral, after a sharp 39-point drop over the past month. In that kind of backdrop, investors tend to favor retailers that can win share without leaning on heavy discounting or discretionary demand. Costco has long fit that profile: it trades on value, but its scale and loyal customer base allow it to hold up when shoppers become more selective.
Consumer Spending — 30-day sentimentadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
The stock has already reflected that resilience. Costco shares closed at $942.25 on Oct. 7, above the 50-day moving average of $932.09 but still below the 200-day moving average of $960.59, suggesting the market has been willing to give the name credit for fundamentals even as the broader trend remains uneven. The 14-day RSI at 75.9 points to strong recent momentum, while the MACD has turned positive, signaling that buyers have regained some control after a volatile summer.
For investors, the September sales figure is less about a single month and more about whether Costco can extend a pattern that supports both earnings quality and multiple expansion. A solid update would reinforce the case that the business is still gaining members, preserving traffic and defending pricing power even as consumer confidence softens. A miss, by contrast, would raise questions about how much room remains for further share gains in an increasingly crowded value retail space.
The next catalyst is straightforward: monthly sales will show whether Costco is still converting cautious consumers into steady members, or whether the recent pullback in spending appetite is beginning to slow the warehouse club’s momentum.
| Entity | Gains | Losses |
|---|---|---|
| Costco | ▲Membership revenue growth | ▼Slower sales momentum |
| Long-term shareholders | ▲Defensive earnings profile | ▼Multiple compression risk |
| Value-focused consumers | ▲Low-price warehouse model | ▼Fewer discretionary bargains |
| Rival retailers | ▲None | ▼Share and traffic pressure |