Costco’s rise under Ron Vachris is a reminder that in an era of stubborn inflation, supply-chain complexity and relentless competition, the market rewards execution over pedigree.
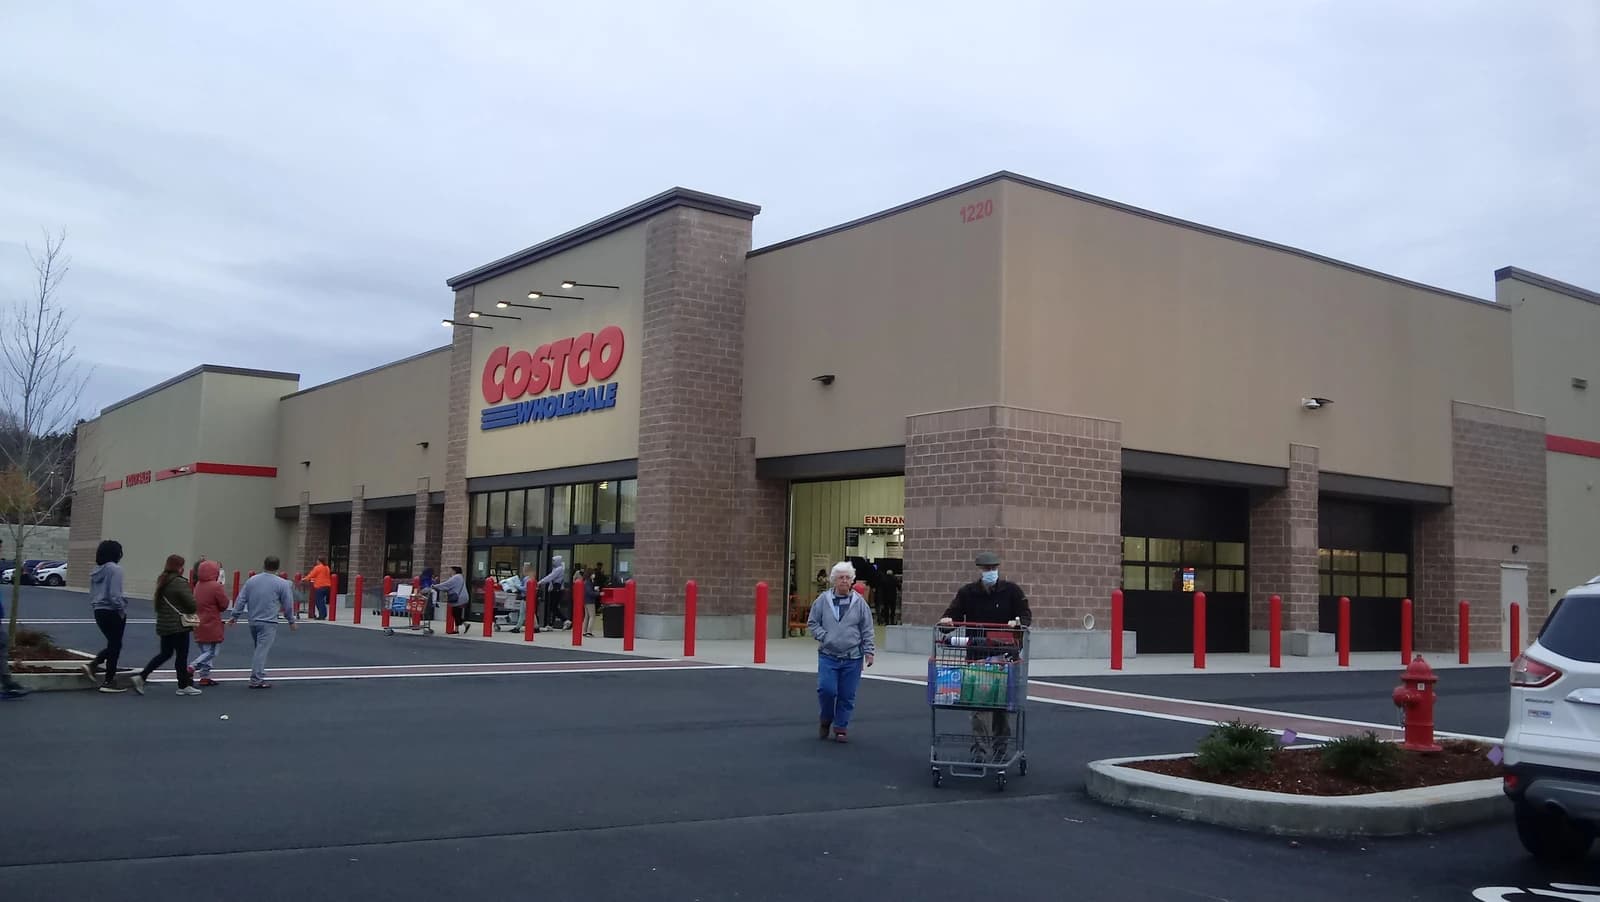
Costco Shares Near $1,000 Under Ron Vachris
Vachris, who started at Costco as a forklift driver before becoming chief executive, embodies the warehouse club’s most durable advantage: a culture built from the shop floor up, not designed in a boardroom. That matters because Costco’s business model depends on precision — moving inventory efficiently, keeping costs low, and preserving member loyalty even as consumers become more selective and price-sensitive.
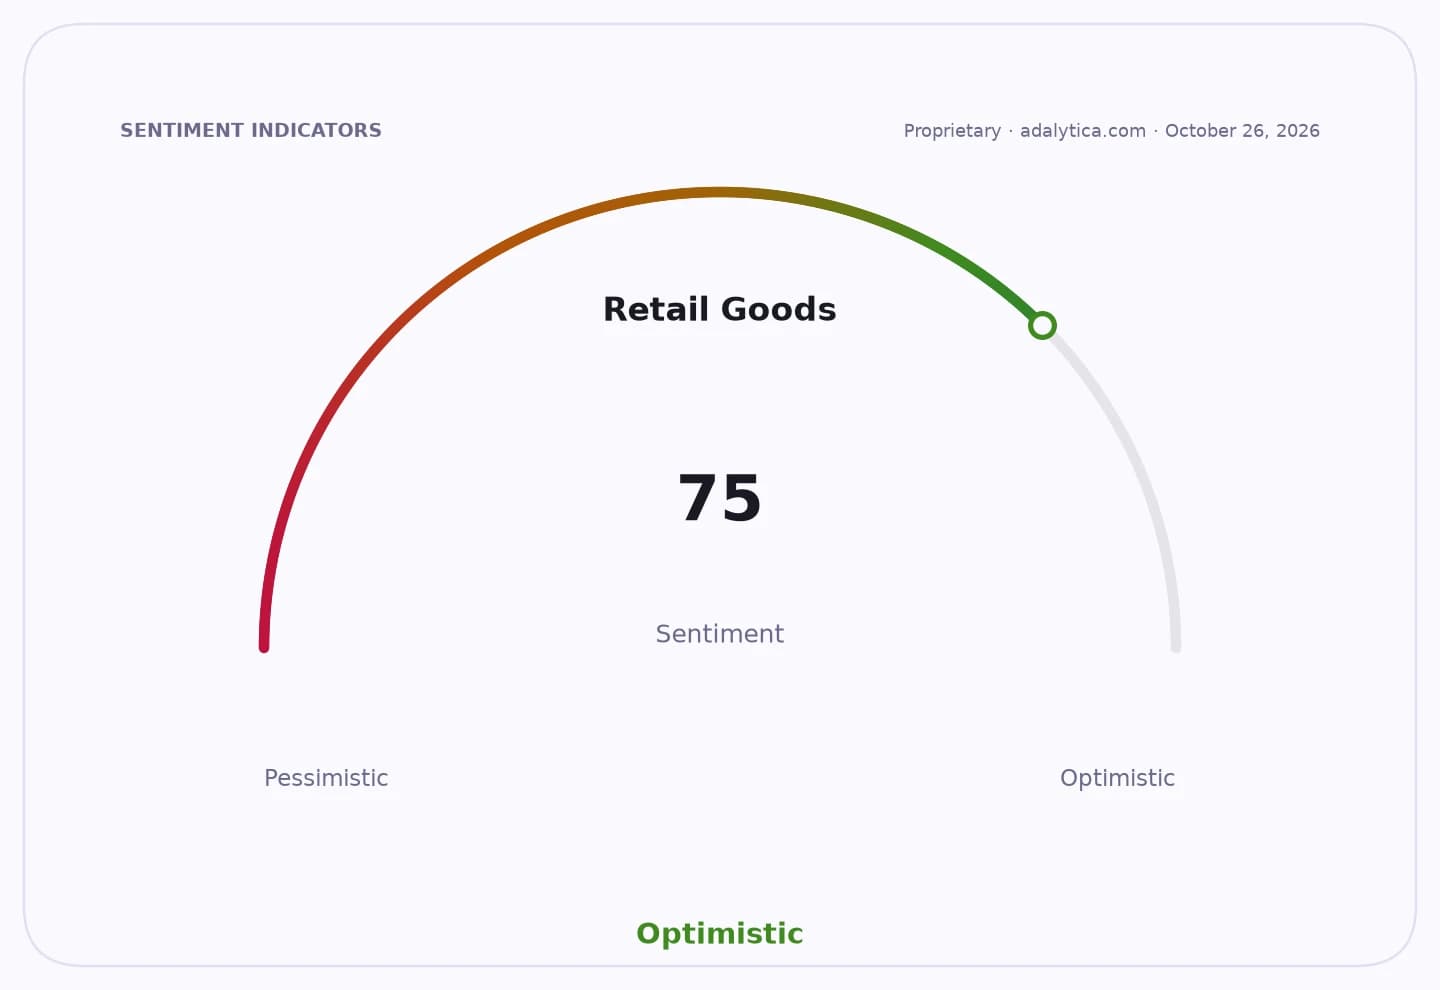
Sentiment Indicators
For investors, the message is bigger than one executive biography. The companies that win the next phase of retail will be the ones that can protect traffic, defend margins and keep pricing power without alienating customers. Costco has done that better than almost anyone in consumer staples or retail, and Vachris’ operational pedigree reinforces why. A leader who has lived the cadence of the warehouse floor is more likely to protect the company’s low-cost structure than one focused on optics or hierarchy.
The stock has already reflected that confidence. Costco shares have been trading near the $1,000 level, far above both the 50-day and 200-day moving averages, and recent technical readings show the name has been extended even after some volatility. That says investors are still willing to pay up for quality, but it also highlights how much of Costco’s appeal rests on the expectation that management will keep executing through cycles, not on short-term excitement. Adalytica.com’s Walmart earnings sentiment snapshot has also flashed “Extreme Greed,” underscoring how strongly the market is leaning into big-box winners as consumers trade down and hunt for value.
The broader investment thesis is that Costco remains one of the cleanest ways to own the consumer trade-down theme without betting on a weak economy outright. If households stay pressured, the warehouse club model should keep taking share. If the economy stabilizes, Costco still benefits from membership stickiness, bulk buying and disciplined capital allocation. That makes the name a rare defensive compounder with offensive upside.
The next catalyst is not a flashy strategy pivot. It is continued proof that Costco can keep growing sales, renew memberships and expand internationally while preserving the culture that made it great. In this market, that is exactly the kind of leadership investors should want to own.
| Entity | Gains | Losses |
|---|---|---|
| Costco | ▲Operational continuity | ▼Nothing immediate |
| Ron Vachris | ▲Credibility as an operator | ▼Title-based leadership norms |
| Investors in COST | ▲Durable compounding story | ▼Missed if they chase cheaper retail names |
| Traditional retailers | ▲Harder comparison on efficiency | ▼Share to warehouse clubs |