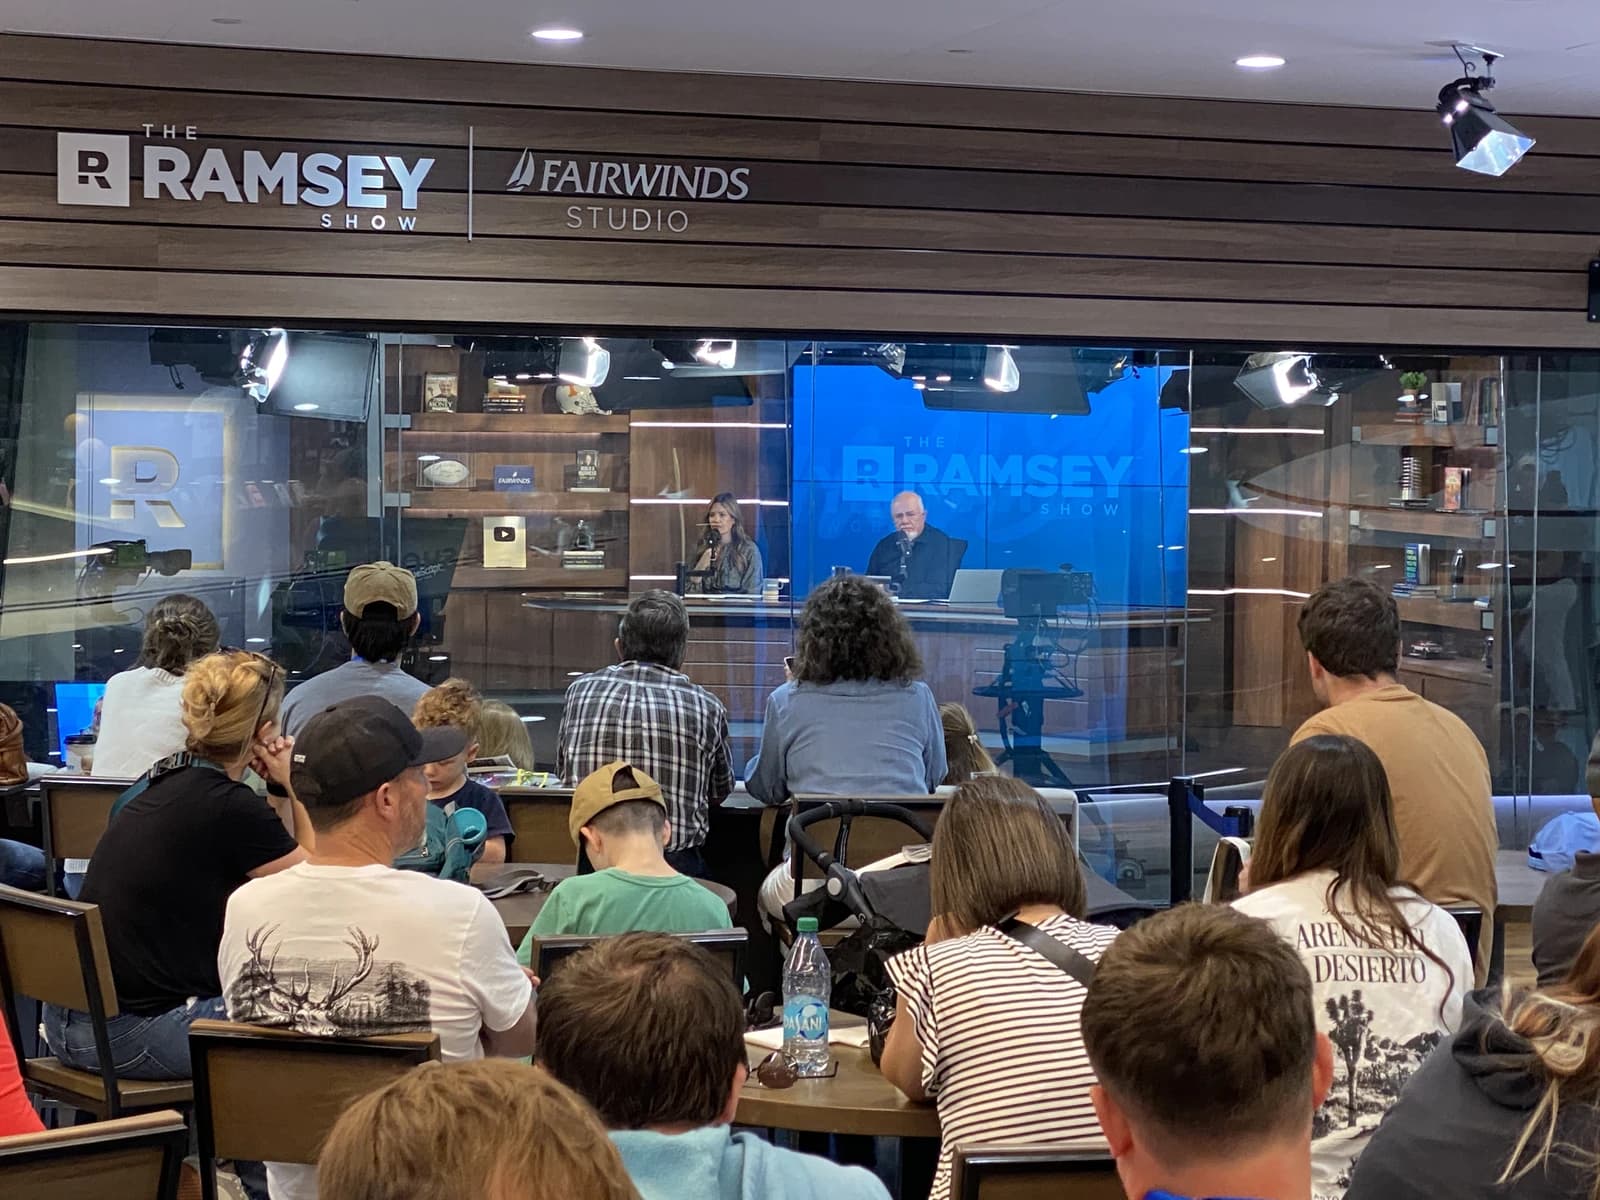
A Philadelphia sales worker who says he suddenly has $50,000 in the bank after a job switch is being told by Dave Ramsey to use most of it to wipe out roughly $70,000 of vehicle debt before thinking about investing.
Dave Ramsey Urges $40,000 Debt Paydown First
The advice lands in a market where consumer borrowing costs remain elevated and lenders are getting more cautious. The 10-year Treasury yield is near 5.23%, high-yield credit spreads are around 3.18%, and unemployment is forecast at 4.11%, a backdrop that makes balance-sheet cleanup more valuable than chasing sub-1% cash returns.
Sentiment Indicators
Shane, who said he saved $40,000 in six months and now sits on $50,000 in a savings account earning less than 1%, called The Ramsey Show looking for a place to invest. Ramsey instead pushed him to attack the smaller of the couple’s two auto loans, saying he would “stop your 401(k) temporarily” and use $40,000 of the savings to cut the debt first.
For investors, the story is a reminder that the U.S. consumer is still juggling high-rate debt even after wage gains and job changes. That matters for auto lenders, banks and credit investors because car loans are among the most rate-sensitive forms of household borrowing, and bad debt at listed banks has surged nearly 27% over the first nine months of the year in a sign of growing strain.
Ramsey’s playbook also reflects a broader shift in personal finance priorities as savings finally build but remain trapped in low-yield deposits. Co-host Rachel Cruze pointed Shane to a high-yield savings account paying 3% to 4% for an emergency fund, while Ramsey said retirement contributions can wait until the debt is gone and the family has three to six months of expenses set aside.
The investment implications are straightforward: deleveraging first, then retirement and index-fund investing later. That sequence reduces monthly cash outflow, lowers default risk and gives households more flexibility if the labor market softens or credit conditions tighten further.
For lenders such as Ally Financial, which specializes in auto finance, the dynamic cuts both ways. Paying down car loans improves household resilience, but it also caps growth in new loan balances at a time when banks are already dealing with rising non-performing assets and more aggressive debt recovery efforts.
The next catalyst is whether higher borrowing costs and tighter credit standards keep pushing consumers to prioritize debt repayment over new spending. If that trend broadens, it would be a headwind for auto finance growth but a support for credit quality across the banking sector.
| Entity | Gains | Losses |
|---|---|---|
| Households paying down debt | ▲Lower monthly obligations | ▼Less short-term investing |
| Auto lenders and banks | ▲Better repayment odds | ▼Slower loan growth |
| Emergency fund savers | ▲Higher-yield cash options | ▼Lower immediate liquidity |
| S&P 500/index funds | ▲Later long-term inflows | ▼Near-term contributions delayed |