The euro’s near-term recovery has been pushed back as Rabobank cut its one-month EUR/USD forecast to 1.14, arguing that markets have moved too far toward expecting another Federal Reserve hike and are not yet ready to rebuild long positions in the single currency.
EUR/USD Forecast Cut to 1.14 by Rabobank
That matters because the exchange rate is once again being driven less by Europe’s growth picture than by U.S. policy expectations and global risk appetite. EUR/USD was trading around 1.1377 on Thursday, after a 0.58% drop on Wednesday, leaving the pair close to June’s yearly low of 1.1325 and still vulnerable if the dollar retains its late-year bid.
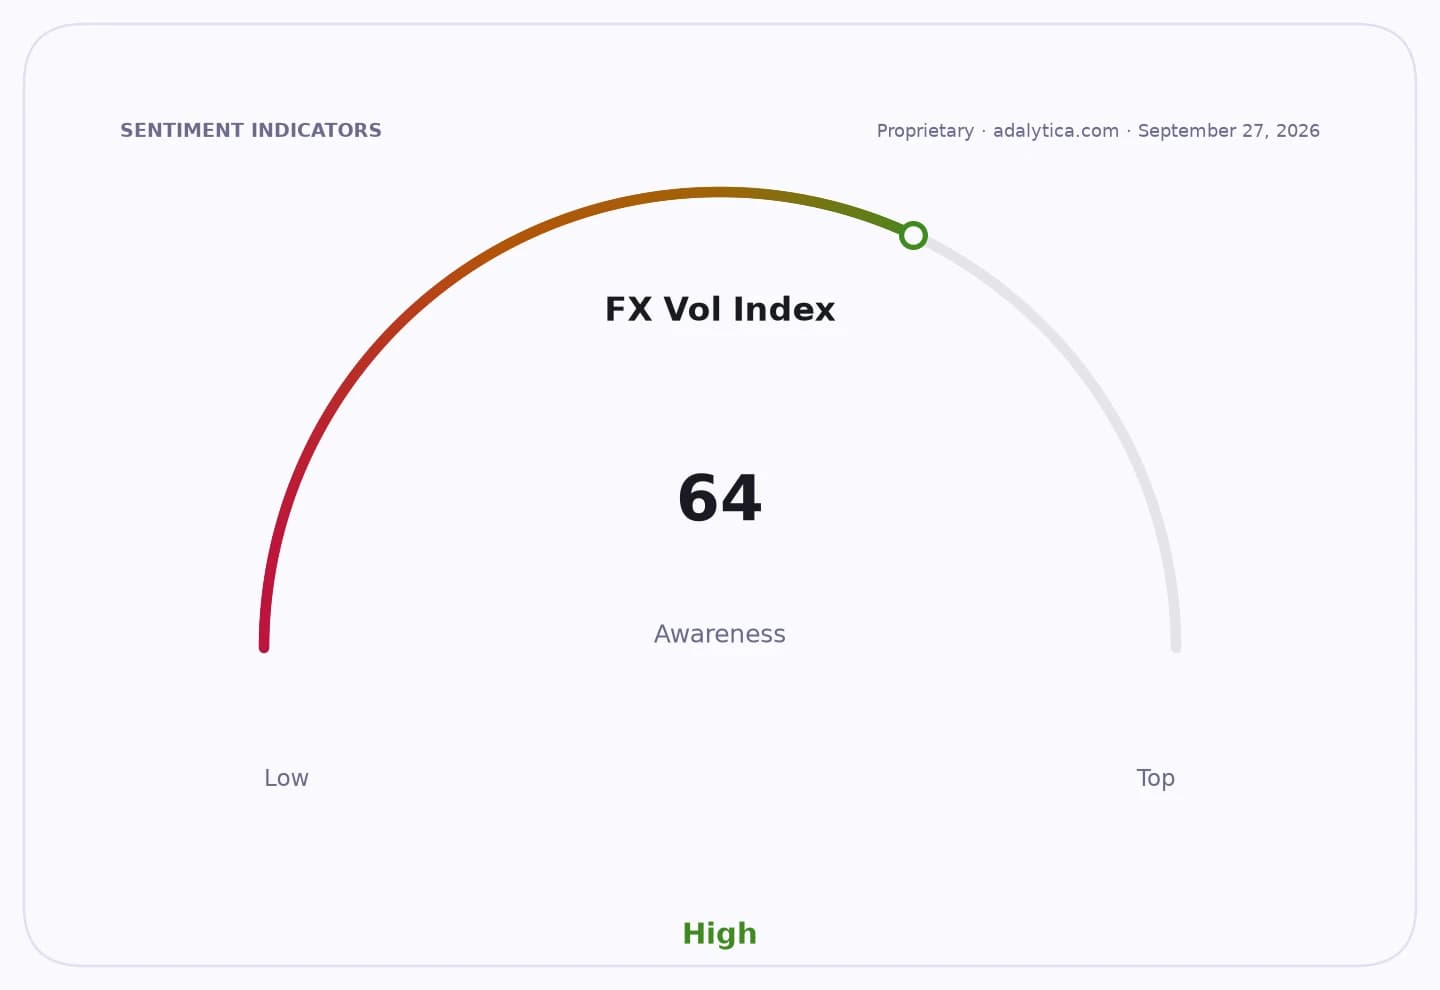
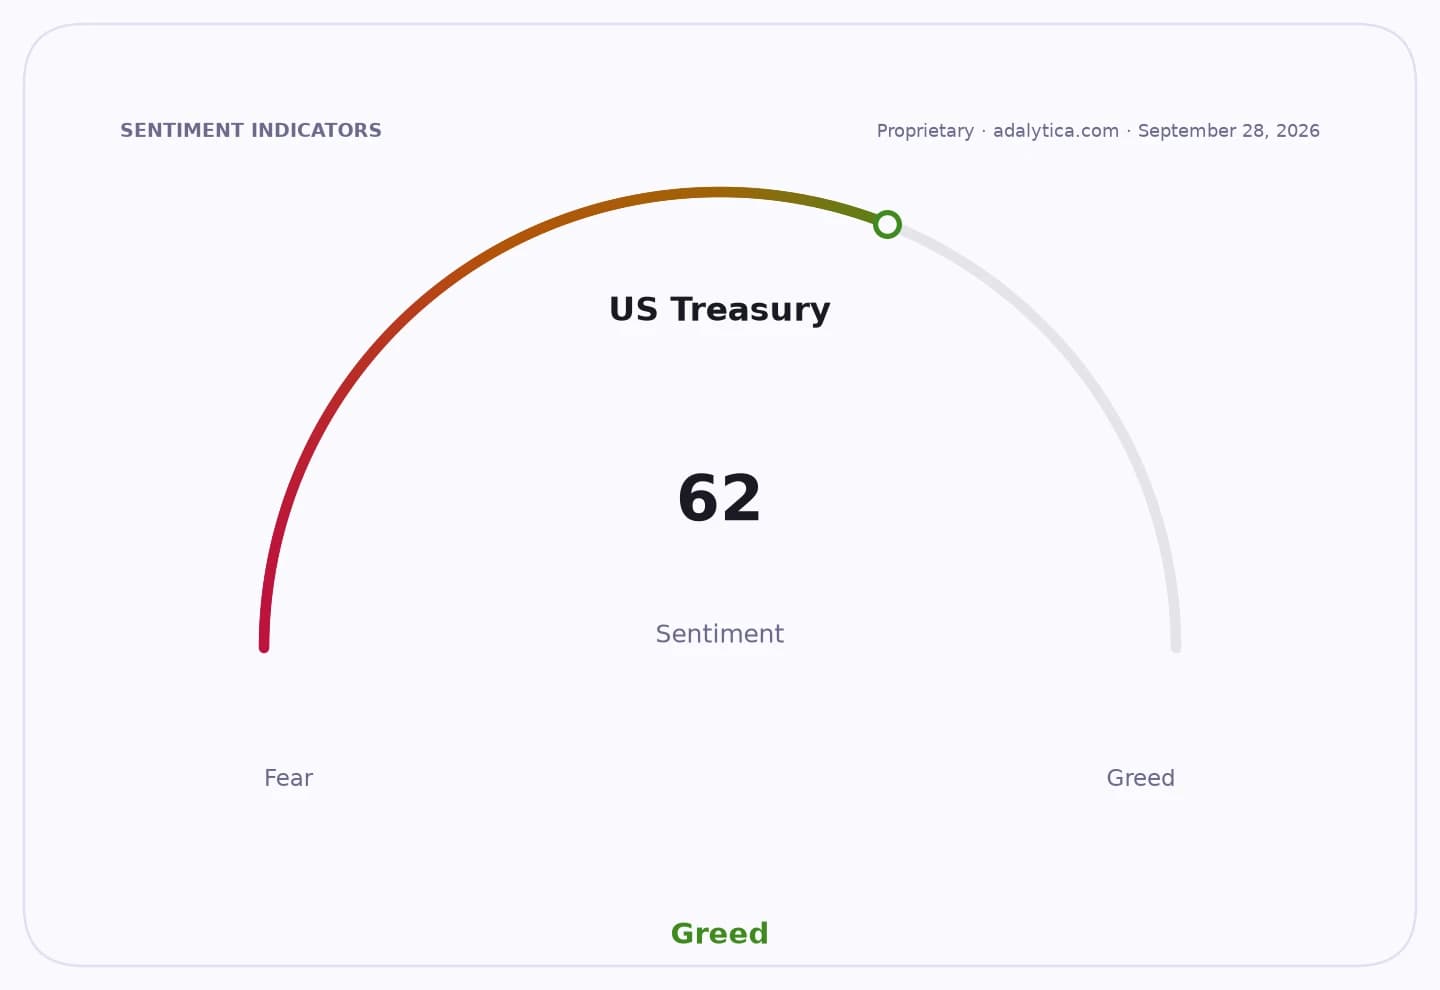
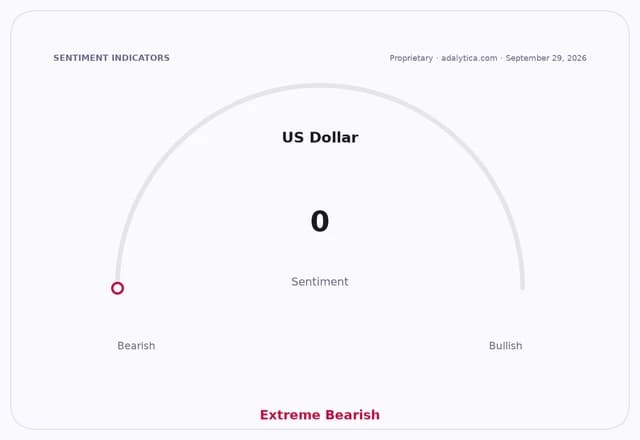
Sentiment IndicatorsⓘProprietary · adalytica.com · September 29, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Rabobank kept its three-month target at 1.16, but the path to that level now depends on a clear retreat in Fed tightening bets. The bank said markets are pricing roughly a 70% chance of an October rate increase after September’s hike, a backdrop that has supported the dollar even as eurozone activity improves. The euro area composite PMI rose to 53.1 in September, a reading consistent with expansion, but stronger U.S. survey data has overshadowed the European improvement.
The bank’s argument is essentially a timing call on policy divergence. If investors have priced in too much Fed tightening, the dollar’s recent strength could unwind and allow EUR/USD to recover about 2% toward 1.16 over three months. But Rabobank also warned that near-term gains may be capped while the Iran war keeps energy risk elevated, reducing the willingness of investors to add euro exposure.
That geopolitical overlay matters for Europe more than for the United States. Any sustained rise in energy risk tends to hit the euro through trade balances, inflation expectations and growth confidence, while reinforcing the dollar’s appeal as a defensive asset. The result is a market that can tolerate better European data, but not enough to offset higher U.S. rate expectations and energy-linked caution.
For investors, the message is that the euro is not trading on the weakest domestic data point, but on the broader balance between Fed policy, U.S. economic resilience and global risk sentiment. Rabobank’s revised one-month forecast is only slightly above spot, which suggests the market may remain rangebound unless the Fed repricing reverses.
The bank’s longer-term view is still constructive, though not unqualified. It expects EUR/USD to reach 1.16 on a three-month horizon, but said next year’s French presidential election could also limit upside, and it plans to review its forecasts in the coming weeks. That leaves traders watching the same two drivers that have dominated the pair for months: whether the Fed delivers as much tightening as priced, and whether Europe’s energy and political risks allow the euro to benefit when it does not.
| Entity | Gains | Losses |
|---|---|---|
| U.S. dollar | ▲Higher-rate support | ▼Risk of reversal if Fed bets fade |
| Euro | ▲Potential 3-month rebound | ▼Near-term upside capped by energy risk |
| Dollar bulls | ▲Stronger carry and defensive demand | ▼Vulnerable to policy repricing |
| Euro longs | ▲Recovery toward 1.16 | ▼Delay in rebuilding positions |