Britain and the wider European gas market are heading into winter with inventories unusually thin, raising the risk of price spikes and supply stress if cold weather arrives early or lasts longer than normal.
Europe Gas Storage at Lowest Level for Winter
European gas storage is 72% full, the lowest level ever recorded for this time of year, according to The Economist, far below the roughly 90% average seen in 2022-2025. In the UK, storage was below 40% on Sept. 30, while German and Dutch facilities were only about 60% full, underscoring how little buffer the region has after the latest restocking season.
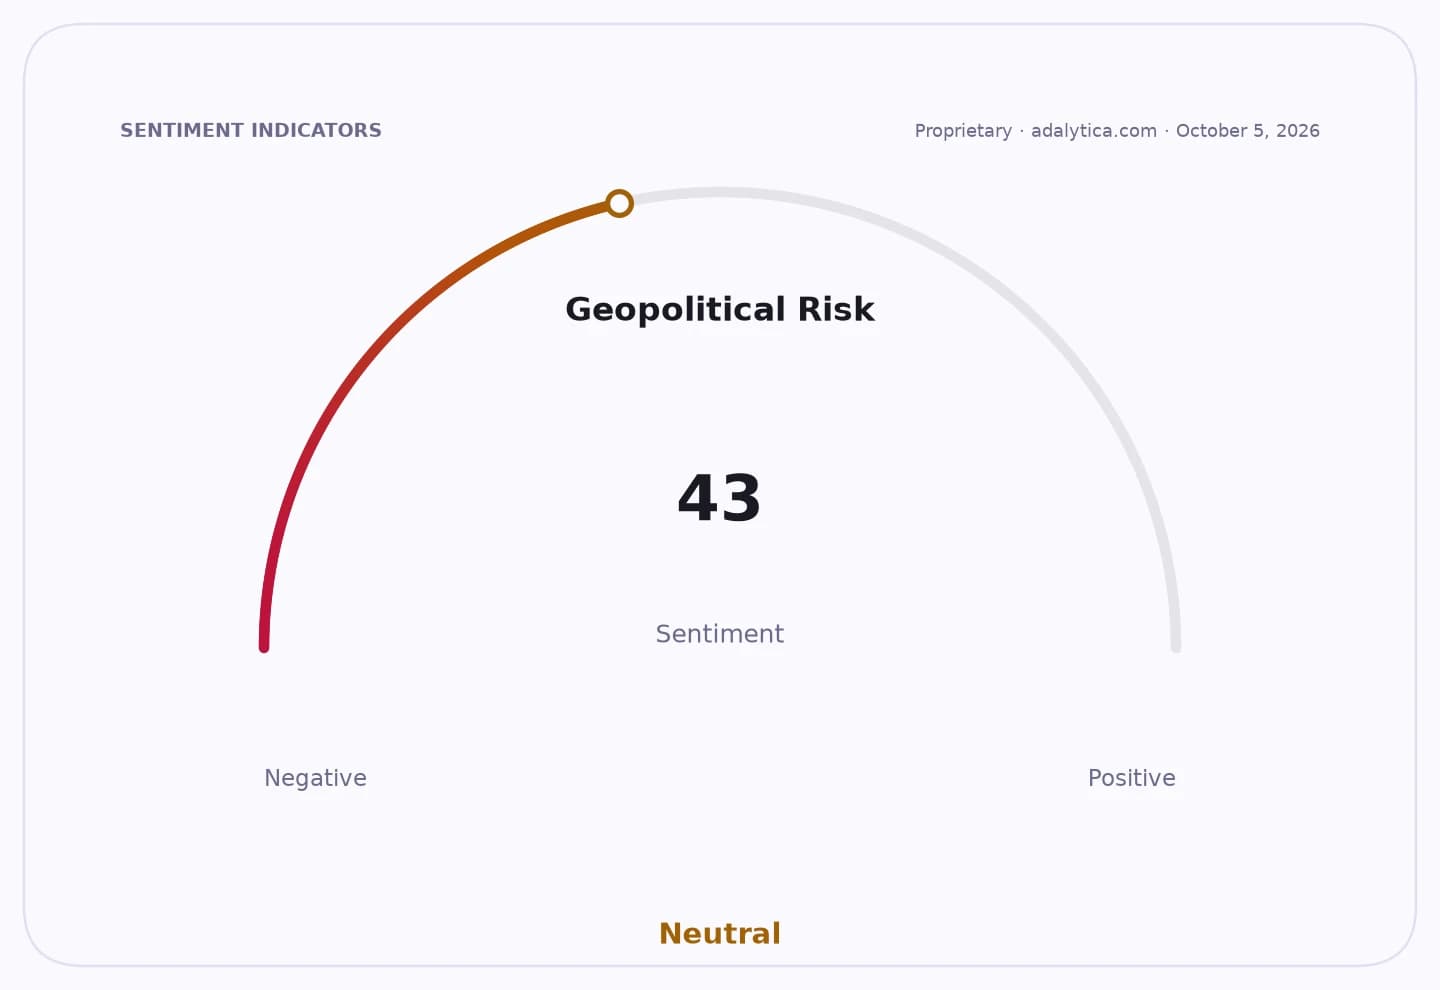
Sentiment IndicatorsⓘProprietary · adalytica.com · October 5, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The shortage matters because gas still sets the tone for power prices, industrial costs and household bills across Europe. Lower inventories mean the market has less room to absorb a supply shock from a cold snap, a pipeline outage or renewed LNG disruption, and that can quickly feed into wholesale prices and inflation expectations.
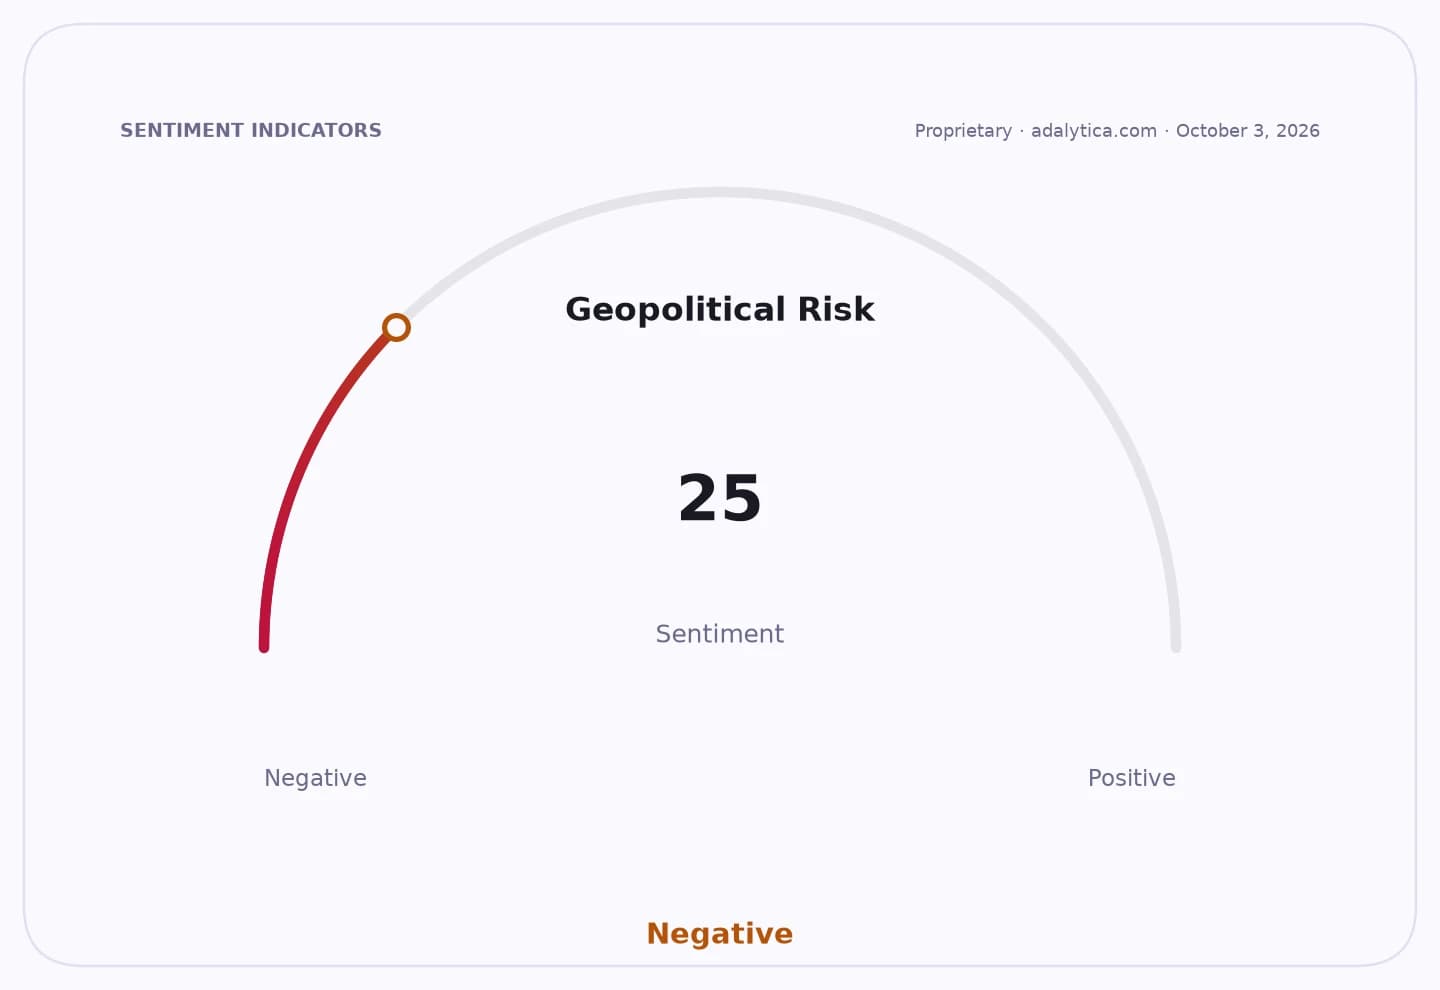
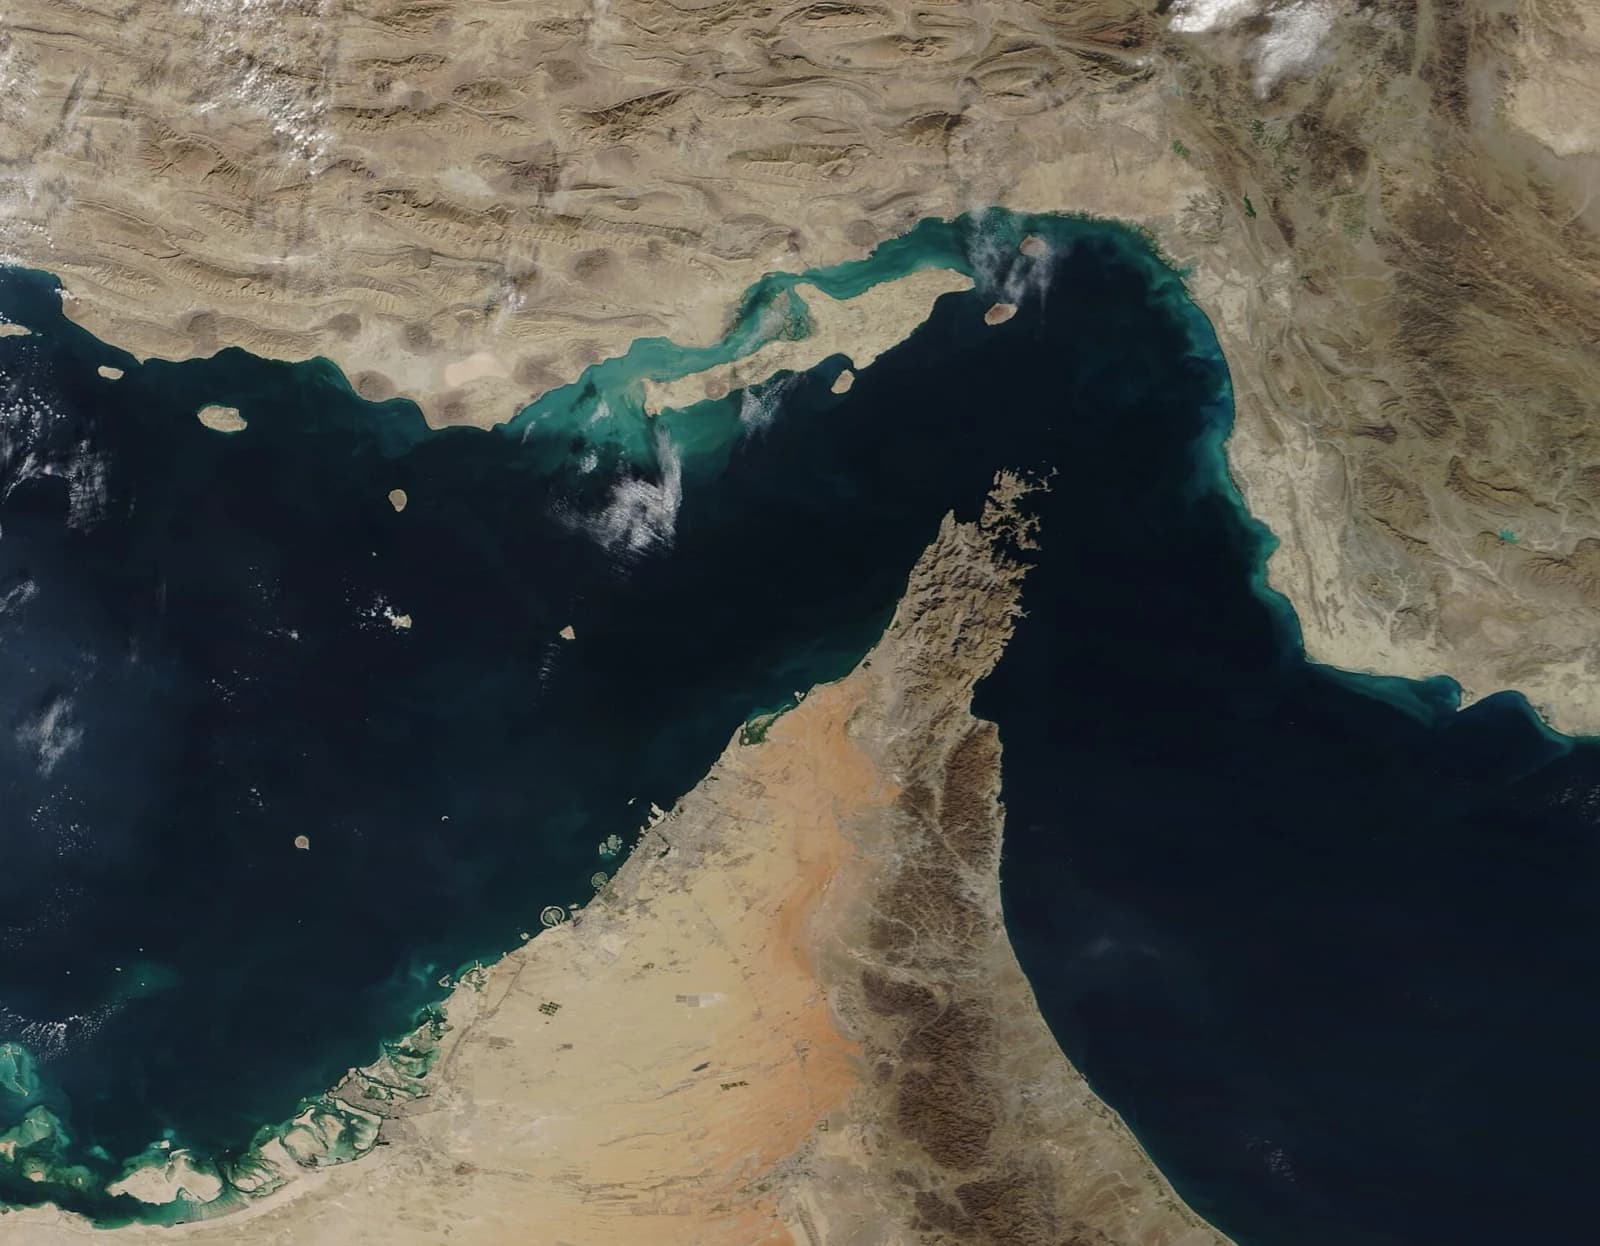
The situation is particularly sensitive after Europe spent the past four years trying to replace Russian energy flows with LNG imports and other suppliers. The report said Qatar had been forced to declare force majeure on LNG shipments after the closure of the Strait of Hormuz, a reminder that Europe’s replacement strategy remains exposed to geopolitical and shipping risks far beyond the continent.
For investors, the setup keeps natural gas futures and energy equities in focus. Front-month U.S. natural gas futures, tracked by NG=F, rose to $3.06, while the Energy Select Sector SPDR Fund, XLE, traded at $63.54, reflecting a firmer backdrop for energy markets even as gas-specific technical readings remain mixed.
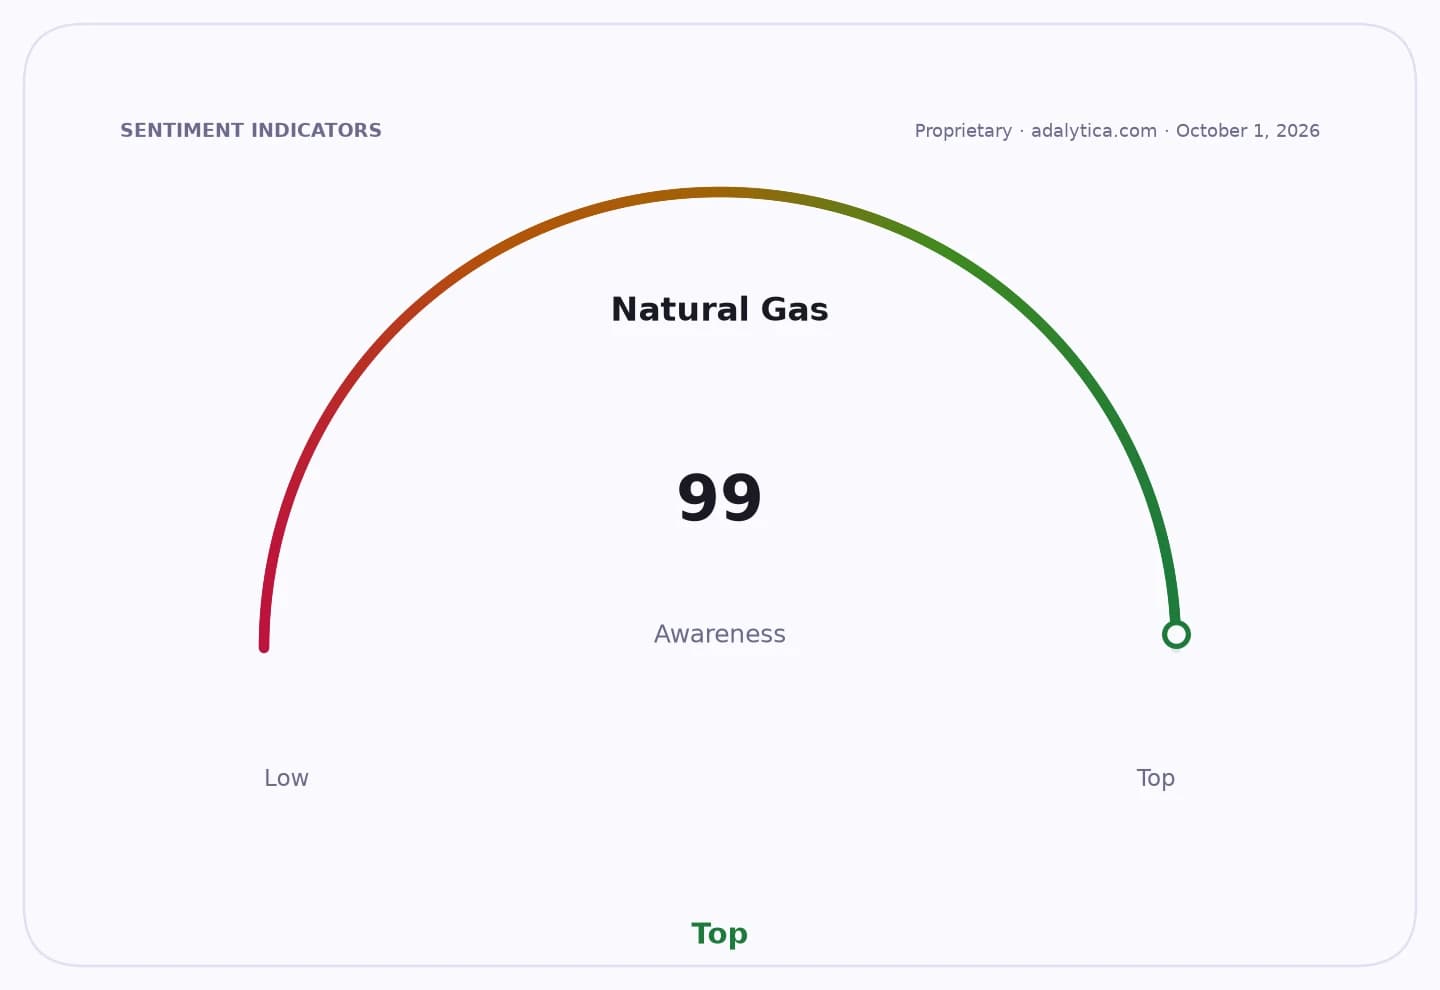
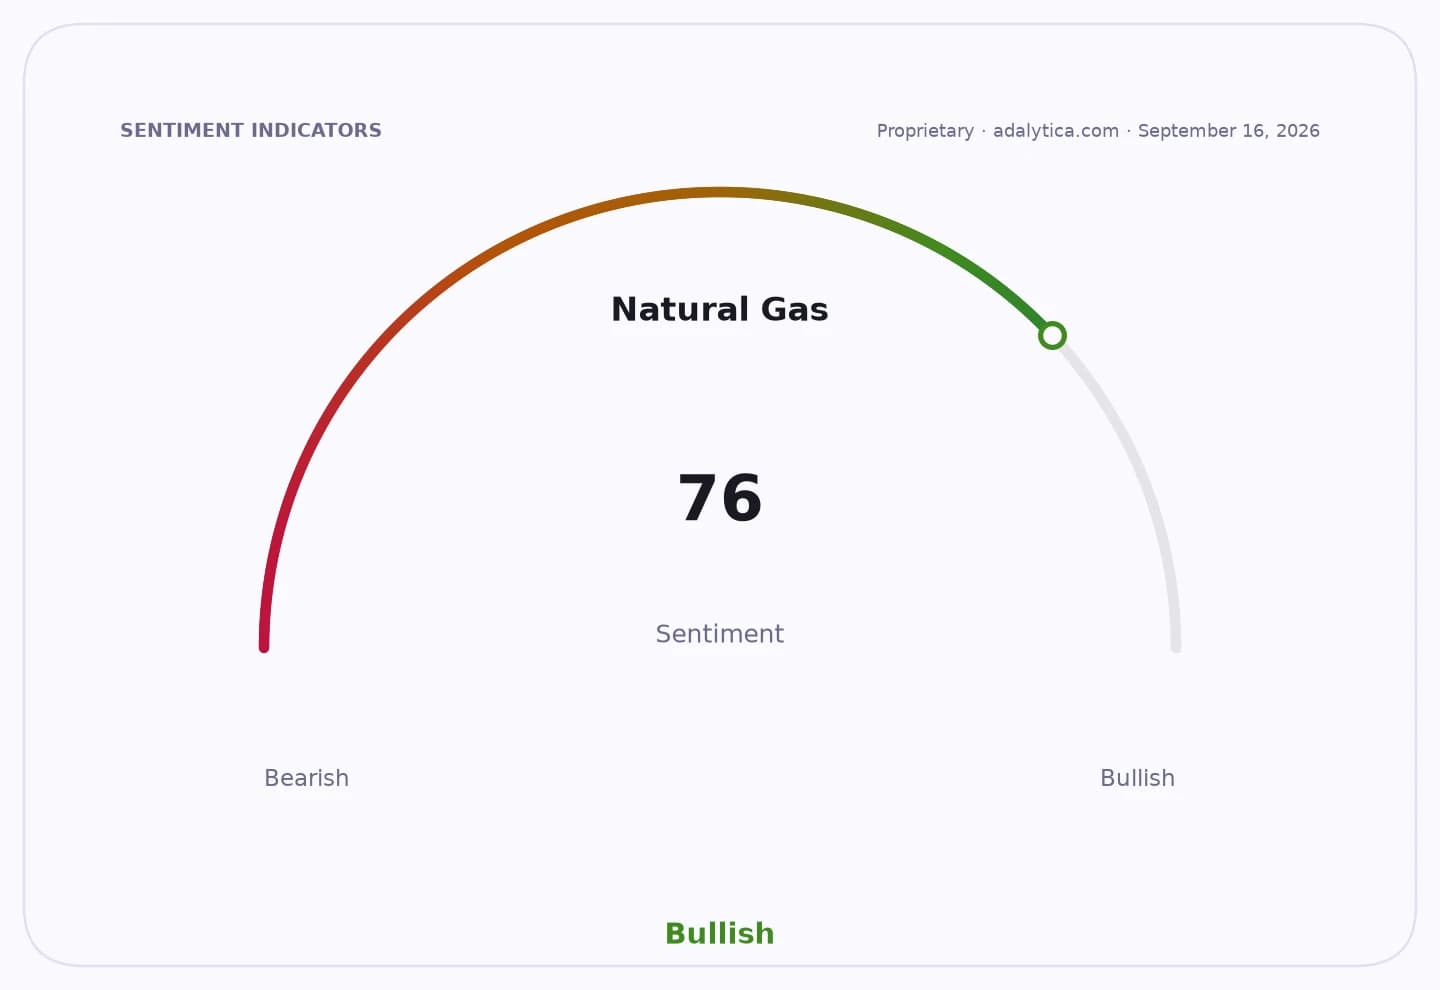
Adalytica’s Natural Gas Market Trade Signals show awareness at an “Extreme Fear” level even though sentiment is neutral, a combination that points to elevated anxiety around supply conditions rather than outright panic. With heating demand usually rising into late autumn and winter, traders will be watching storage updates, weather forecasts and any new disruptions to LNG flows for the next move.
| Entity | Gains | Losses |
|---|---|---|
| LNG exporters | ▲Higher winter prices | ▼Demand uncertainty |
| Gas producers | ▲Stronger pricing power | ▼Political scrutiny |
| European utilities | ▲None | ▼Higher procurement costs |
| Households and industry | ▲None | ▼Bigger heating bills |