Firmus has scrapped a planned $5 billion initial public offering, a reminder that even hot artificial intelligence infrastructure names are not immune to choppy markets and demanding valuation math.
Firmus scraps $5 billion IPO after valuation pushback
The Australian AI data-center operator, backed by Nvidia and with Meta as a customer, said the planned listing no longer made sense under current market conditions. That matters because Firmus was aiming to raise about A$5 billion at A$11 a share, valuing the company at roughly $30.6 billion and making it the second-largest new issue in Australian history. Instead, the board decided the terms did not fairly reflect the business or its long-term growth prospects.
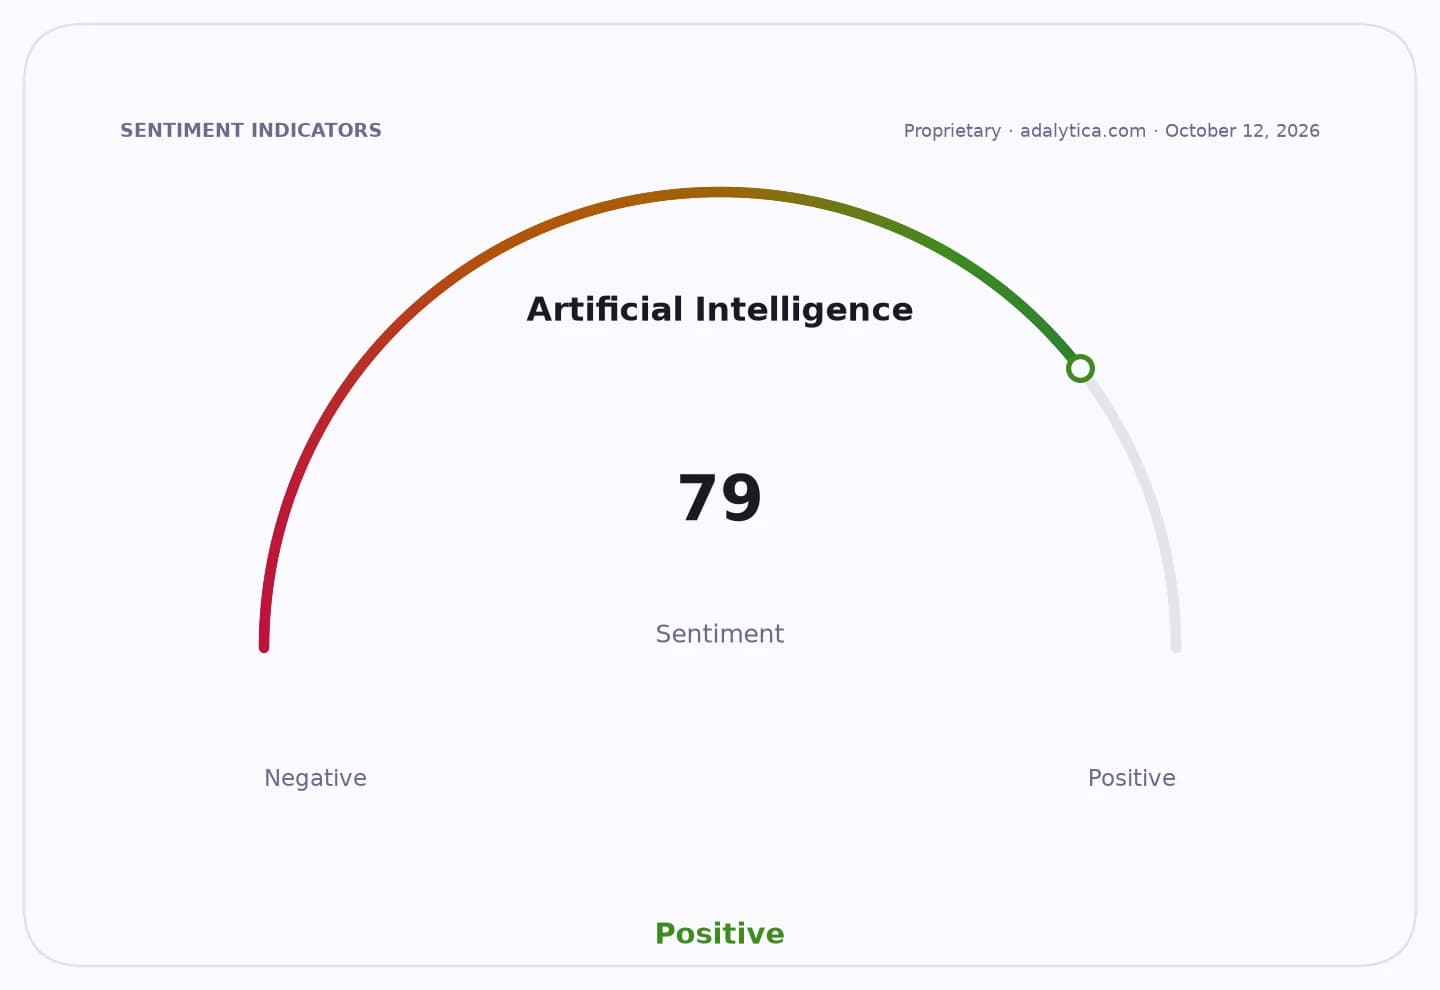
Sentiment IndicatorsⓘProprietary · adalytica.com · October 11, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the withdrawal says as much about the market as it does about Firmus. Big AI infrastructure projects need enormous capital, and the public markets have been willing to reward that story only when pricing looks reasonable. When volatility picks up, buyers become more selective, especially for companies that are still spending heavily and have valuations that can jump quickly from one funding round to the next. Firmus was valued at more than $10.5 billion in August after a $2 billion private round led by Nvidia, Coatue Management, Blackstone and Jane Street. The proposed IPO price implied nearly a tripling in just a few months.
That gap is the real story here. The company can point to a compelling long-term narrative: Meta signed on to buy GPU compute from Firmus’s AI data centers in Southeast Asia, and those facilities are built on Nvidia’s DGX platform. In a world where hyperscalers, model developers and enterprise customers keep expanding AI workloads, the need for specialized power-hungry infrastructure should keep growing. But growth stories only get financed at the right price, and public-market investors have shown they will push back when expectations outrun fundamentals.
The setback does not necessarily damage the business case for Firmus, Nvidia or Meta. If anything, it reinforces how early the AI infrastructure buildout still is. Private capital may continue to bridge the gap, and Firmus said it will explore alternative financing in both public and private markets. That is important for long-term investors because the AI ecosystem is not just about chipmakers and software platforms; it also includes the data-center operators, power suppliers and infrastructure providers that turn demand into cash flow.
But the episode is also a warning. Capital-intensive AI plays can be powerful winners over a multi-year horizon, yet they are vulnerable to market windows closing just as quickly as they open. For investors building portfolios around the AI boom, the lesson is to favor businesses with durable financing, credible customers and realistic valuations. Firmus is still worth watching, but the IPO pullback suggests patience may be the smarter move.
| Entity | Gains | Losses |
|---|---|---|
| Firmus private backers | ▲Preserve optionality | ▼Lose IPO exit timing |
| Nvidia and Meta | ▲Keep strategic AI buildout alive | ▼Face slower public-market financing |
| Public IPO investors | ▲Avoid rich pricing | ▼Miss first listing opportunity |
| Competing AI data-center operators | ▲Gain a cautionary precedent | ▼Face tougher valuation scrutiny |