ForteBank and BI Group have launched a joint mortgage program for new homes in Kazakhstan, giving buyers an unusually flexible funding option as developers and lenders look for ways to keep primary housing sales moving.
ForteBank and BI Group launch Kazakhstan mortgage program
The deal matters because it lowers the upfront and monthly barriers to homeownership at a time when mortgage demand remains highly sensitive to borrowing costs. The program offers loans from 5 million to 100 million tenge, with terms of 12 to 180 months, a minimum down payment of 20% and no insurance requirement or prepayment fees.
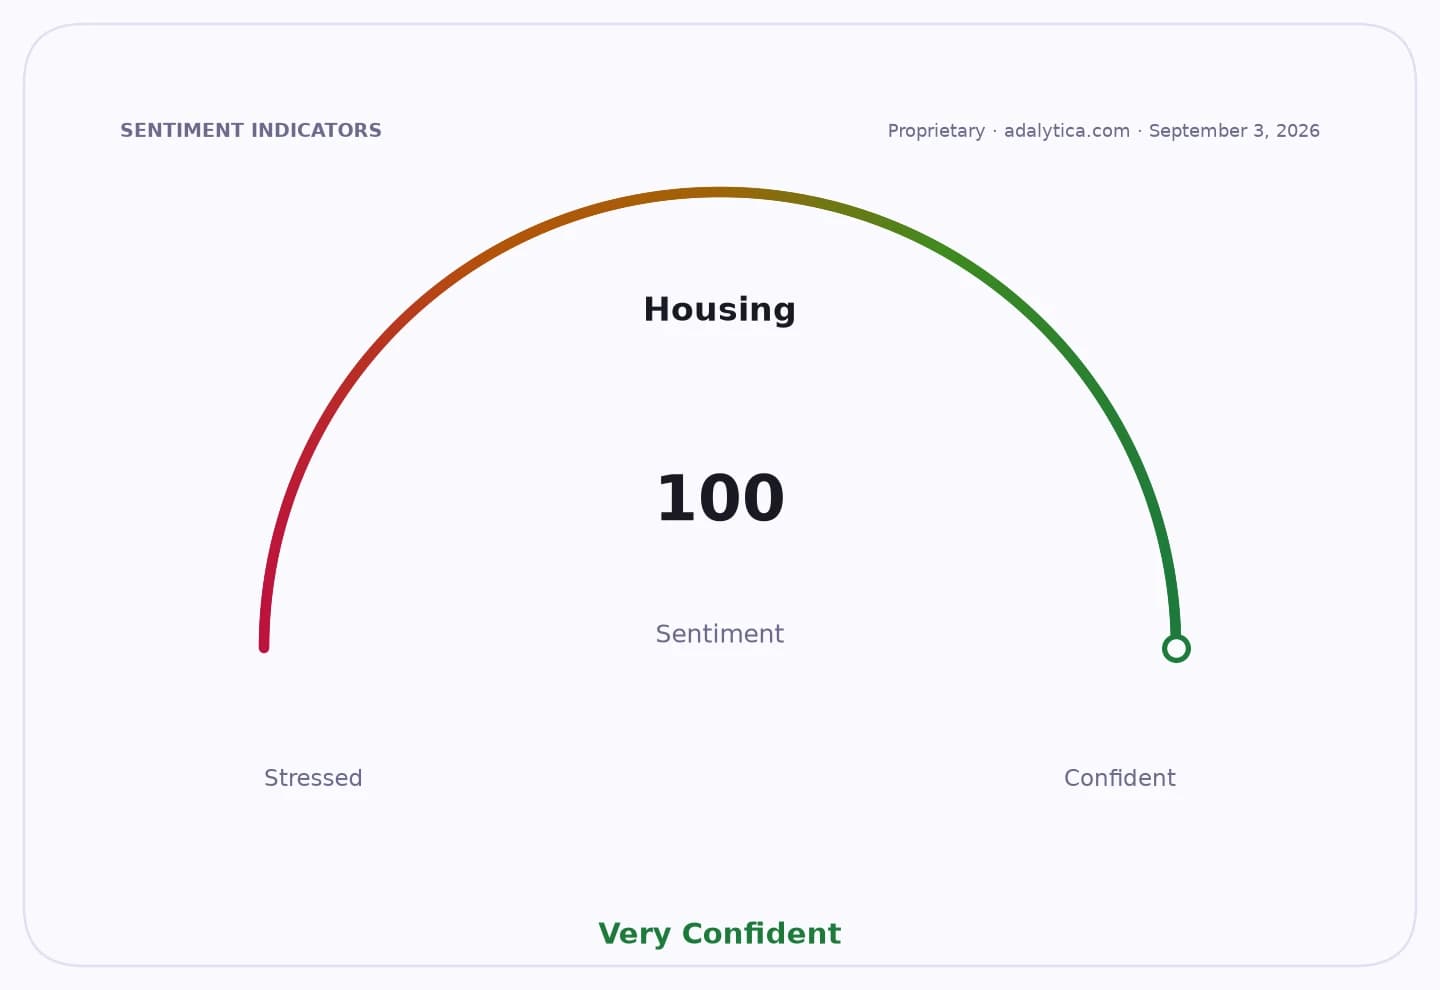
Sentiment IndicatorsⓘProprietary · adalytica.com · September 3, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The headline rate is 1% a year for a 12-month loan, while longer tenors carry a tiered pricing structure. At a 50% down payment, the rate is 13.5% on terms from 13 to 60 months, and Forte said customers will also get an exclusive discount on property purchases.
For BI Group, the partnership gives a major domestic builder another channel to support sales in the primary market, where access to financing is often as important as price. For ForteBank, it expands its retail mortgage franchise and deepens a partnership that aims to package financing and housing purchases into one sales channel.
The launch fits a broader push across Kazakhstan to widen mortgage access and stimulate the housing market through bank-led and government-backed financing. In Russia and the wider region, similarly structured mortgage partnerships have become a way for lenders and developers to defend volume when households are more rate-sensitive and affordability is under pressure.
Investors will watch whether the program translates into faster origination growth and stronger property sales, particularly if it can channel demand into BI Group projects without forcing the bank into excessive credit risk. The next catalyst is the publication of eligible developments and borrower requirements on Forte’s official channels, which will show how broad the program can become.
| Entity | Gains | Losses |
|---|---|---|
| ForteBank | ▲More mortgage volume | ▼Higher credit exposure |
| BI Group | ▲Stronger new-home sales | ▼Greater pricing pressure |
| Homebuyers | ▲Lower entry barriers | ▼Smaller down payment burden |
| Rival lenders/developers | ▲Little direct benefit | ▼Share loss to the partnership |