General Motors’ fresh $20 billion share buyback and raised cash-flow outlook sharpen the contrast with Tesla’s richly valued stock, making the old-line automaker look like the cleaner bet for investors searching for profits rather than perfection.
GM Buyback Raises Value Case vs Tesla
GM’s decision matters because it shows management thinks the stock is undervalued and because it has the balance-sheet capacity to return cash while still funding the business. The company said on Oct. 20 that third-quarter revenue rose nearly 3% to $50 billion and lifted full-year adjusted automotive free cash flow guidance to $11.5 billion to $12.5 billion. For a cyclical manufacturer, that combination of stable profitability and aggressive capital returns is exactly what income-oriented and value investors want to see.
Sentiment Indicators
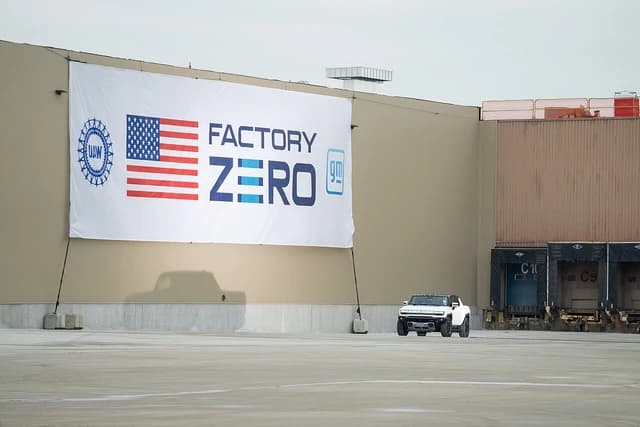
The buyback also arrives after GM had already exhausted a prior repurchase authorization, underscoring that the company is still generating enough cash to support further shareholder returns. That has helped offset concerns around inflation and EV losses, which have weighed on sentiment toward legacy automakers. GM shares have also held up technically better than Tesla in recent months, with the stock trading above both its 50-day and 200-day moving averages and its RSI in neutral-to-positive territory, a sign the market is giving the repurchase story some credibility.
Tesla, by contrast, remains a high-expectations trade. The company delivered 486,532 vehicles in its latest quarter, but that was still down more than 2% from a year earlier. More importantly for investors, Tesla’s trailing price-to-earnings ratio is about 351 and its market capitalization is roughly $1.5 trillion, meaning the stock already discounts years of success in autonomy, robotaxis and Optimus that have yet to show up in the earnings base. That makes the equity far more sensitive to execution risk, margins and any disappointment in the pace of commercialization.
The valuation gap is the heart of the story. GM is priced like a mature industrial that can compound cash and repurchase stock; Tesla is priced like a platform company with multiple optionality layers embedded in the share price. There is a bull case for Tesla — if autonomy monetization or humanoid robotics becomes meaningful, today’s multiple could eventually look less extreme. But the bear case is immediate: any slowdown in deliveries, margin pressure or delay in AI-driven products can compress a valuation that leaves little room for error.
For investors, the choice comes down to what they want to own in the current market. GM offers visible free cash flow, shareholder returns and a lower bar for success. Tesla offers faster growth potential, but demands near-flawless execution at a price that already assumes a lot of it. In that framing, GM is the more defensible buy today.
| Entity | Gains | Losses |
|---|---|---|
| GM shareholders | ▲Buyback support, stronger cash returns | ▼Less upside from multiple expansion |
| Tesla bulls | ▲Exposure to autonomy and robotics upside | ▼Valuation risk and execution pressure |
| Value investors | ▲Lower multiple, clearer cash flow | ▼Missed upside if Tesla re-rates higher |
| Tesla shorts | ▲Elevated valuation vulnerability | ▼Risk of squeeze if growth reaccelerates |