Builder confidence in the U.S. housing market fell more than expected in November, underscoring how sticky mortgage rates and affordability pressures are still freezing demand and limiting the case for a near-term housing rebound.
Homebuilder Confidence Falls as Mortgage Rates Stay High
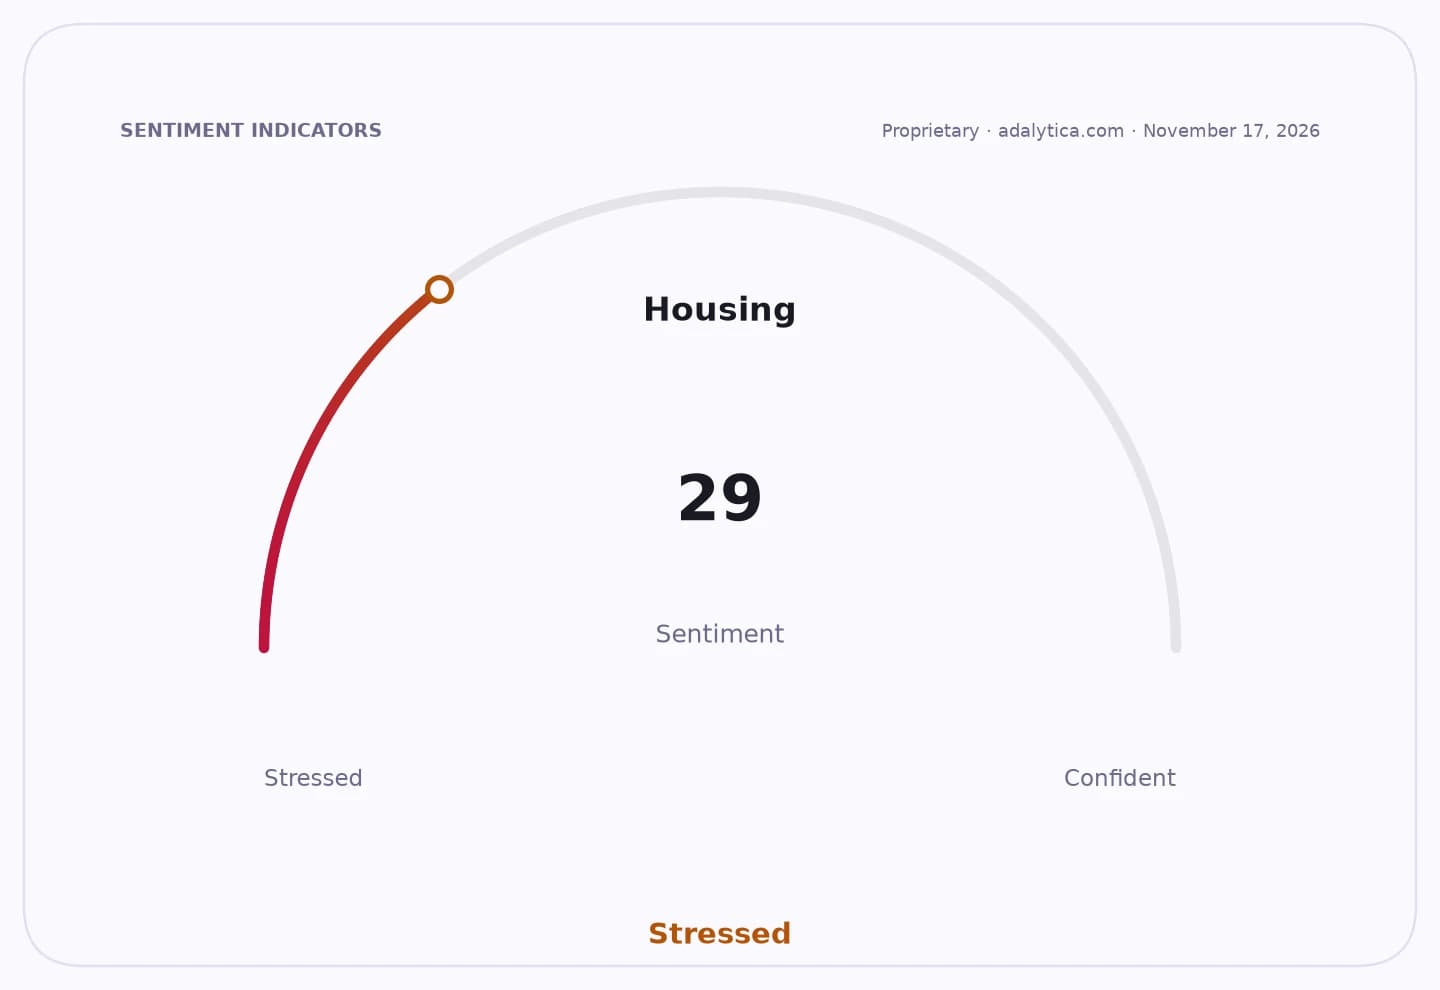
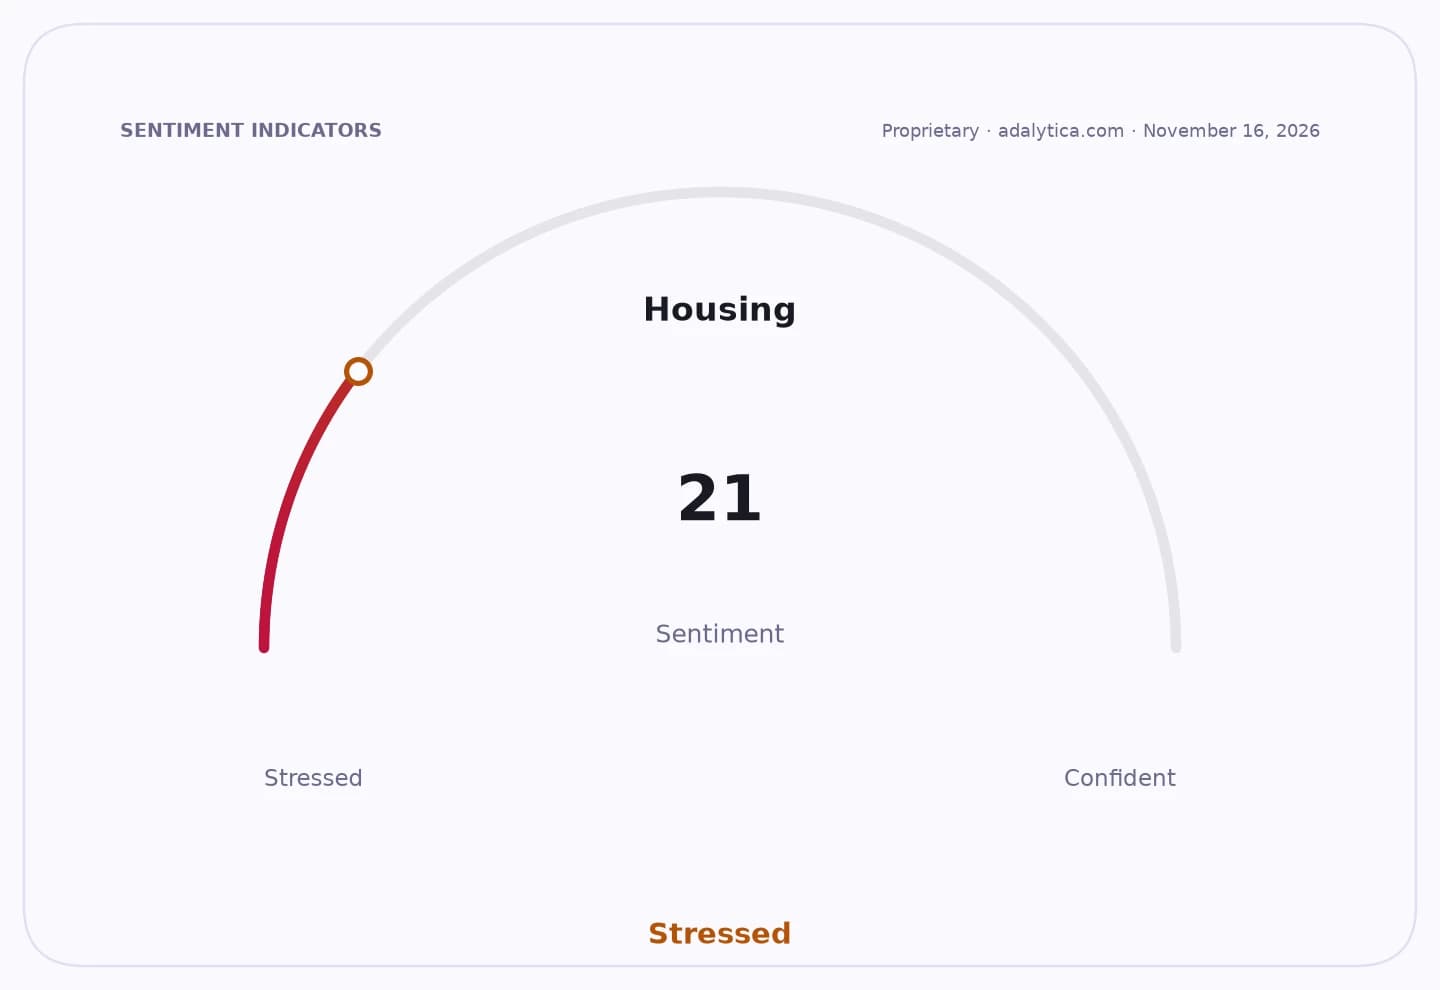
The National Association of Home Builders’ index dropped to 25 from 29 in October, missing expectations for 29 and landing at a level that still signals deeply pessimistic conditions. For the market, that matters because housing is not just a construction story — it is a rate-sensitive transmission channel for the broader economy, influencing everything from consumer wealth to bank lending, building-material demand and the pace of household formation.
Sentiment Indicators
The reading comes as the 10-year Treasury yield remains above 5%, a backdrop that keeps mortgage costs elevated even after recent volatility in bond markets. That has left many prospective buyers priced out or waiting, forcing builders to lean harder on incentives, discounts and product mix changes to keep traffic moving. The result is slower pricing power, tighter margins and a continued drag on housing-linked economic activity.
The weakness also lines up with what builders have been warning in recent SEC filings: demand remains challenged by elevated mortgage rates, weak consumer confidence and geopolitical uncertainty. Toll Brothers, D.R. Horton and PulteGroup have all pointed to a market still constrained by affordability, even as longer-term housing fundamentals remain intact.
Investors should read this as a reminder that the housing trade is still primarily a rate trade. If borrowing costs stay elevated, the upside in homebuilders is likely to remain uneven and selective, favoring companies with affluent buyers, strong balance sheets and enough pricing power to defend margins. Toll Brothers has held up better than some peers on that basis, while D.R. Horton and PulteGroup remain more exposed to the broad affordability squeeze.
The bigger investment takeaway is that the housing market is not in a clean recovery — it is in a holding pattern waiting for rates to break lower. Until that happens, the best opportunities are likely to sit in the downstream beneficiaries of eventual easing, not in a broad bet that homebuilder sentiment has already turned.
| Entity | Gains | Losses |
|---|---|---|
| Homebuyers | ▲Lower pressure if rates fall | ▼High mortgage costs |
| Homebuilders | ▲Selective luxury demand | ▼Softer traffic and incentives |
| TOL | ▲Affluent-buyer resilience | ▼Slower overall demand |
| DHI / PHM | ▲Scale in a weak market | ▼Margin pressure from affordability |