Indian 5% broken rice prices are poised to jump by as much as $60 a tonne, a move that underscores how quickly food inflation can reprice one of the world’s most important staple exports and squeeze buyers across Africa and Asia.
India rice prices rise on festive demand
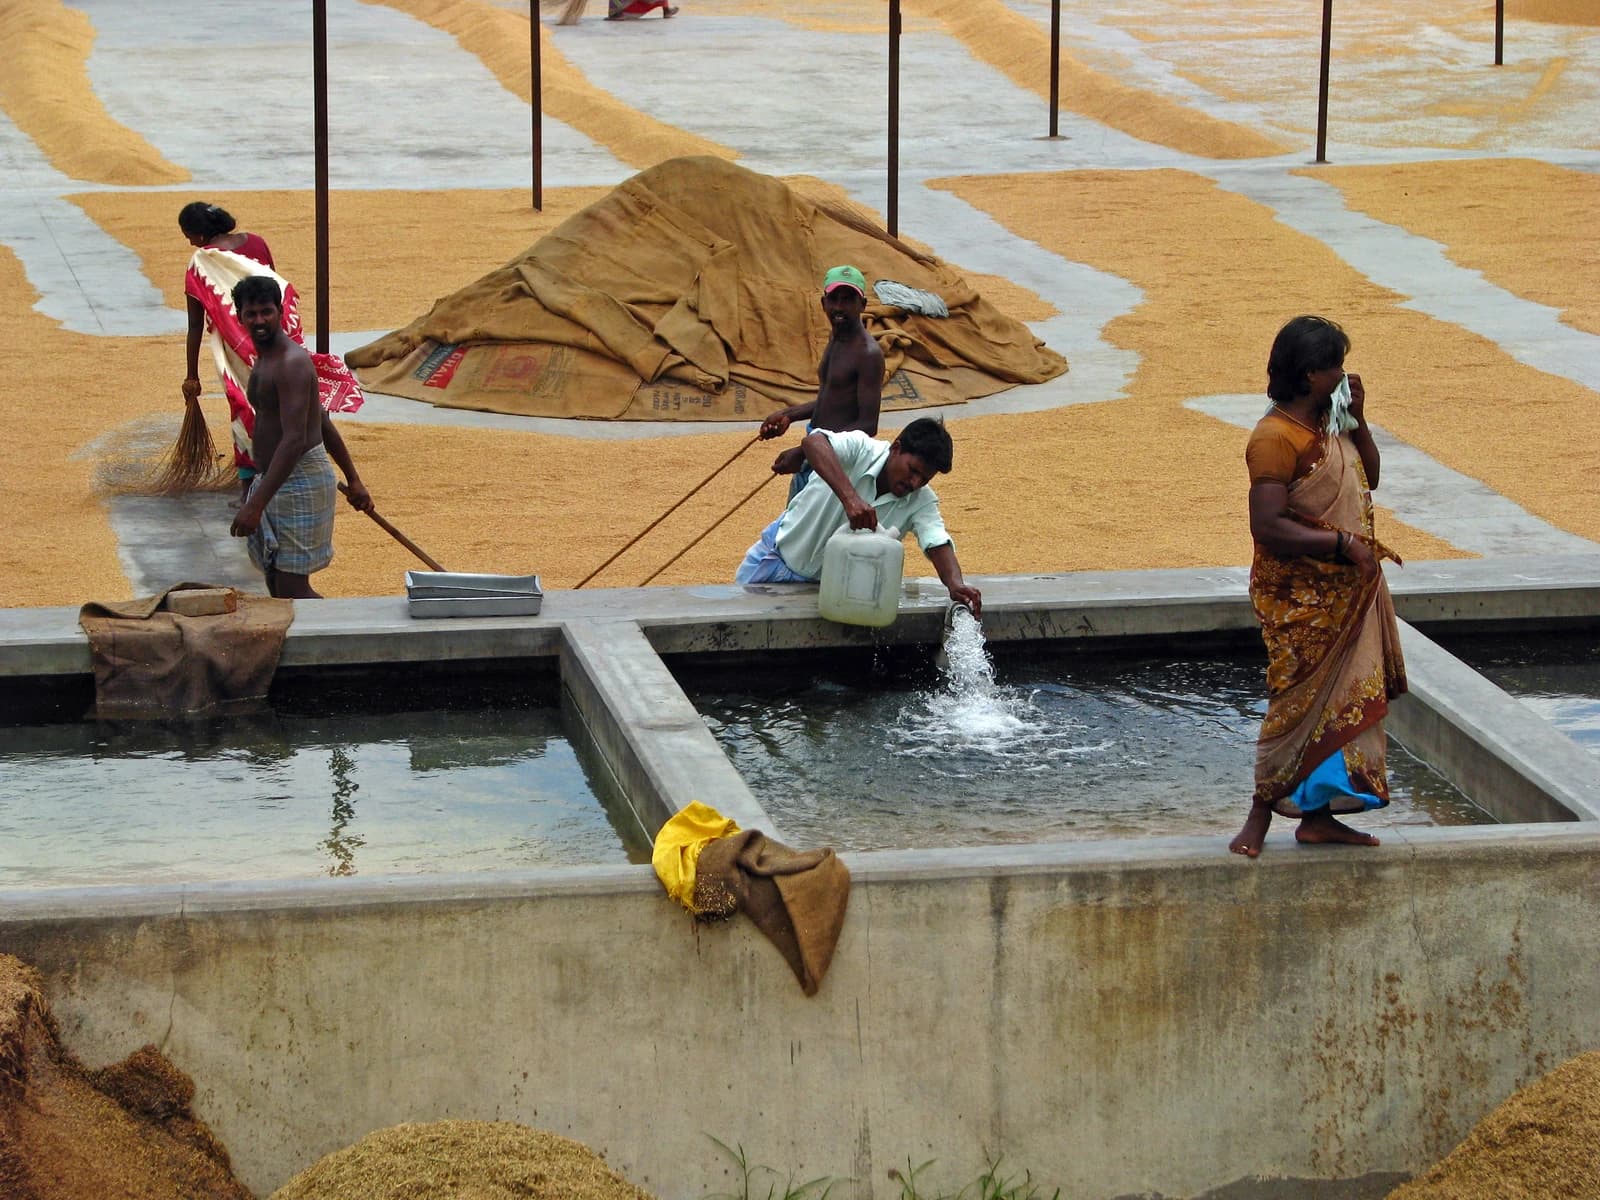
The economics are straightforward: stronger domestic and export demand during the festive season is tightening availability just as global rice markets are already digesting higher food costs. The result is a fresh leg up in exported rice prices, which have climbed to their highest levels since early 2025. For import-dependent countries, that means a larger bill for basic food security. For India, it means stronger export realizations for millers and traders, but also a higher risk that elevated rice prices feed into broader inflation pressures at home.
Sentiment Indicators
Food & Groceries
This matters because rice is not a niche commodity. India is the biggest exporter of the grain, and even a modest price increase in its benchmark broken-rice grade can ripple through tenders, shipping contracts and local food budgets from West Africa to Southeast Asia. The latest move comes even as some regional supply indicators remain mixed, including a surplus in North Sumatra and stable conditions in parts of the Mekong Delta. That divergence suggests the market is not being driven by a single supply shock, but by a combination of seasonal demand, regional trade flows and persistent appetite from African buyers.
The rally also shows up in the broader food-commodity tape. Wheat has rebounded sharply, with the WEAT ETF falling back toward the lower end of its recent range after a volatile run, while corn has also softened. That leaves rice as one of the clearest inflation-sensitive agricultural trades right now. When staples rise together, food processors, importers and consumer-goods companies feel the pressure first, and central banks cannot ignore the pass-through if it broadens.
For investors, the key is that this is not just a short-lived pricing blip. A $60-a-tonne move in Indian broken rice points to a market still underestimating how durable food inflation can be when demand is seasonal and supply is fragmented. The upside may favor exporters, logistics providers and commodity merchants with access to Asian grain flows. The losers are the importers, packaged-food companies and low-income consumers who face the cost of a basic staple becoming more expensive again.
My view: stay long the supply-chain winners and be cautious on food-cost exposure. Rice is reminding the market that inflation can return through the grocery aisle before it shows up in the macro data, and that is exactly where the next trade begins.
| Entity | Gains | Losses |
|---|---|---|
| Indian rice exporters | ▲Higher realizations | ▼Stricter price sensitivity |
| African importers | ▲None | ▼Bigger food import bill |
| Food producers | ▲None | ▼Margin pressure |
| Consumers in rice-importing markets | ▲None | ▼Higher staple costs |