Investors are bracing for a tense week in which President Donald Trump’s decision to hold off on strikes against Iran collides with a fresh inflation update at home and a pivotal slate of earnings from Meta, Apple, Microsoft and Amazon.
Inflation and megacap earnings test market resilience
The immediate market significance is that Washington’s pause lowers the risk of an abrupt oil-supply shock and a rush into haven assets, even as the Middle East remains volatile and U.S. officials debate whether depleted defence munitions constrain any broader military option. That backdrop keeps geopolitics in the price action for crude, Treasuries, the dollar and defense stocks, but it also shifts attention back to U.S. inflation and the earnings engine driving the major indexes.
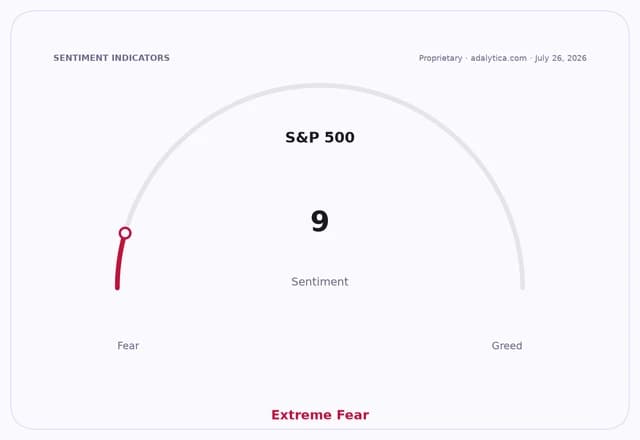
The consumer price outlook still matters because the Federal Reserve’s next move will depend on whether price pressures keep easing or reaccelerate. Forecasts in the data point to a 0.89% monthly rise in headline CPI in July and a 0.33% increase in core prices, underscoring that inflation is still sticky enough to keep rate-cut hopes fragile if the next print comes in hot.
Treasury traders are already signaling that tension. The 10-year yield has climbed to around 4.75% from 4.63% earlier this week, reflecting a market that is pricing less policy relief and more compensation for inflation and geopolitical risk. Adalytica’s U.S. bond signals show extreme fear in Treasuries even as awareness is elevated, a pattern consistent with investors rotating defensively while waiting for clearer macro direction.
CPIAUCSL vs CPILFESL — macro contextadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
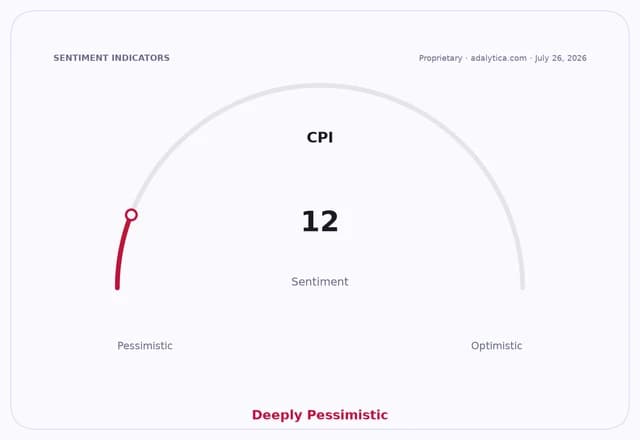
That makes the inflation update especially important for equities. The S&P 500 is flashing extreme fear in Adalytica’s trade signals, while the dollar is also under pressure, suggesting positioning is fragile and investors are leaning hard on the next macro catalyst. A cooler CPI print would help justify higher valuations and support rate-sensitive names; a hotter reading would likely reinforce the recent jump in yields and keep pressure on growth stocks.
The earnings calendar could be the bigger near-term driver for individual stocks. Apple, Microsoft and Amazon all trade above their longer-term technical averages, but their recent price action shows investors are demanding proof that AI spending, cloud demand and consumer resilience are still translating into revenue and margin support. Apple closed at $333.02 on July 24, above its 50-day and 200-day moving averages, while Microsoft ended at $381.70 and Amazon at $232.11, both below their 50-day averages and still working through recent volatility.
Meta’s report may be the cleanest read on ad demand and AI monetization, while Microsoft’s numbers will be watched for cloud growth and capital spending discipline. Amazon’s results will gauge consumer demand, AWS momentum and whether tariff uncertainty or a softer dollar are affecting margins, and Apple will face scrutiny over device demand and its ability to sustain shareholder returns amid a higher-rate backdrop.
For investors, the story is not just that geopolitics, inflation and earnings are all hitting at once. It is that they are reinforcing the same question: whether the market can keep bidding up megacap tech and broad indexes while yields rise, the dollar weakens and the Fed remains constrained by still-elevated prices.
The next catalyst is the inflation release, followed immediately by the megacap earnings wave and any new White House signal on Iran, all of which could set the tone for Treasuries, crude and the market’s leadership trade into month-end.
| Entity | Gains | Losses |
|---|---|---|
| Oil bulls | ▲Geopolitical risk premium | ▼Strike pause |
| Treasury bulls | ▲Haven bid if risk spikes | ▼Rising 10-year yields |
| Big Tech longs | ▲Earnings upside / AI spend payoff | ▼Any margin miss |
| Fed doves | ▲Cooler CPI would revive cut hopes | ▼Sticky core inflation |




