India’s top software exporters are under renewed pressure as pricing weakness and geopolitical uncertainty weigh on growth prospects for the sector that powers much of the country’s services trade.
Infosys and Wipro Fall as IT Pricing Pressure Grows
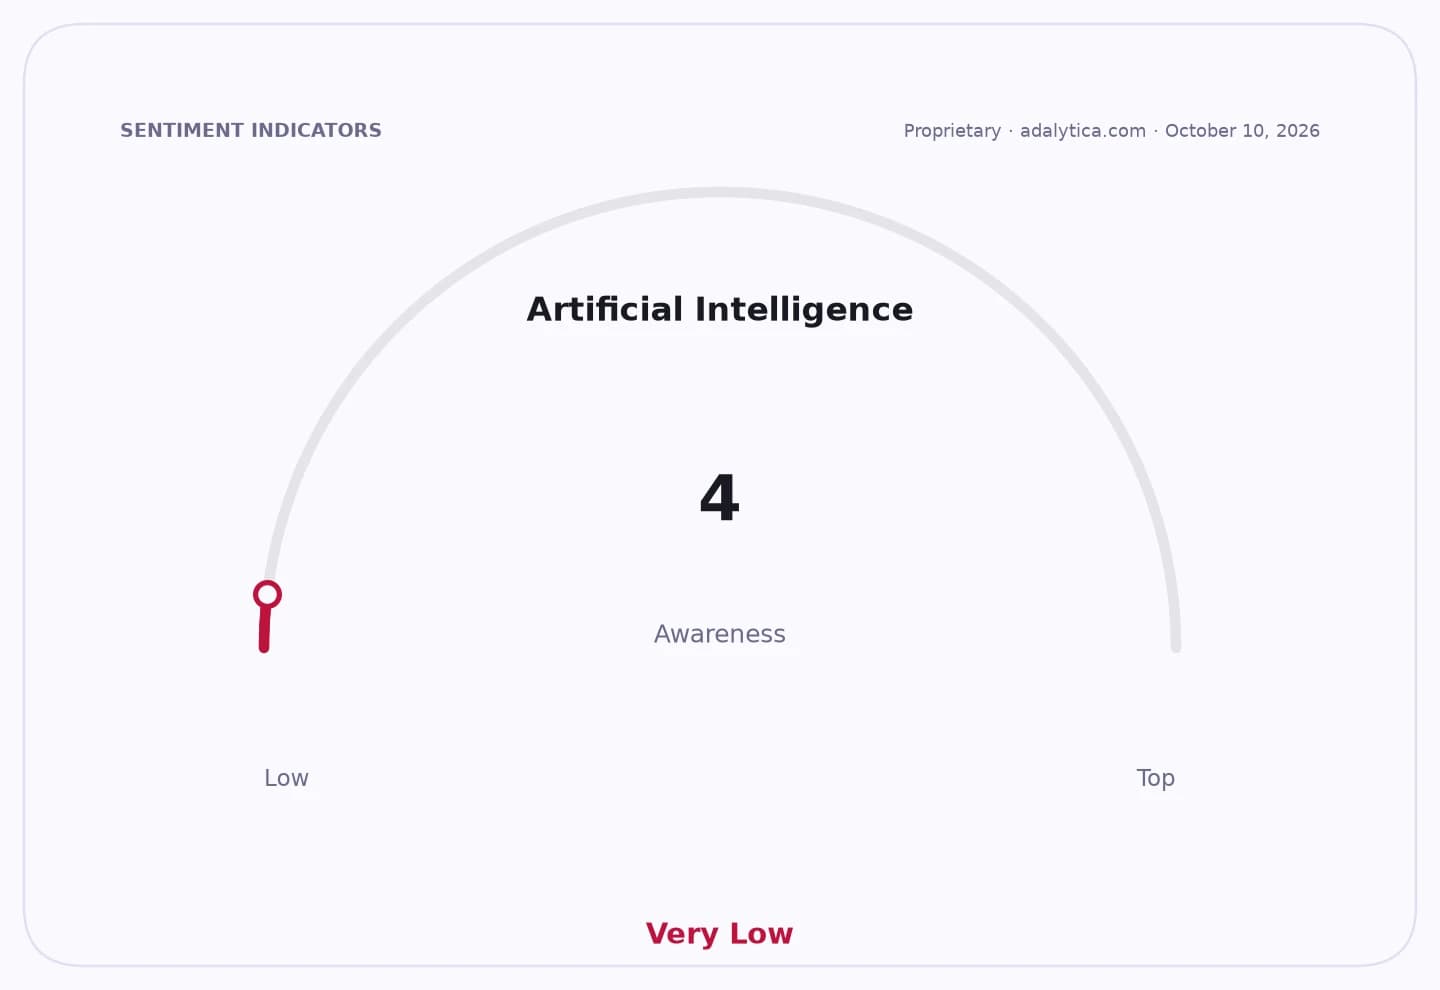
Infosys shares fell to $11.04 on Oct. 2, leaving the stock down sharply from a 2025 peak of $19.79, while the broader read on risk appetite darkened as a geopolitical fear gauge tracked by Adalytica.com showed “Extreme Fear” at 4, after a 64-point drop in seven days. The move underscores how fragile sentiment has become for India’s IT names as clients delay discretionary spending and investors look past the recent rebound in some technology shares.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 4, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The sector’s challenge is economic as much as market-driven. Indian IT firms depend heavily on U.S. and European corporate demand, so slower enterprise spending, tighter budgets and pressure on billing rates flow directly into revenue growth and margins. That makes any pickup in global uncertainty — whether from trade tensions, election risk or broader geopolitical shocks — especially damaging because it tends to hit both client decision-making and deal closures at the same time.
For investors, the setup matters because Indian IT has long been treated as a defensive export play, supported by dollar revenues and recurring contracts. But that cushion weakens when pricing power fades and the industry’s earnings visibility narrows. Infosys’ share price remains below its 50-day moving average of $11.64 and well under its 200-day average of $13.29, a sign traders still see the stock as in a downtrend despite recent volatility.
Wipro has shown a similar pattern. The stock closed at $1.72 on Oct. 2, below its 200-day average of $2.15, while the broader risk backdrop remains unsettled and the U.S. dollar gauge sits in “Extreme Fear,” a mix that can complicate offshore earnings translation even when export demand holds up. Lower U.S. Treasury yields may eventually ease financing conditions for clients, but they do little in the near term if corporate tech budgets stay tight.
The narrative for the sector is straightforward: India IT is moving from a period of resilience to one where every basis point of pricing and every escalation in geopolitical stress can hit forecasts. Investors will be watching upcoming client commentary and quarterly updates for signs that deal pipelines are stabilizing, or that margin pressure is becoming the dominant theme again.
| Entity | Gains | Losses |
|---|---|---|
| Large IT buyers | ▲Lower vendor pricing | ▼Less service flexibility |
| India IT exporters | ▲Weaker rupee translation support | ▼Slower revenue growth |
| Infosys, Wipro | ▲Potential share rebounds on valuation support | ▼Margin pressure and downtrend risk |
| Investors in defensive tech | ▲Entry points after declines | ▼Earnings downgrade risk |