Requests for an overhaul of lending regulations are now emerging as a central theme in the real estate debate, with the stakes extending well beyond property buyers to banks, mortgage financiers and the broader pace of credit growth.
Mortgage Rule Reform Could Lift Lenders
The issue matters economically because tighter lending standards can restrain housing transactions, delay construction demand and slow the transmission of lower rates into the real economy. In the US, mortgage lending is already operating in a still-restrictive environment: the 10-year Treasury yield is around 4.64%, the unemployment rate is holding near 4.2% and single-family housing starts are forecast at 1.33 million for July after a volatile run. That combination points to a housing market that is stabilizing, but not yet free of financing friction.
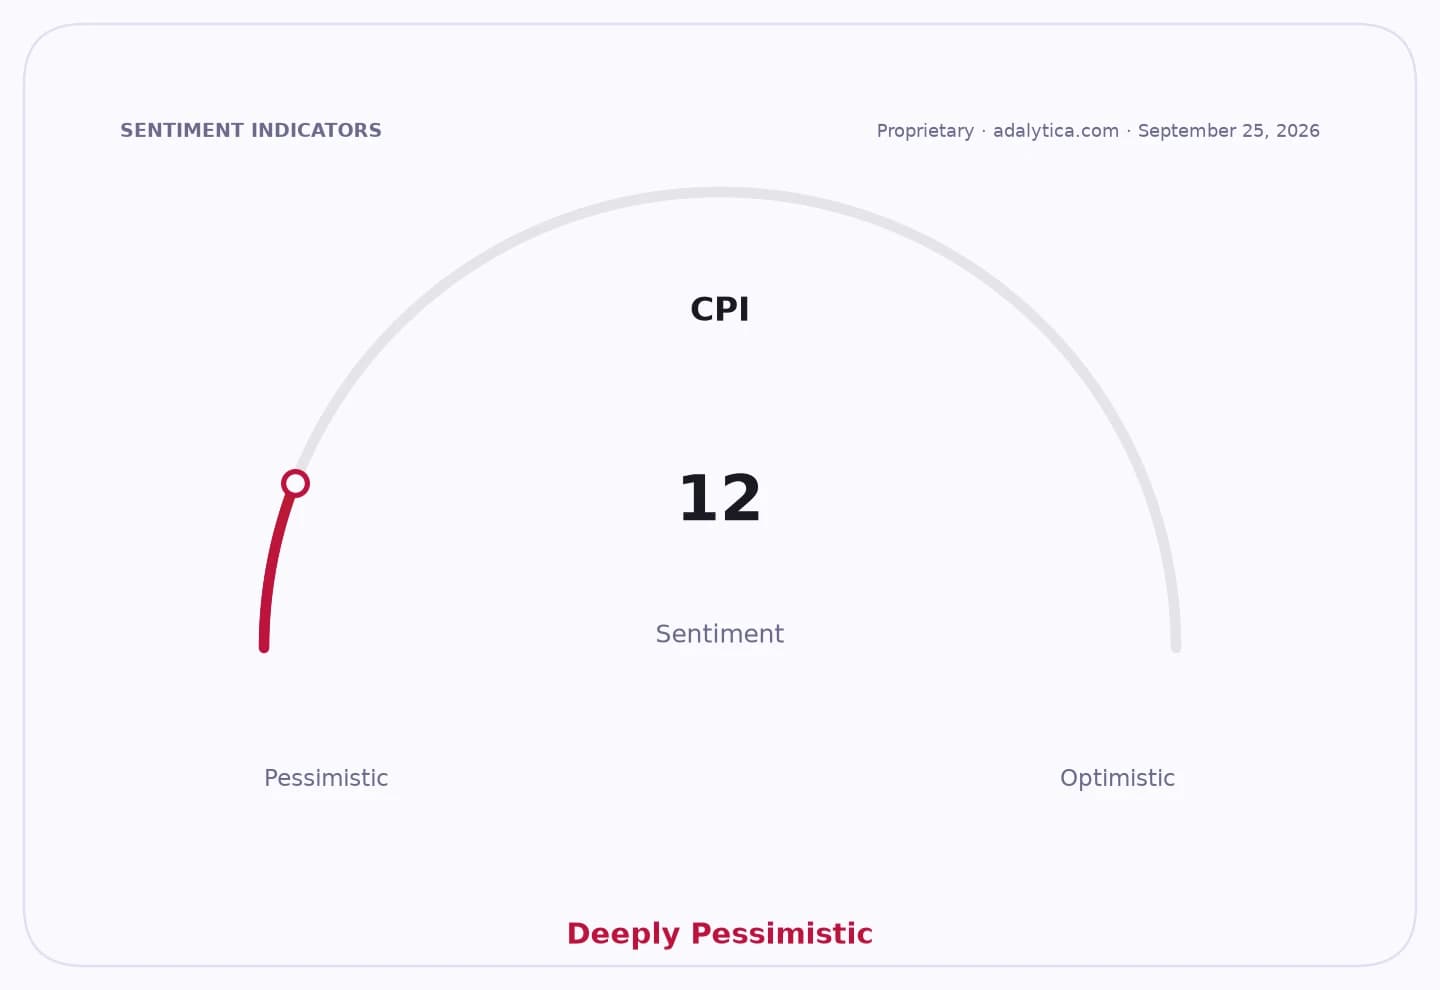
Sentiment IndicatorsⓘProprietary · adalytica.com · July 23, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the debate goes straight to earnings and valuation for lenders exposed to residential credit. Freddie Mac, or FMCC, traded at 5.48 on July 23, below its 200-day moving average of 7.69, while its RSI sat at 46.5, suggesting the stock has recovered from oversold conditions earlier in the year but remains technically fragile. The company’s 10-Q showed a low allowance for credit losses ratio of 0.23% on total loans, underscoring that credit quality is not the immediate problem; the bigger question is whether easier rules could unlock volume in a market where affordability and approval standards have capped activity.
That tension is visible in other rate-sensitive names. Equity Residential, which benefits from a housing system that keeps would-be buyers in rentals, has risen to 68.52 from 59.67 in March and still trades above both its 50-day and 200-day moving averages. Zions Bancorp has also bounced from sharp weakness late last year, with the stock at 68.74 and its 50-day average above its 200-day, reflecting renewed confidence in banks with significant lending franchises. If regulation becomes less restrictive, mortgage originators and housing-finance players could see more loan flow; if not, banks may continue to favor disciplined underwriting over growth.
The broader narrative is one of policy trying to balance access and stability. Regulators and policymakers are being pressed to make credit more available without repeating past mistakes, especially after years in which stricter standards, higher rates and borrower caution compressed mortgage demand. Supporters of reform argue that the current framework is too rigid for a housing market still constrained by affordability. Opponents say easing rules too far could weaken underwriting just as the economy is normalizing and delinquency risks are still being watched closely.
For investors, the next catalyst is whether those reform requests translate into actual changes in mortgage eligibility, collateral requirements or repayment flexibility. Any loosening would likely be positive for lenders, homebuilders and housing-finance intermediaries, while renters and existing homeowners may see a mixed effect from stronger demand and firmer prices. If the debate stalls, the market is likely to remain in a slow-growth pattern in which housing support comes from rates and income growth, not from regulation.
| Entity | Gains | Losses |
|---|---|---|
| Mortgage lenders | ▲Higher loan volume | ▼Narrower underwriting margins |
| Homebuyers | ▲Easier credit access | ▼Less borrower protection |
| Banks with lending exposure | ▲Fee and interest income | ▼Higher credit-risk scrutiny |
| Renters / REITs | ▲Steadier demand for rentals | ▼Less upside from homeownership shift |