Nigeria’s government says the hardest part of President Bola Tinubu’s reform drive is over, and that matters because the next test is whether stability turns into jobs, higher incomes and a more investable economy for the long run.
Nigeria reforms and naira near key technical levels
At Nigeria’s 66th independence anniversary briefing, officials said the administration is moving from shock therapy to consolidation after scrapping the petrol subsidy, unifying foreign exchange windows and tightening fiscal and monetary policy. Those steps were painful for households, but they also helped restore some macroeconomic balance in Africa’s biggest economy, which has spent much of the past two years battling inflation, currency weakness and weak consumer demand.
For investors, that shift is more important than the rhetoric. A country that can begin to stabilize its currency, improve its external position and expand domestic refining capacity becomes easier to model and, eventually, easier to finance. That is especially true in a market like Nigeria, where policy credibility can matter as much as growth rates. The government is now betting that the gains from reform will unlock more private investment, stronger production and better allocation of capital across transport, power, agriculture and digital infrastructure.
The message is not that the problems are gone. Poverty remains high, insecurity still weighs on farms and logistics, and power, ports and roads continue to constrain businesses. But officials are arguing that the direction of travel has changed. In practical terms, that means more room for credit growth, more predictable policy and a stronger case for companies exposed to local consumption, infrastructure build-out and domestic manufacturing.
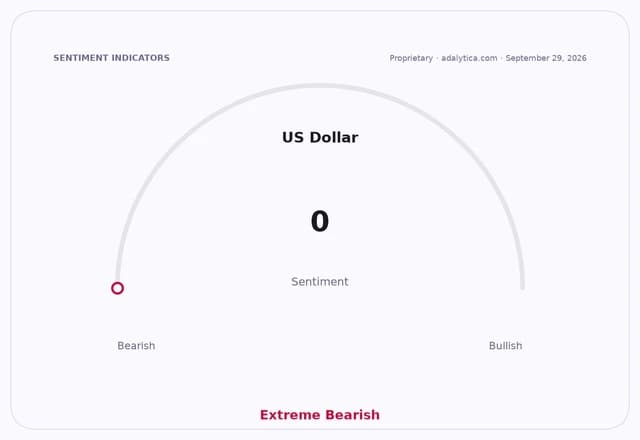
There is also a market angle worth watching. The naira has been volatile, but technical readings on NGN=X show the currency near 1,323 to the dollar, below its 50-day and 200-day moving averages, with momentum indicators still soft. That suggests the currency has not fully shaken off pressure, even if the policy backdrop is more orderly than it was a year ago. By contrast, the EZA ETF, which tracks South African equities and often serves as a broader gauge of emerging-market appetite in Africa, has slipped back toward its own 50-day and 200-day moving averages after a strong run earlier in the year. That kind of caution in regional markets reinforces why Nigeria’s reform credibility will matter to portfolio investors looking for durable returns rather than short-lived rebounds.
The government is also trying to turn reform into something more tangible for voters and consumers. It says it is spending on roads, rail, airports, seaports, electricity and digital connectivity, while also supporting farmers with seeds, fertilizer, irrigation and storage to ease food inflation and build agro-processing value chains. Those are the kinds of investments that can compound over years, not weeks, if execution improves.
For long-term investors, the right question is not whether Nigeria’s reforms were painful — they were — but whether they now create a platform for sustained earnings growth across banks, consumer companies, infrastructure providers and energy-linked businesses. If the administration can keep policy steady, improve security and reduce the cost of doing business, Nigeria could move from stabilization to a much more investable growth story. That is still a work in progress, but it is a story worth keeping on the watchlist.
| Entity | Gains | Losses |
|---|---|---|
| Tinubu administration | ▲Reform credibility | ▼Short-term popularity |
| Nigerian businesses | ▲Better policy stability | ▼High operating costs |
| Consumers and workers | ▲Potential jobs and income growth | ▼Near-term pain from reforms |
| Investors in Nigeria | ▲Longer-term valuation upside | ▼Those expecting quick fixes |