NVIDIA is pitching a new AI factory blueprint for Europe that could materially ease the two biggest bottlenecks to AI expansion on the continent: electricity and cooling capacity.
NVIDIA pitches DSX AI factories for Europe
At its GTC Berlin event, the chipmaker said leading ecosystem partners in Europe are beginning to adopt its DSX AI Factory Platform, a full-stack reference architecture designed to cut cooling water use to near zero and reduce power consumption by as much as 30% for the same AI output. That matters because Europe’s AI buildout is increasingly constrained not by demand, but by the practical limits of power grids, water availability and data-center infrastructure.
The DSX system combines computing, networking, storage, software and power-and-cooling design from the outset, rather than bolting them together after the fact. NVIDIA says the architecture uses liquid-cooled compute paired with outdoor dry coolers in a closed loop, avoiding the evaporative water use common in conventional data centers. On a 2-gigawatt deployment, it says the system could save as much as 54 million liters of water a day, equal to the daily consumption of about 180,000 households.
The economics are straightforward. AI infrastructure has become increasingly capital-intensive, but the operating constraint is shifting from chips alone to the cost and availability of power and cooling. If a factory can generate the same number of tokens with 30% less electricity, or use the same power budget to run more GPUs, it improves utilization economics and lowers the cost per unit of AI output. That could help hyperscalers, sovereign buyers and enterprise operators justify faster deployment, particularly in markets where permitting, grid access and environmental rules are slowing expansion.
NVIDIA is also trying to solve the less visible problem of load management. Its DSX MaxLPS software dynamically allocates power within a fixed electrical budget. In tests at Nscale’s Iceland facility using four racks of GB300 NVL72 systems, NVIDIA said inference throughput rose 49% and managed GPU capacity increased 37% on the same 264-kilowatt power budget. Lambda separately reported a 24% gain in cluster token throughput on HGX B200 systems.
Those gains matter for investors because they suggest NVIDIA is no longer selling only accelerators, but an increasingly integrated operating model for AI factories. That broadens the company’s addressable market across software, networking, cooling and orchestration, while also raising the strategic value of its ecosystem partnerships. It also reinforces a key investment thesis: the AI cycle is moving deeper into infrastructure optimization, not just raw chip demand.
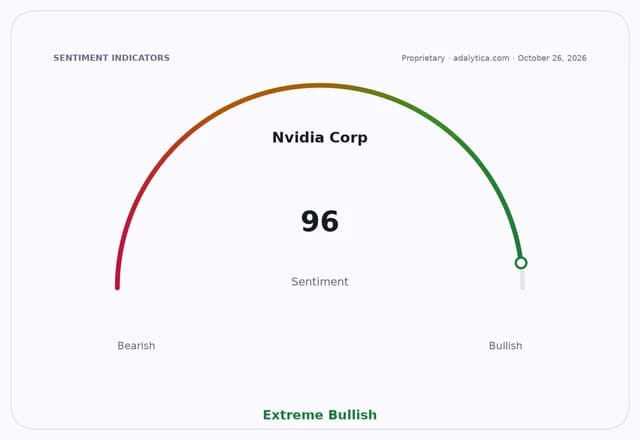
The stock market has already priced in much of that optimism. NVIDIA shares have traded with elevated volatility in recent weeks, with the stock closing at $216.00 most recently, below its 50-day moving average of $222.22 and well above its 200-day average of $203.52. The pullback suggests investors are still demanding evidence that the AI capex boom can translate into sustained monetization, not just faster hardware turnover. Still, the new DSX rollout strengthens the case that NVIDIA can defend pricing power by embedding itself in the full data-center stack.
The European angle is especially important. Regional governments and utilities face rising pressure to support AI investment without worsening strain on grids or water systems. NVIDIA’s DSX Flex software, which can shift demand in line with utility pricing and grid events, fits into that policy environment. In trial work with Emerald AI, EPRI, Nebius and U.K. National Grid, the company said it cut cluster power draw by up to 40% during simulated grid stress without stopping critical workloads.
That makes the platform attractive to both operators and regulators, but it also creates a split for the market. AI infrastructure providers that can demonstrate lower energy intensity may win permits, contracts and financing faster. Less efficient rivals could face higher operating costs, tighter site selection and greater scrutiny from utilities and policymakers.
The bull case is that DSX becomes a template for Europe’s next wave of AI factories, strengthening NVIDIA’s ecosystem moat and accelerating deployment where power is scarce. The bear case is that adoption remains limited to premium projects, leaving the broader market still constrained by grid capacity, cost inflation and execution risk. Either way, the message from Berlin is clear: the next phase of AI competition will be decided as much by watts, water and orchestration software as by chips.
| Entity | Gains | Losses |
|---|---|---|
| NVIDIA | ▲Broader AI factory moat | ▼Pure-chip rivals |
| European AI operators | ▲Lower power and water use | ▼Legacy data centers |
| Utilities/grid operators | ▲Flexible demand response | ▼Fixed-load customers |
| Energy-intensive rivals | ▲— | ▼Higher operating costs |