Higher crude prices and a weaker rupee are set to lift earnings at India’s state-run upstream producers in the September quarter, while fuel retailers are expected to show only a partial recovery as refining and marketing margins remain under pressure.
ONGC, Oil India Q2 earnings rise on crude and rupee
Brokerage previews from Elara Capital and JM Financial point to ONGC and Oil India as the clearest beneficiaries of Brent averaging $91.3 a barrel in Q2 and of rupee weakness, even as crude realisations ease from the prior quarter. JM Financial said ONGC’s net crude realisation may slip to $90-$92 a barrel from $96-$100 in Q1, but higher volumes should cushion the decline, with crude sales seen up 1.8% quarter-on-quarter and gas sales up 3.4%. For Oil India, JM expects crude volumes to rise 6.2% and gas sales 3.5%.
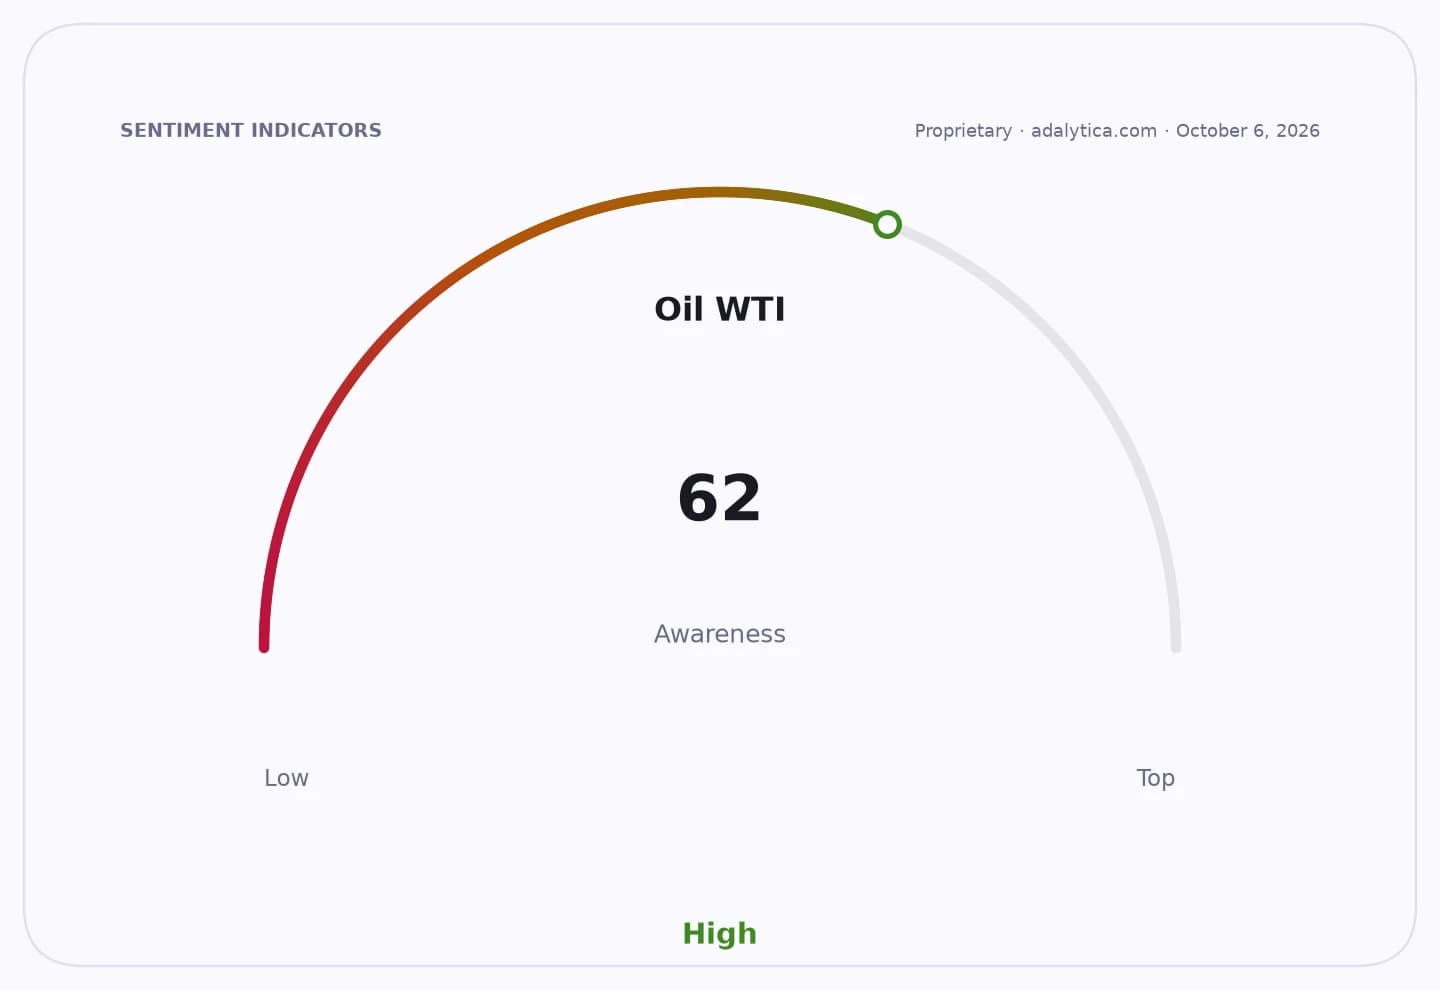
Sentiment IndicatorsⓘProprietary · adalytica.com · October 7, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
ONGC is projected to post Q2 revenue of about ₹43,232 crore to ₹43,311 crore, with adjusted net profit of ₹15,551 crore to ₹16,423 crore, up 58% to 66.8% from a year earlier. Oil India could report revenue of ₹7,600 crore to ₹8,040 crore and profit of roughly ₹2,738 crore to ₹2,771 crore, a jump of as much as 162% year on year. The numbers underscore how upstream earnings remain tightly linked to crude prices and currency moves, giving the producers leverage that refiners lack when feedstock costs rise.
The oil marketing companies, by contrast, are expected to recover sequentially but remain subdued. JM Financial estimates reported gross refining margins of $31.5 a barrel for Indian Oil, $37 for BPCL and $30 for HPCL, while gross auto-fuel marketing losses narrow to negative ₹17.7 a litre from negative ₹23.4 a litre in Q1 after the May fuel price hike. Even so, HPCL is forecast to stay in the red, while IOCL and BPCL are seen swinging back to profit after heavy first-quarter losses.
LPG under-recoveries are another swing factor. JM Financial sees them easing to about ₹11,000 crore from ₹21,200 crore in Q1, helped by ₹7,500 crore of government support, but still leaving refiners short of full recovery. Elara Capital said gross LPG losses may still be around ₹13,800 crore, keeping pressure on margins despite a better quarter for product cracks.
Petronet LNG is the other relative winner in the preview. Dahej terminal utilisation is expected to rise to 94% from 84% in Q1 as LNG imports rebound, supporting revenue and profit even as trading and inventory gains normalise. JM Financial estimates Q2 profit at about ₹1,131 crore, up 40.4% year on year.
For investors, the setup leaves the sector split between upstream cash generators and downstream companies still waiting for a cleaner margin recovery. JM Financial keeps Buy ratings on ONGC, Oil India and Petronet LNG, while staying bearish on IOCL, BPCL and HPCL; Elara is more constructive on BPCL and gives Accumulate ratings to IOCL and HPCL. The market now looks to the actual Q2 prints for confirmation that crude strength and rupee weakness outweighed the strain on refining and fuel marketing margins.
| Entity | Gains | Losses |
|---|---|---|
| ONGC, Oil India | ▲Higher upstream profits | ▼Lower realisations vs Q1 |
| IOCL, BPCL, HPCL | ▲Sequential margin recovery | ▼LPG under-recoveries, weak marketing margins |
| Petronet LNG | ▲Higher Dahej utilisation | ▼Normalising trading gains |
| Government support | ▲Contains LPG losses | ▼Still funds part of the burden |