PayPal shares surged after reports that Stripe and Advent had offered more than $53 billion for the payments group, a move that could reset the market’s view of a company that had lost most of its value since 2021.
PayPal Pops on $53 Billion Takeover Talk
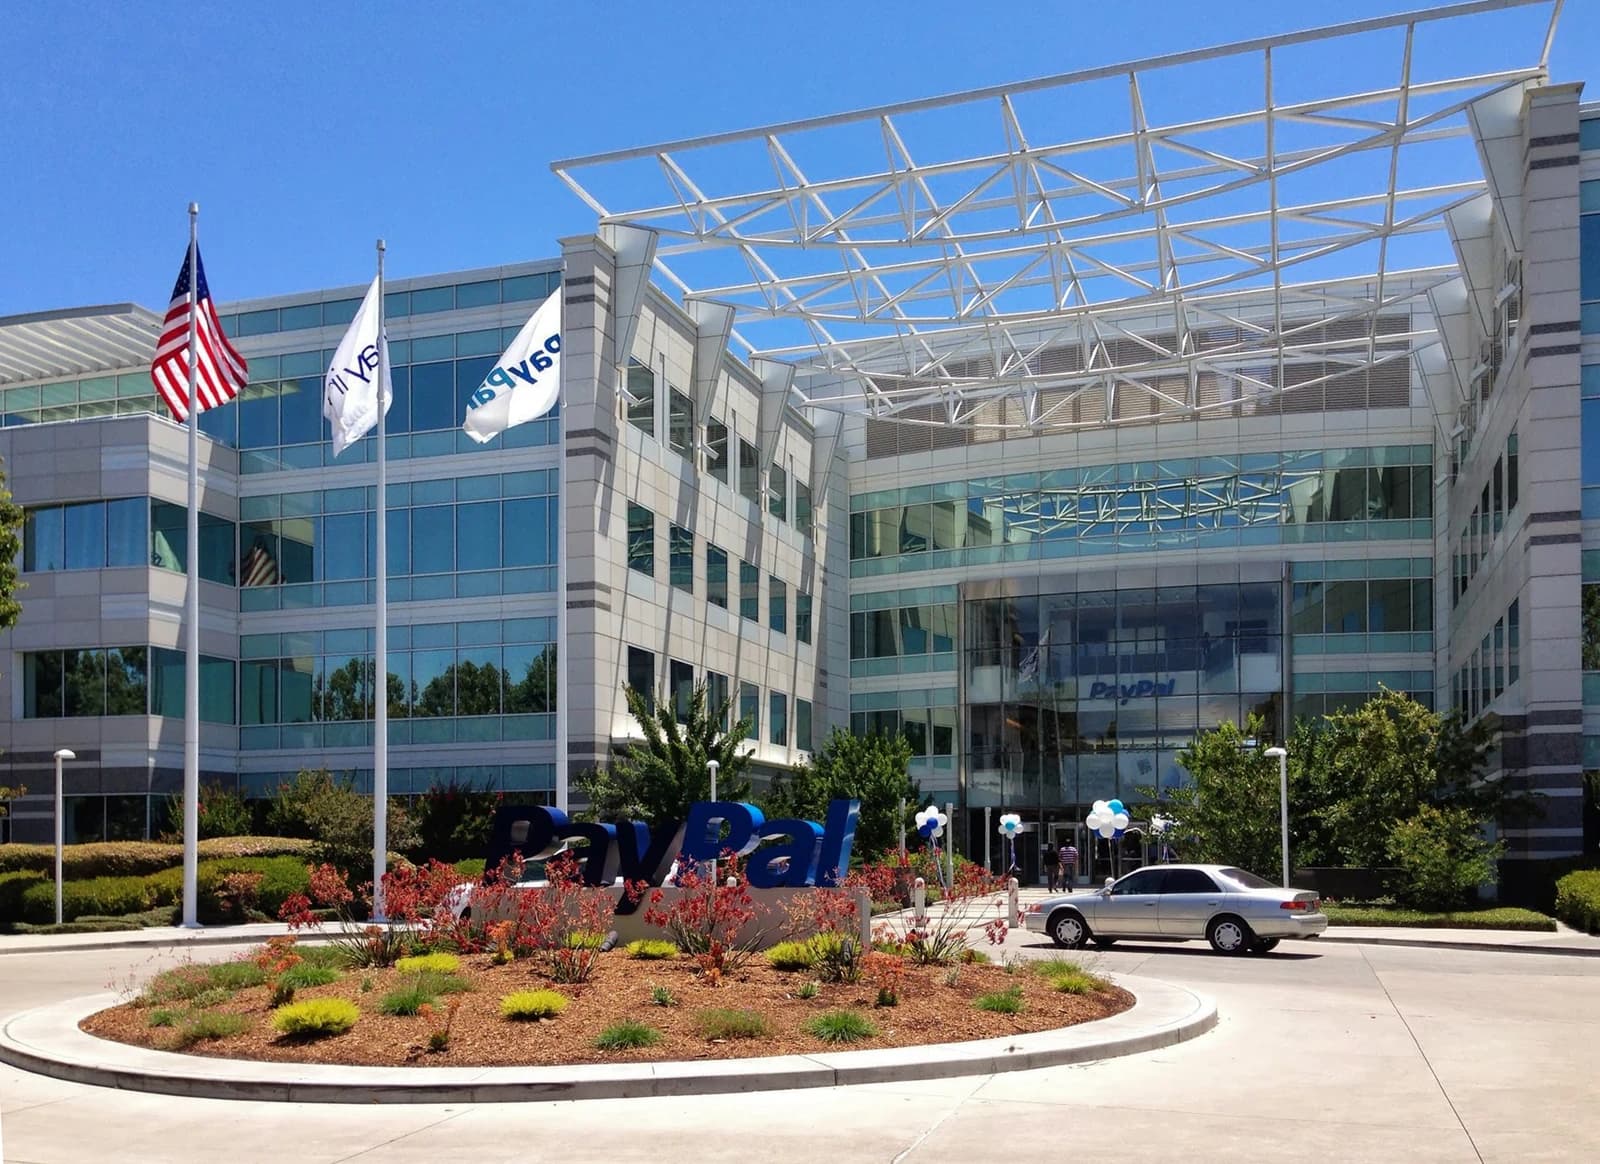
The bid matters because it turns PayPal from a long-discounted public-market laggard into a strategic asset with clear private-market value. At roughly $53 billion, the offer implies buyers see more worth in PayPal’s customer base, merchant reach and payments infrastructure than the stock market has assigned to it through years of slowing growth, margin pressure and competitive erosion. For investors, that is the central signal: the transaction pitch effectively validates the idea that PayPal’s business remains valuable even if the equity story has deteriorated.
Sentiment IndicatorsⓘProprietary · adalytica.com · July 15, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The stock jumped 20% to $55.52 in the latest session, its largest move in the data provided and a sharp reversal from the mid-40s trading range it had occupied only days earlier. Volume exploded to 89.3 million shares, far above recent levels, underscoring that the move was driven by merger speculation rather than a routine re-rating. The shares are now well above the 50-day moving average of $44.32 and have pushed through technical resistance near the upper Bollinger Band at $50.92, while the RSI reading of 84 suggests the stock has entered overbought territory on conventional technical indicators.
That kind of reaction is consistent with a name that had been priced for disappointment. PayPal had been trading at a deep discount to its earlier peak, with the market focusing on the loss of momentum in its branded checkout franchise, intense competition from rivals including Block’s Square ecosystem and broader pressure on consumer and digital-payments volumes. A takeover bid does not erase those problems, but it changes the framework: instead of asking whether PayPal deserves a premium multiple, investors now have to assess what a buyer is willing to pay for scale, data, merchant relationships and cash generation.
For Stripe, a deal would be unusual but strategically meaningful. The privately held payments company has long been associated with software-led merchant acquisition, not large public-company takeouts. Advent’s role suggests financial backing and a willingness to underwrite a complex transaction. Together, the pair would be signaling confidence that PayPal can be streamlined, integrated or repositioned more effectively outside the public markets than within them. The bull case is that a private owner could extract value from PayPal’s operating leverage and broader distribution. The bear case is that the offer may reflect not hidden upside, but rather the difficulty of fixing the business while it remains exposed to public-market scrutiny and sector compression.
The wider significance extends beyond one stock. A successful bid would mark one of the biggest shake-ups in digital payments in years and could accelerate consolidation across a sector where scale, network effects and cost discipline are becoming more important. It also arrives at a time when broader equity sentiment is mixed and the U.S. dollar is weak on the Adalytica trade signals snapshot, conditions that can support risk assets but also magnify scrutiny of company-specific catalysts. For PayPal holders, the immediate question is whether the offer becomes a floor for the shares or the opening salvo in a bidding contest.
What investors will watch next is simple: whether PayPal’s board engages, whether rival bidders emerge, and whether the valuation holds if the market decides the bid is credible. If the offer advances, it could close the gap between PayPal’s public-market discount and the strategic value assigned by bidders. If it stalls, the stock may quickly revert to a more fundamental debate about growth, margins and whether the company can justify even part of the rumored premium on its own.
| Entity | Gains | Losses |
|---|---|---|
| PayPal shareholders | ▲Takeover premium | ▼Public-market discount |
| Stripe and Advent | ▲Strategic scale | ▼Deal execution risk |
| Rival payments firms | ▲Acquisition benchmark | ▼Higher competitive pressure |
| Short sellers | ▲Potential squeeze loss | ▼Squeeze risk |




