A Petrobras drilling probe in Brazil’s Foz do Amazonas basin is the kind of catalyst that can re-rate the country’s offshore oil story if it confirms hydrocarbons in one of the world’s most closely watched frontier regions.
Petrobras Foz do Amazonas Drill Probe
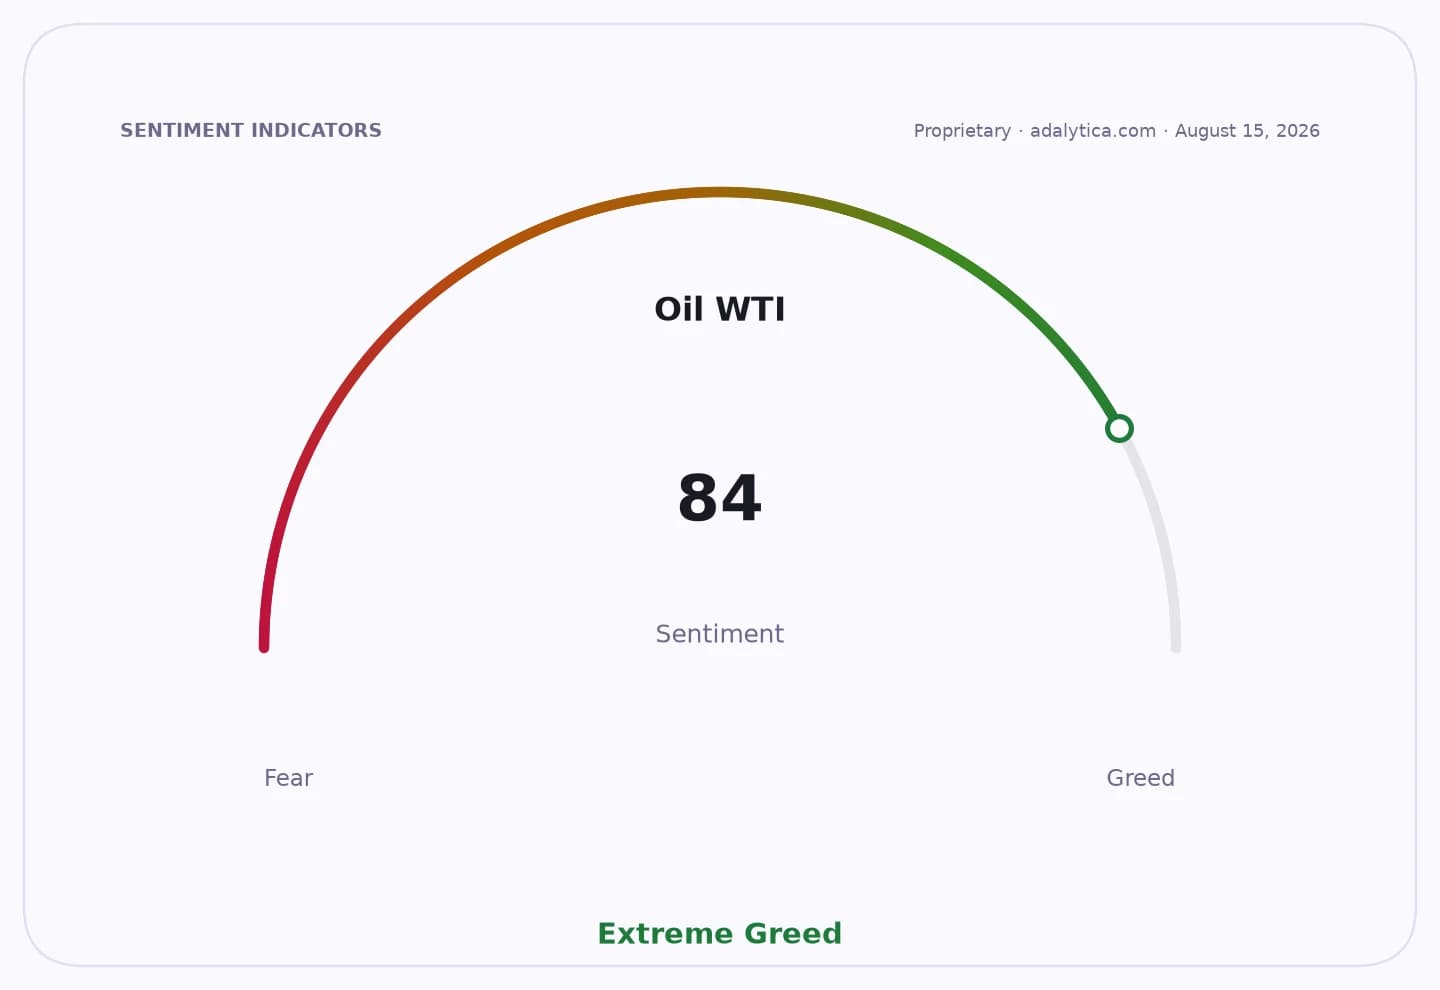
For investors, the stakes are bigger than one well. Foz do Amazonas sits in a geologically promising area off Brazil’s northern coast, and any credible sign of oil or gas would strengthen Petrobras’ case for expanding exploration in a basin that has been delayed by environmental scrutiny and permitting risk. In a market where supply fears are already elevated, even a preliminary success can sharpen the value of long-dated reserves and lift the discount applied to Brazilian upstream assets.
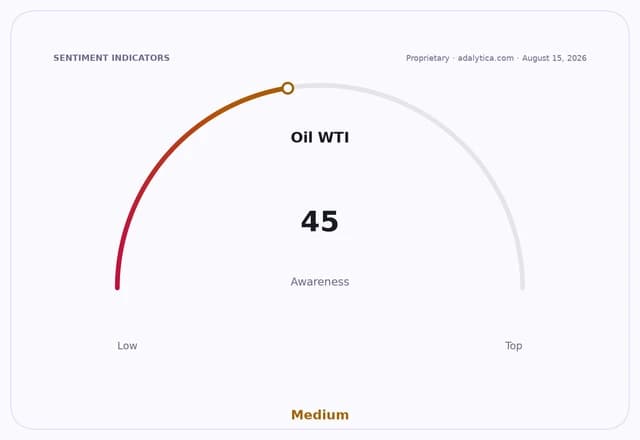
That matters because the oil market is being driven as much by scarcity psychology as by barrels. Brent has been pushed higher by tanker attacks, stalled US-Iran diplomacy and shrinking US inventories, while geopolitical risk remains elevated across key producing regions. Against that backdrop, a Brazilian discovery would not change the market overnight, but it would reinforce the thesis that the next major additions to global supply are likely to come from large, technically complex offshore basins rather than easy onshore growth.
Petrobras shares have already been pricing in a more constructive oil backdrop. The stock has climbed to around $17.88, up sharply from the mid-teens in July, while its 50-day moving average has risen to $17.69, a sign the trend is still intact. But the move also leaves the market vulnerable to disappointment if the Foz do Amazonas campaign fails to deliver. The recent rise in relative strength readings suggests momentum is firm, but it is not an argument to chase blindly if regulatory setbacks emerge.
The bigger opportunity is in the optionality. Petrobras is one of the few large-cap ways to express a bullish view on offshore exploration, global energy security and Brazilian resource development in a single trade. A confirmed find would support not just Petrobras’ reserve life and future production profile, but also service contractors, offshore equipment suppliers and the broader Brazil energy complex. It would also fit neatly into a world where governments are paying up for energy security and domestic supply resilience.
Investors should watch two things next: the regulatory path in Brazil and any follow-up data on the well’s geology. If the probe turns into a viable discovery, the market may have to start valuing Petrobras less like a cash-yielding state oil company and more like a long-cycle reserve growth story. That is the kind of shift that can create outsized returns before consensus catches up.
| Entity | Gains | Losses |
|---|---|---|
| Petrobras | ▲reserve upside | ▼exploration risk |
| Brazil offshore contractors | ▲more drilling demand | ▼project delays |
| Oil bulls | ▲supply narrative support | ▼higher volatility |
| Environmental opponents | ▲little near-term leverage | ▼discovery momentum |




