A new wave of AI tools is moving from text and image generation into game production, promising to compress the time and labor required to build assets such as pixel animations, and that could eventually reshape costs across the interactive entertainment industry.
Take-Two and Nvidia on AI game production
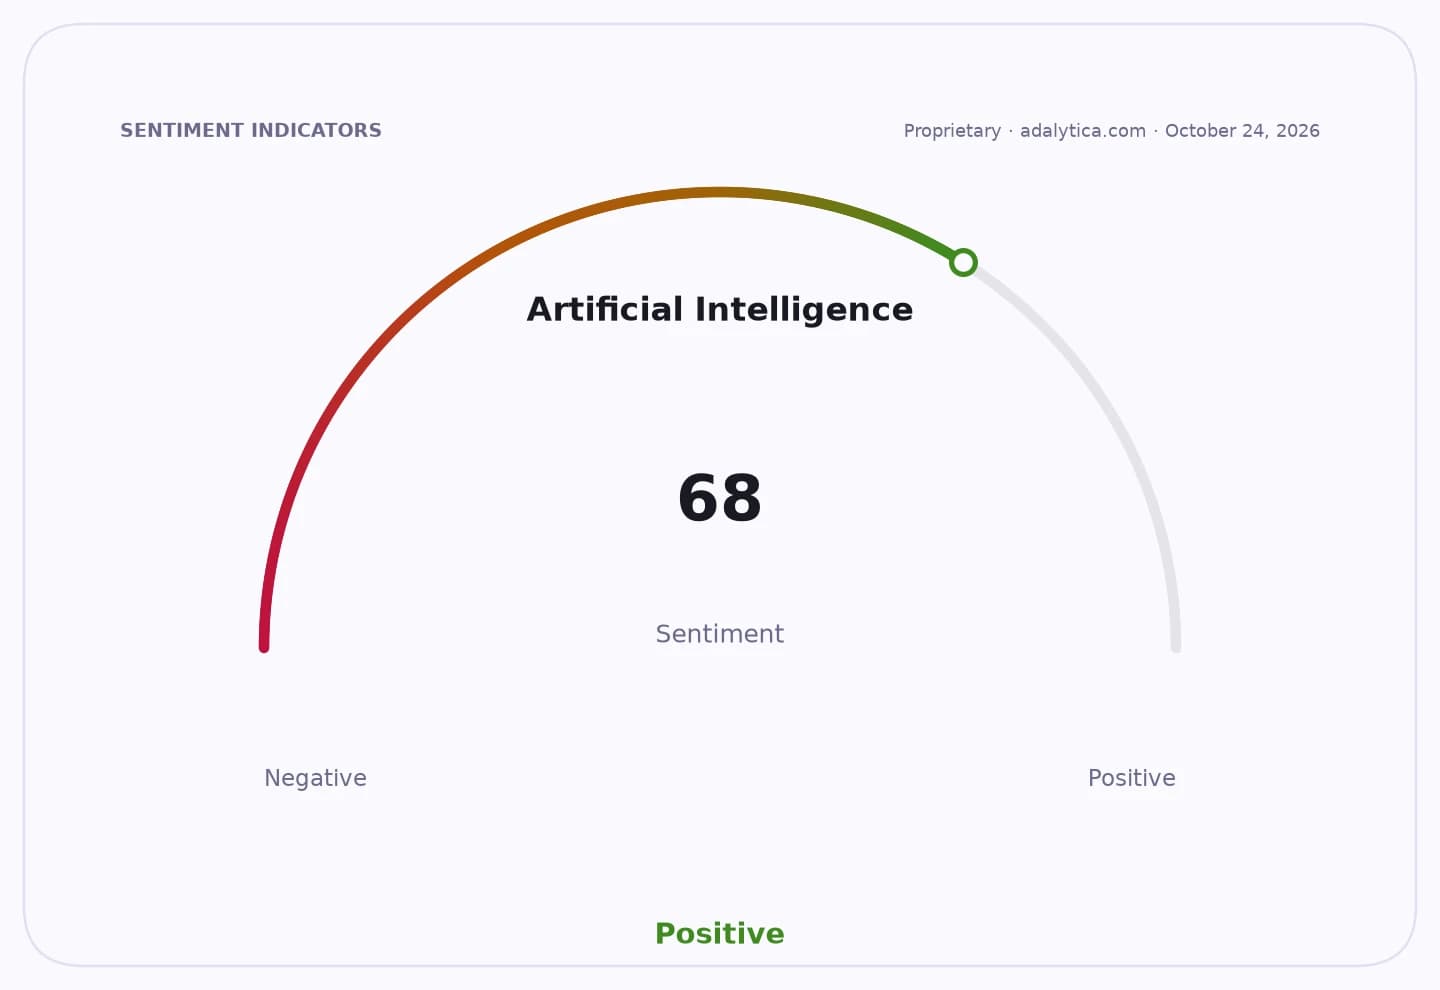
The significance is less about a novelty demo than about the economics of production. Game studios have long faced a trade-off between creative ambition and development expense, especially as budgets rise and release cycles lengthen. If a simple prompt can generate usable animation or video assets in seconds rather than hours, the payoff goes beyond convenience: it could lower outsourcing needs, speed prototyping and let smaller teams produce more polished content with fewer specialists.
That matters for companies such as Take-Two Interactive, whose portfolio spans console, PC and mobile publishing, and for the broader ecosystem of toolmakers and hardware suppliers that profit when creation becomes more compute-intensive. It also gives a second-life argument to the AI infrastructure trade, where Nvidia remains central even after a volatile run in the stock. In the data here, TTWO has fallen back to $203.69 from a recent high near $246.95, while its 50-day moving average sits at $214.98 and the RSI is 50.2, a sign the stock has lost momentum but is not yet deeply oversold. Nvidia, meanwhile, closed at $210.96, below its 50-day average of $222.39 and with an RSI of 22.0, typically a technically stretched reading that reflects sharp recent selling.
For investors, the near-term question is who captures the value. AI-powered creative tools could improve margins for game publishers if they reduce art and animation bottlenecks, but they could also pressure third-party studios, middleware vendors and freelance creators who sell production hours. The bullish case is that productivity gains accelerate content output and widen the pool of viable game concepts, supporting more launches and richer live-service updates. The bearish case is that lower barriers to creation intensify competition, commoditize some art workflows and do little to solve the bigger commercial risks around user acquisition, hit rates and monetization.
The broader narrative is that generative AI is steadily leaving the research lab and entering workflow software with measurable economic consequences. What began as a consumer-facing content tool is becoming a production layer for industries that sell visual output, and gaming is one of the clearest test cases because its costs are so visibly tied to asset creation. If adoption grows, the market may start to value AI not just as a growth theme, but as a margin tool.
| Entity | Gains | Losses |
|---|---|---|
| Game studios | ▲Lower production costs | ▼Legacy workflows |
| AI tool vendors | ▲New enterprise demand | ▼Manual content vendors |
| Nvidia | ▲More AI compute usage | ▼Short-term sentiment volatility |
| Freelance artists | ▲Faster tool access | ▼Some billable work |