Tech Mahindra posted a sharp jump in second-quarter profit and operating income, underscoring that the Indian IT services firm is turning stronger deal momentum into margin expansion just as the market remains wary on enterprise tech spending.
Tech Mahindra Q2 Profit, Deals, and Margin Rise
The company said EBIT rose 40.5% year on year to ₹2,387 crore in the quarter ended Sept. 30, while revenue climbed 15.6% to ₹16,180 crore and profit after tax surged 32.7% to ₹1,586 crore. The board also recommended a 1:1 bonus share issue and declared an interim dividend of ₹15 a share, a clear signal of confidence in cash generation and balance-sheet strength.
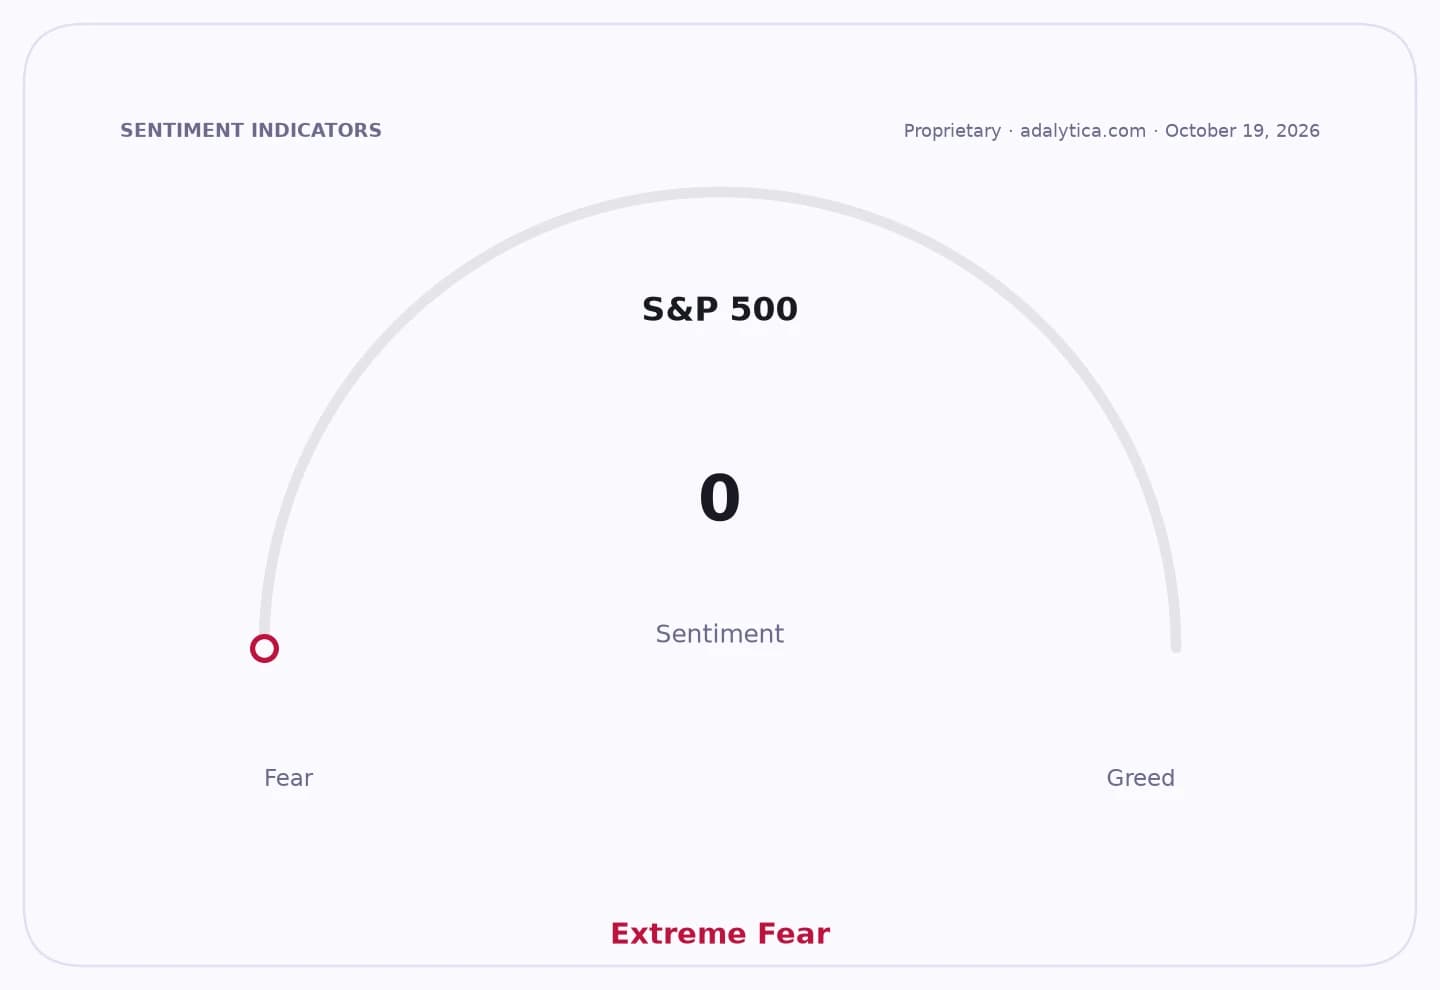
Sentiment IndicatorsⓘProprietary · adalytica.com · October 17, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the bigger story is not just the beat itself but the quality of the growth. Tech Mahindra said new deal wins reached $1.023 billion, up 25.4% from a year earlier, and that it has now topped $1 billion of wins in each of the last four quarters. That matters because order intake is the best leading indicator for future revenue in an industry where clients have been cautious on discretionary IT spending and selective on large transformation programs.
Margin performance is the other crucial piece. EBIT margin rose to 14.8%, up about 260 basis points from a year ago, extending a run of expansion for the twelfth straight quarter, according to management. In a sector where pricing pressure and wage costs can quickly eat into growth, sustained margin improvement suggests Tech Mahindra is benefiting from a better mix of large contracts, productivity gains and tighter execution.
The company is also leaning harder into artificial intelligence as a commercial lever rather than a marketing theme. Management said it is investing in AI to improve productivity and drive innovation, while a long list of new partnerships with Google Cloud, Cisco, ServiceNow, Uniphore, Rezolve AI and others shows the firm is trying to position itself as a platform for enterprise AI adoption. That is important because the next phase of IT services growth is likely to come from production-scale AI deployments, not one-off pilots.
The stock has already started to reflect the improvement. Tech Mahindra shares jumped to ₹1,790 on Oct. 16, after closing at ₹1,650 the prior day and ₹1,575 on Oct. 14, with trading volumes surging alongside the move. The rally leaves investors with a familiar choice: pay up for a turnaround that is finally showing through in earnings, or wait and risk missing the next leg if deal conversion and AI-led demand continue to compound.
Our view is that Tech Mahindra is still being valued too much like a legacy IT outsourcer and not enough like a beneficiary of the AI infrastructure and enterprise transformation cycle. The combination of rising EBIT, repeated billion-dollar deal wins, expanding margins and shareholder-friendly capital returns gives the thesis more than enough support.
If the company can keep converting AI partnerships and telecom, BFSI and logistics wins into recurring revenue, the next catalyst will be not just another earnings beat, but a re-rating of the business model itself.
| Entity | Gains | Losses |
|---|---|---|
| Tech Mahindra | ▲Higher EBIT, larger deal wins | ▼Discounted valuation if re-rated slowly |
| Long-only investors | ▲Bonus issue, dividend, margin expansion | ▼Missed upside if they wait |
| Competitors | ▲Sector proof of AI-led demand | ▼Pressure to defend margins and wins |
| Clients/buyers | ▲Better AI and transformation options | ▼Less bargaining power on premium projects |