Technoprobe is emerging as one of the quieter ways to invest in the AI buildout, and that matters because every new generation of semiconductors needs far more testing before it can ever earn a dollar in a server, phone or car.
Technoprobe raises 2026 revenue and EBITDA guidance
The Italian probe-card specialist sits in a part of the supply chain that investors often overlook: the equipment used to test wafers before chips are cut and assembled. As AI accelerators, high-bandwidth memory and advanced packaging all grow more complex, the number of checks required to validate each chip rises with them. In other words, AI does not just create demand for GPUs and memory — it also increases demand for the tools that make sure those expensive chips actually work.
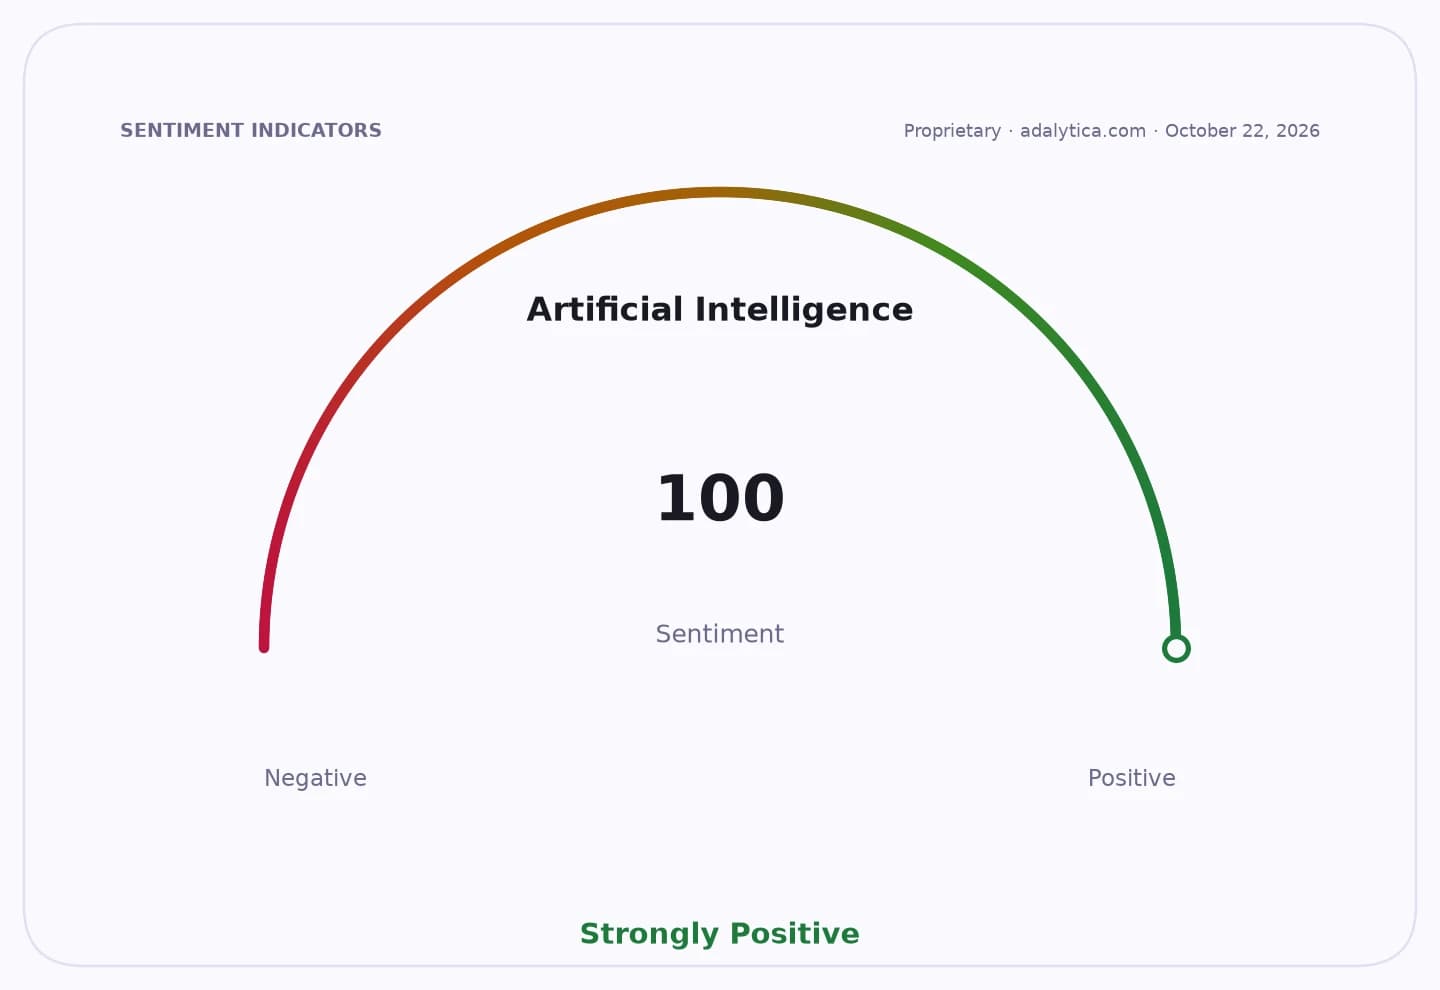
Sentiment IndicatorsⓘProprietary · adalytica.com · October 6, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That is why Technoprobe’s latest numbers matter. For the first half of 2026, the company reported earnings per share of 0.22 euros, above expectations, while revenue climbed 42.4% to 464.1 million euros. EBITDA nearly doubled to 206.2 million euros, lifting the margin to 44.4% from 32.6%. Management also raised its 2026 revenue target to 1.05 billion euros to 1.10 billion euros, up from a prior range of 950 million euros to 1.05 billion euros, and guided for an EBITDA margin of 46% to 48%.
For investors, that combination is attractive because it gives exposure to AI spending without forcing a bet on which chip designer wins the next architecture race. Nvidia, AMD and the memory makers may change product cycles, but they all need to test wafers. That makes Technoprobe more of a structural beneficiary than a one-product story. The company is also investing for the next leg of growth, with 350 million euros earmarked for capacity expansion through early 2027.
This is the kind of business long-term investors should like: a niche supplier with recurring demand, operating leverage and a role that becomes more important as semiconductor complexity rises. The stock can still be vulnerable to cyclical swings, geopolitical tensions and supply-chain regionalization, but the underlying theme is clear. AI spending is not just lifting the headline names — it is creating powerful tailwinds for the picks-and-shovels businesses behind them. For patient investors, Technoprobe is worth watching, especially as the AI supply chain broadens beyond the obvious winners.
| Entity | Gains | Losses |
|---|---|---|
| Technoprobe | ▲Higher test demand | ▼Cyclical chip swings |
| AI chipmakers | ▲Faster adoption | ▼Higher validation costs |
| Semiconductor testers | ▲More complex wafers | ▼Capacity bottlenecks |
| Investors in pure-play AI hardware | ▲Direct growth exposure | ▼Narrower moat than picks-and-shovels |