Taiwan Semiconductor Manufacturing Co. is set to post a sixth straight record quarterly profit on Thursday, but investors are likely to care more about how far the world’s biggest contract chipmaker is willing to push spending to add AI chip capacity in 2027.
TSMC Profit, Capex Guidance Due in Q3 Earnings
LSEG SmartEstimate data from 16 analysts puts third-quarter net income at TWD 746.3 billion, or $23.1 billion, up 65% from a year earlier and above the company’s prior quarterly record of TWD 706.56 billion. TSMC already said last week that third-quarter revenue rose 50% to TWD 1.49 trillion, topping expectations and underscoring how demand tied to AI infrastructure is still outpacing supply.
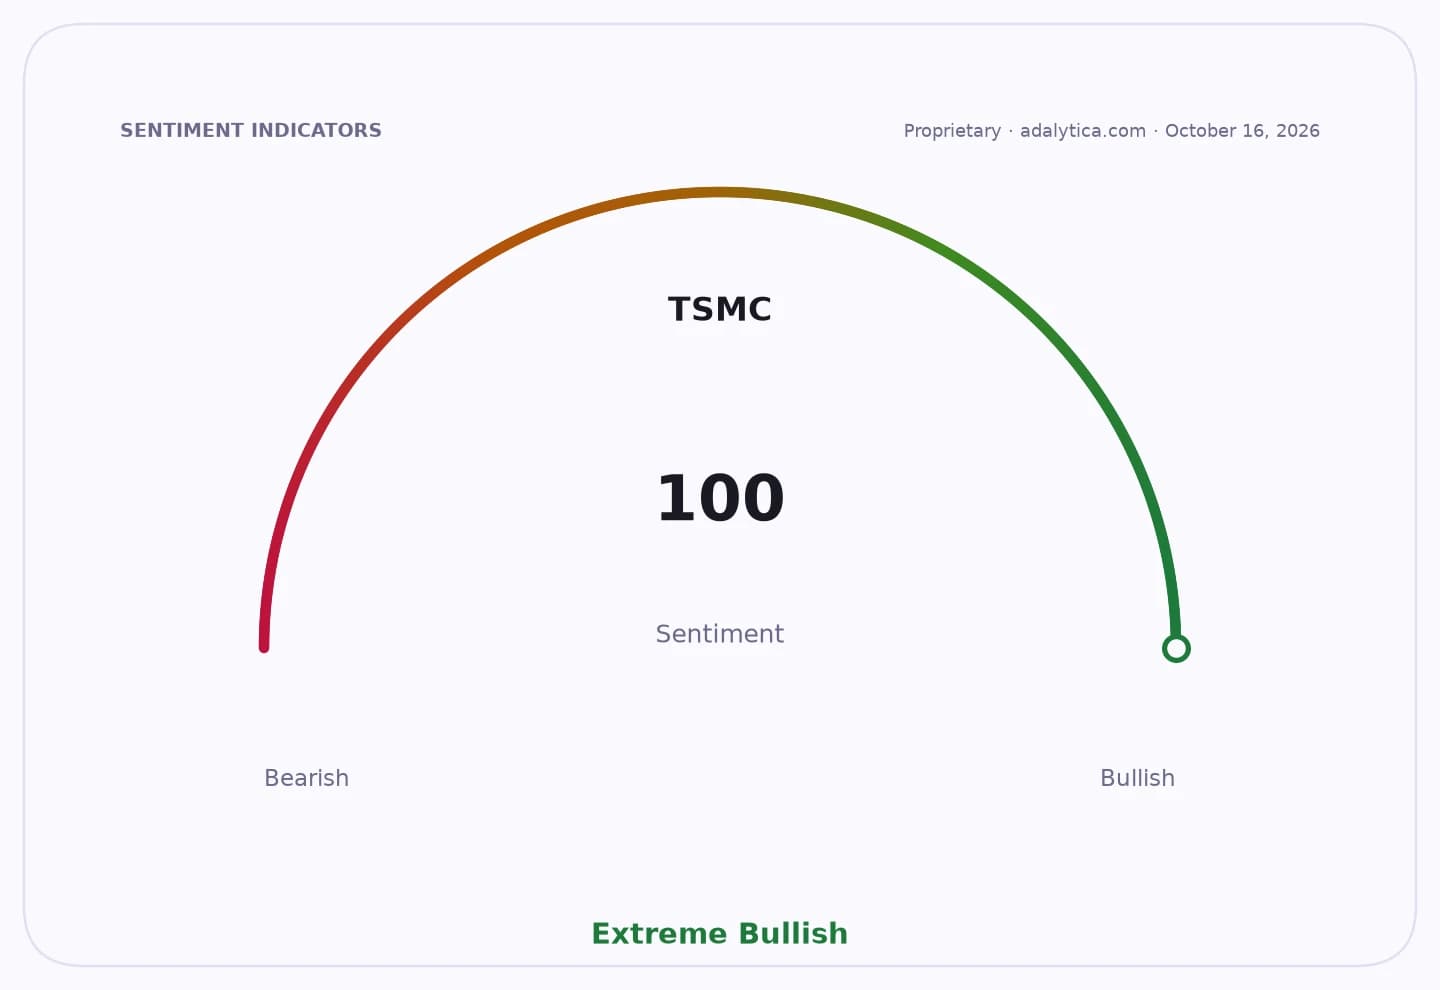
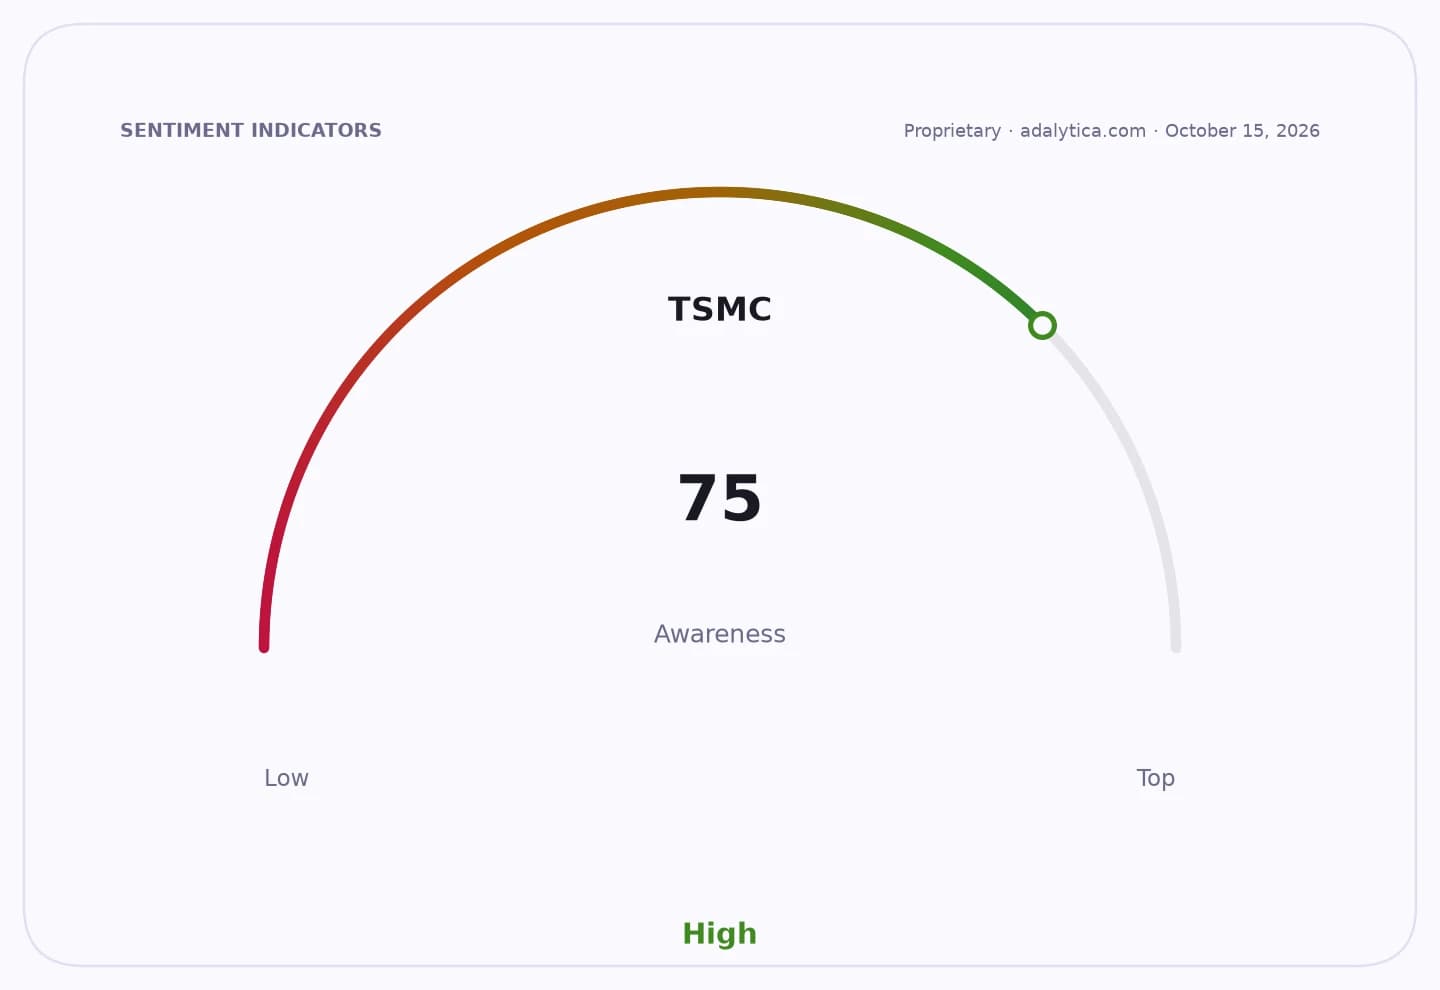
Sentiment IndicatorsⓘProprietary · adalytica.com · October 16, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The real focus is capital expenditure. TSMC lifted its 2026 capex budget in July to $60 billion-$64 billion from $52 billion-$56 billion, and market watchers are looking for any signal on whether that pace extends into 2027. Nicholas Mugalli of World Trade Securities said capex is “the number that matters the most,” arguing the bottleneck in AI is not demand but how fast TSMC and its equipment suppliers can expand output.
That matters for the broader chip cycle because TSMC’s spending plans help set the tone for foundry equipment makers, AI chip designers and hyperscale cloud customers racing to lock in wafer capacity. Reuters cited reports that TSMC may raise wafer prices by 3% to 6% from January 2027, with steeper increases for its most advanced processes, a sign the company still has pricing power as it monetizes the AI buildout.
The earnings report also lands against a softer tone in chip stocks. New York-listed TSMC fell 3.4% on Wednesday to $430 and slipped another 1.73% after hours, while Taipei-listed shares dropped 2.01% to TWD 2,440. Taiwan’s benchmark Taiex lost 3.25% in an Asian chip selloff tied to worries over AI funding.
For investors, the question is whether TSMC can keep translating AI demand into higher profit and sustained cash generation without investors getting spooked by the size of the spending bill. Strong capex would reinforce the case for suppliers to TSMC and for AI chip leaders such as Nvidia and Broadcom, but it would also keep alive concerns that the industry’s boom depends on ever-rising financing needs.
The company’s update should also shed light on whether it can maintain margin discipline as it expands the most advanced manufacturing nodes. With the stock recently under pressure and technical indicators showing the NYSE-listed shares below their 50-day moving average, traders will be parsing Thursday’s call for guidance on investment, pricing and demand into 2027.
| Entity | Gains | Losses |
|---|---|---|
| TSMC | ▲Pricing power, record profit | ▼Higher capex burden |
| AI chip customers | ▲More foundry capacity | ▼Potential wafer price hikes |
| ASML and chip tools suppliers | ▲More equipment orders | ▼Spending delays if TSMC turns cautious |
| Shorts / cautious chip investors | ▲Lower share prices | ▼Continued AI capex enthusiasm |