TSMC is weighing a bigger U.S. manufacturing push in Texas just as surging artificial-intelligence demand keeps the chipmaker at the center of the global AI buildout.
TSMC Evaluates Texas Expansion After Record Quarter
That matters because Taiwan Semiconductor Manufacturing is not just any supplier. It makes more than 90% of the world’s most advanced chips, and its capacity decisions ripple through Nvidia, Apple and the rest of the AI supply chain. If TSMC adds production in Texas, it would deepen the industry’s shift toward U.S.-based semiconductor capacity at a moment when customers are desperate for more chips and governments are pushing for more domestic supply.
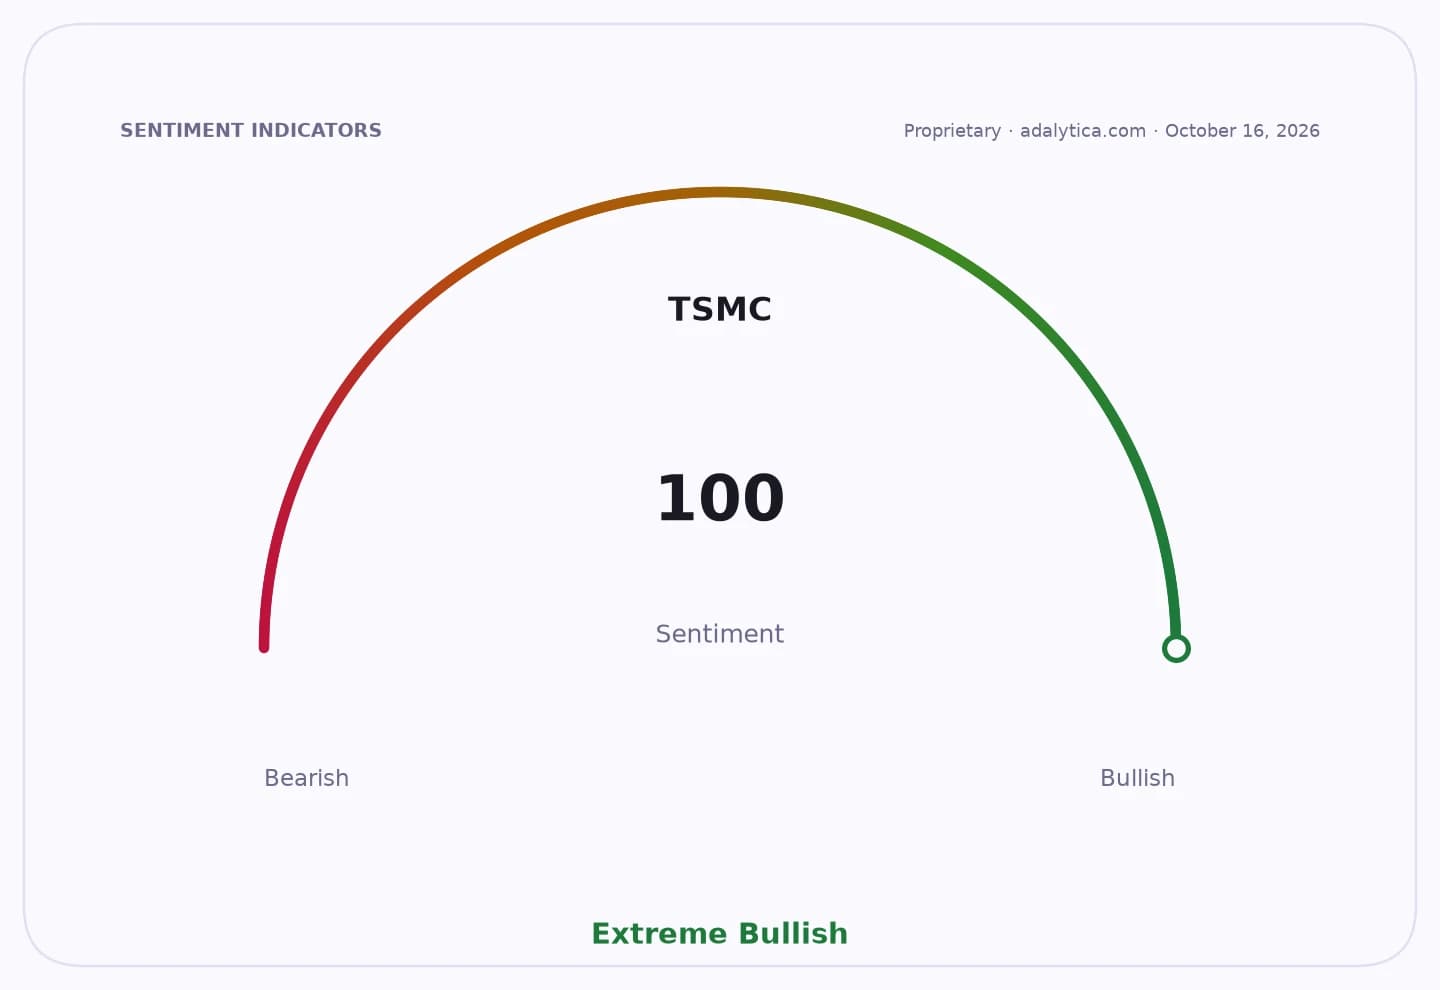
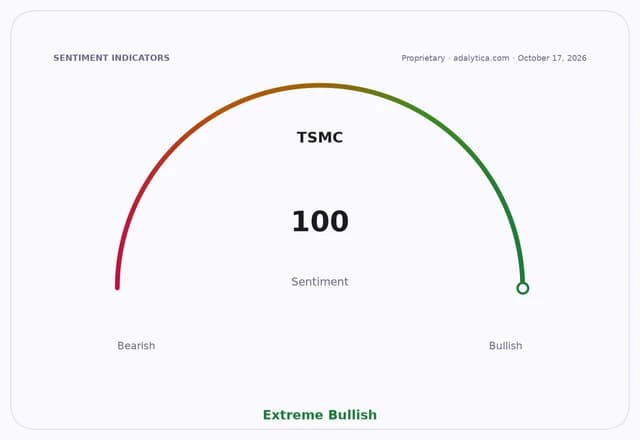
Sentiment IndicatorsⓘProprietary · adalytica.com · October 17, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The company said it is evaluating Texas as an option after another record quarter. Net profit jumped 69% from a year earlier to 763.1 billion New Taiwan dollars, or nearly $24 billion, while revenue rose 51% to NT$1.49 trillion. For investors, that is the key takeaway: AI is still translating into real earnings power, not just optimistic spending plans.
Chief Executive C.C. Wei said demand remains “far above” TSMC’s current ability to supply, and the company is working to close the gap. That shortage is what gives TSMC pricing power and keeps its factories running near full stretch. It also explains why the company is raising capital spending to as much as $64 billion this year, up from an earlier range of $52 billion to $56 billion, and why it expects spending from 2026 through 2028 to be even higher than in the last three years.
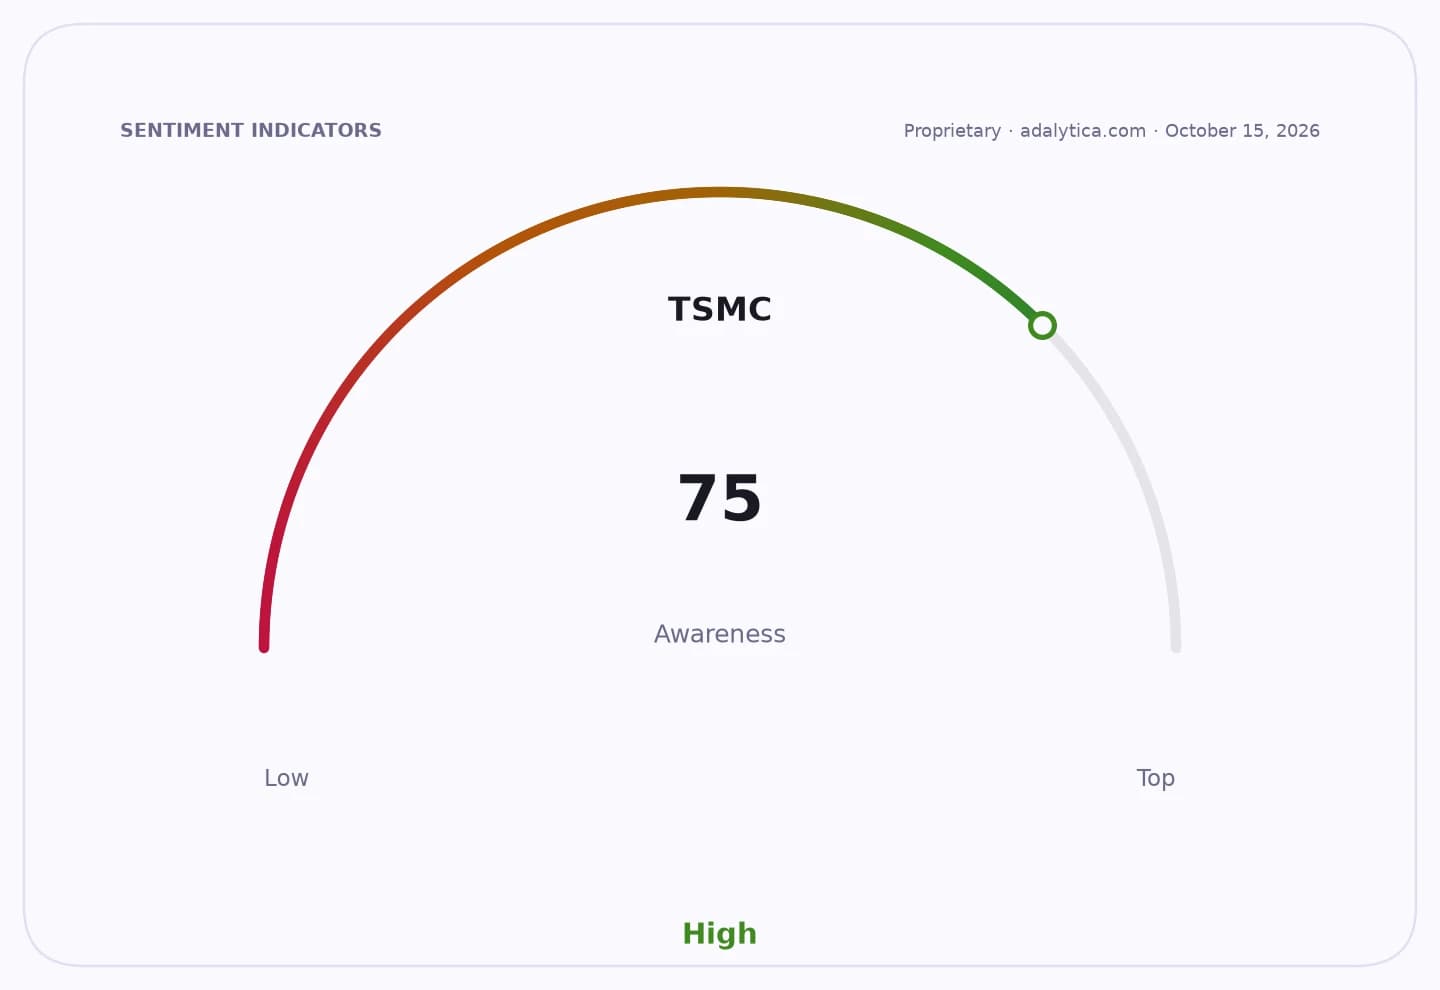
TSMC — 30-day sentimentadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
Texas is now part of that story. Wei said TSMC has sent teams to evaluate the state, and the company is in talks over Elon Musk’s proposed “Terafab” complex. Musk has said he would build and run the fab himself, while TSMC says any plant in Texas must be run by TSMC. However that negotiation ends, the fact that TSMC is exploring another U.S. footprint underscores how much leverage the AI boom has given the chipmaker — and how much pressure it faces to keep up.
For long-term investors, that is exactly why TSMC remains one of the most important stocks in the semiconductor chain. The company is turning secular AI demand into record profit, expanding its manufacturing footprint, and reinforcing its role as the indispensable picks-and-shovels supplier behind the world’s most valuable tech platforms. The stock may wobble with the market, but the business remains tied to one of the most powerful compounding trends in technology. Worth watching, and for patient investors, still one to hold for the long term.
| Entity | Gains | Losses |
|---|---|---|
| TSMC | ▲More U.S. capacity, stronger moat | ▼Higher capex burden |
| Nvidia and Apple | ▲More chip supply | ▼Continued dependence on TSMC |
| U.S. semiconductor policy | ▲More domestic production | ▼Less reliance on Taiwan |
| Intel | ▲Foundry opportunity | ▼TSMC expands competitive reach |