Britain’s public finances just got more expensive to defend, with record debt interest costs pushing government borrowing up to £17 billion in October and highlighting how stubbornly high rates are feeding straight through to the Exchequer.
UK public finances face record debt interest costs
The Office for National Statistics said debt interest payments jumped by £11.2 billion last month, the highest October reading on record and £2.8 billion more than a year earlier. That made borrowing 5.2% higher than a year ago, even though the overall £17 billion print was fractionally below the £18 billion economists had expected.
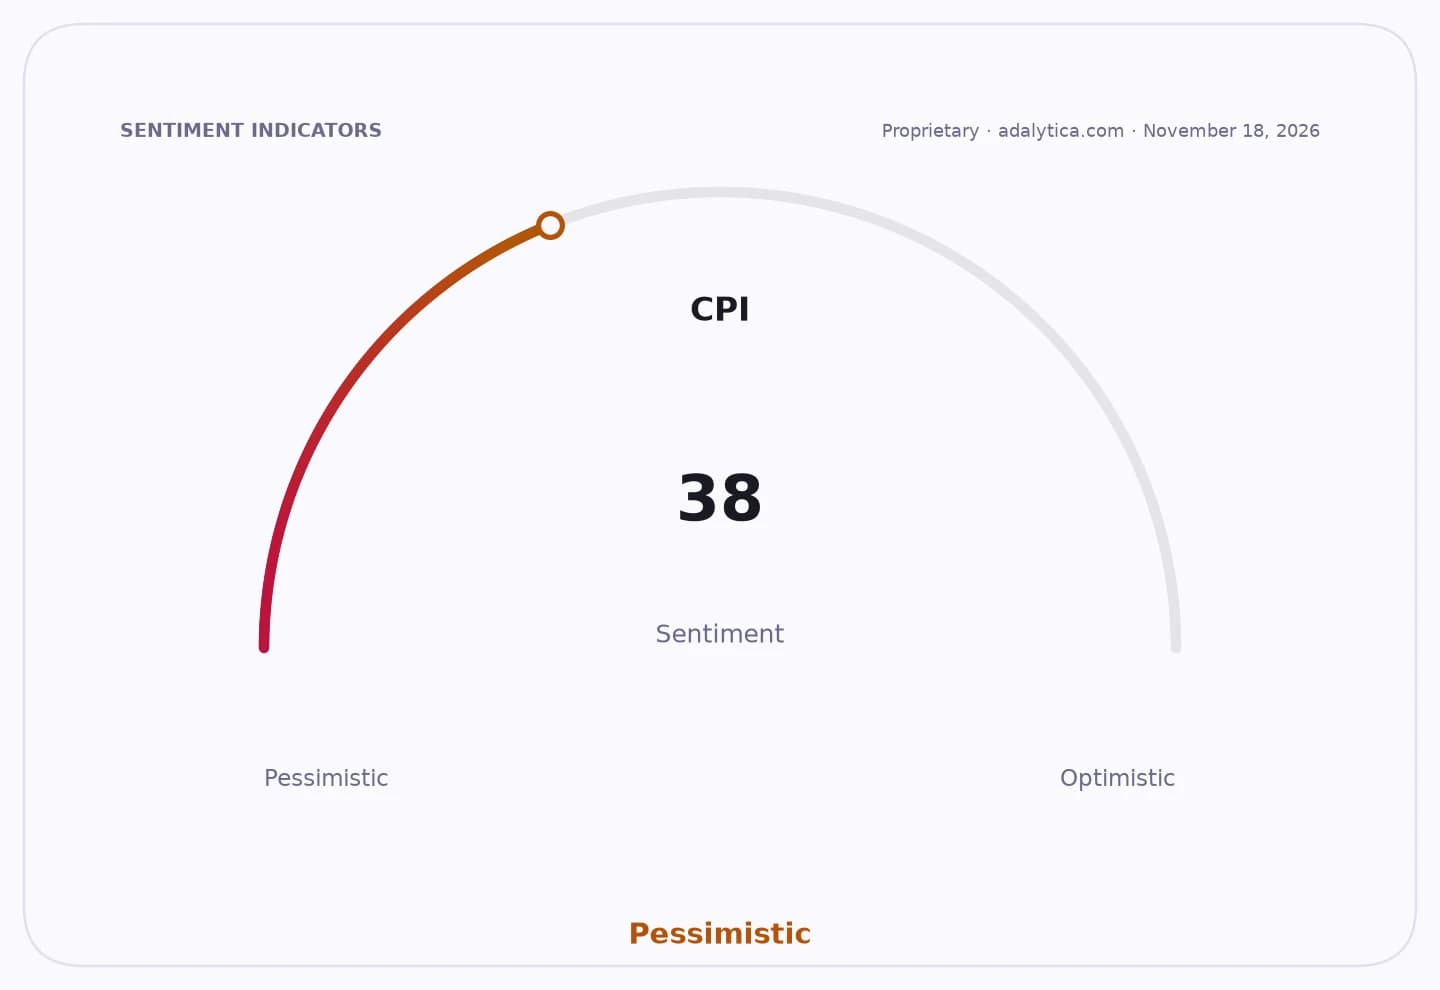
Sentiment Indicators
The economic significance is straightforward: when the state pays more to service its debt, it has less room to fund services, invest or cut taxes without widening the fiscal gap. That matters now because Chancellor John Healey is trying to hold the public finances together at a time when growth remains sluggish and rates are still biting. The ONS said monthly debt interest has topped £10 billion only nine times since records began in 1997, a reminder that the current burden is still unusually heavy even after the Bank of England has started easing policy from its peak.
For investors, the key message is that UK fiscal vulnerability has not gone away. Bigger debt-servicing bills increase the odds of tighter spending plans, higher taxes or both, and that combination is usually unwelcome for domestically focused equities, especially sectors tied to consumer demand and public investment. It also keeps pressure on gilts because markets will continue to test how much borrowing the Treasury can absorb before fiscal credibility becomes a bigger issue.
There is one important offset. Borrowing in the financial year to date still stands at £111.3 billion, down 6.1% from the same period last year and slightly better than the consensus path. Receipts, particularly income-related taxes, have been growing faster than spending, which gives the government some breathing room. But the October number shows how quickly that cushion can be eroded if debt costs keep climbing.
The broader narrative is that the UK is trying to manage a classic late-cycle squeeze: sticky financing costs, weak growth and a budget that is increasingly hostage to rate movements. The market underestimates how powerful that combination can be, not just for fiscal policy but for asset prices that depend on a stable gilt curve and a credible medium-term budget story.
The trade implication is clear: stay selective in UK risk, watch gilts for signs of renewed term-premium pressure, and look for beneficiaries of any renewed fiscal tightening, including defensive cash-generative companies and global exporters less exposed to the domestic tax and spending cycle. If debt interest keeps outrunning growth, the next move in UK markets will be driven less by politics than by the cost of money itself.
| Entity | Gains | Losses |
|---|---|---|
| Gilt investors | ▲Higher yields, better entry points | ▼Capital volatility |
| HM Treasury | ▲Slightly better-than-expected headline borrowing | ▼Rising debt-service burden |
| UK domestically focused stocks | ▲None | ▼Tax/spending pressure |
| Defensive exporters | ▲Relative safe haven | ▼Little direct hit but wider UK risk premium |