The dollar is holding firm near 102 against a broad basket of peers as investors price a still-resilient U.S. rate advantage ahead of the Federal Reserve’s next decision, with Treasury yields staying elevated enough to keep the greenback supported.
U.S. dollar holds near 102 before Fed decision
That matters because the currency’s move is being driven less by day-to-day risk appetite and more by the outlook for U.S. interest rates relative to the rest of the world. With the 10-year Treasury yield at 4.99% and the fed funds rate recently at 3.75%, the market still sees the U.S. offering a meaningful carry premium, helping the dollar outperform even as some traders trim near-term bets after a sharp run-up.
Sentiment Indicators
The dollar index, which has climbed above its 50-day average of 100.75 and its 200-day average of 99.62, closed at 101.97 on Oct. 29 after touching 102.32 earlier in the week. The move comes after a steady October advance, and technical readings show momentum has cooled from overbought levels, with RSI easing to 46.6, but the broader trend remains constructive.
Against that backdrop, the euro has slipped to 103.15 on FXE, while UUP, the Invesco DB U.S. Dollar Index Bullish Fund, is trading at 29.02, near its recent highs and still above both its 50-day and 200-day moving averages. That tells investors the dollar’s strength is not just a single-session move but part of a broader positioning shift tied to expectations that U.S. policy will stay restrictive longer than other major central banks’.
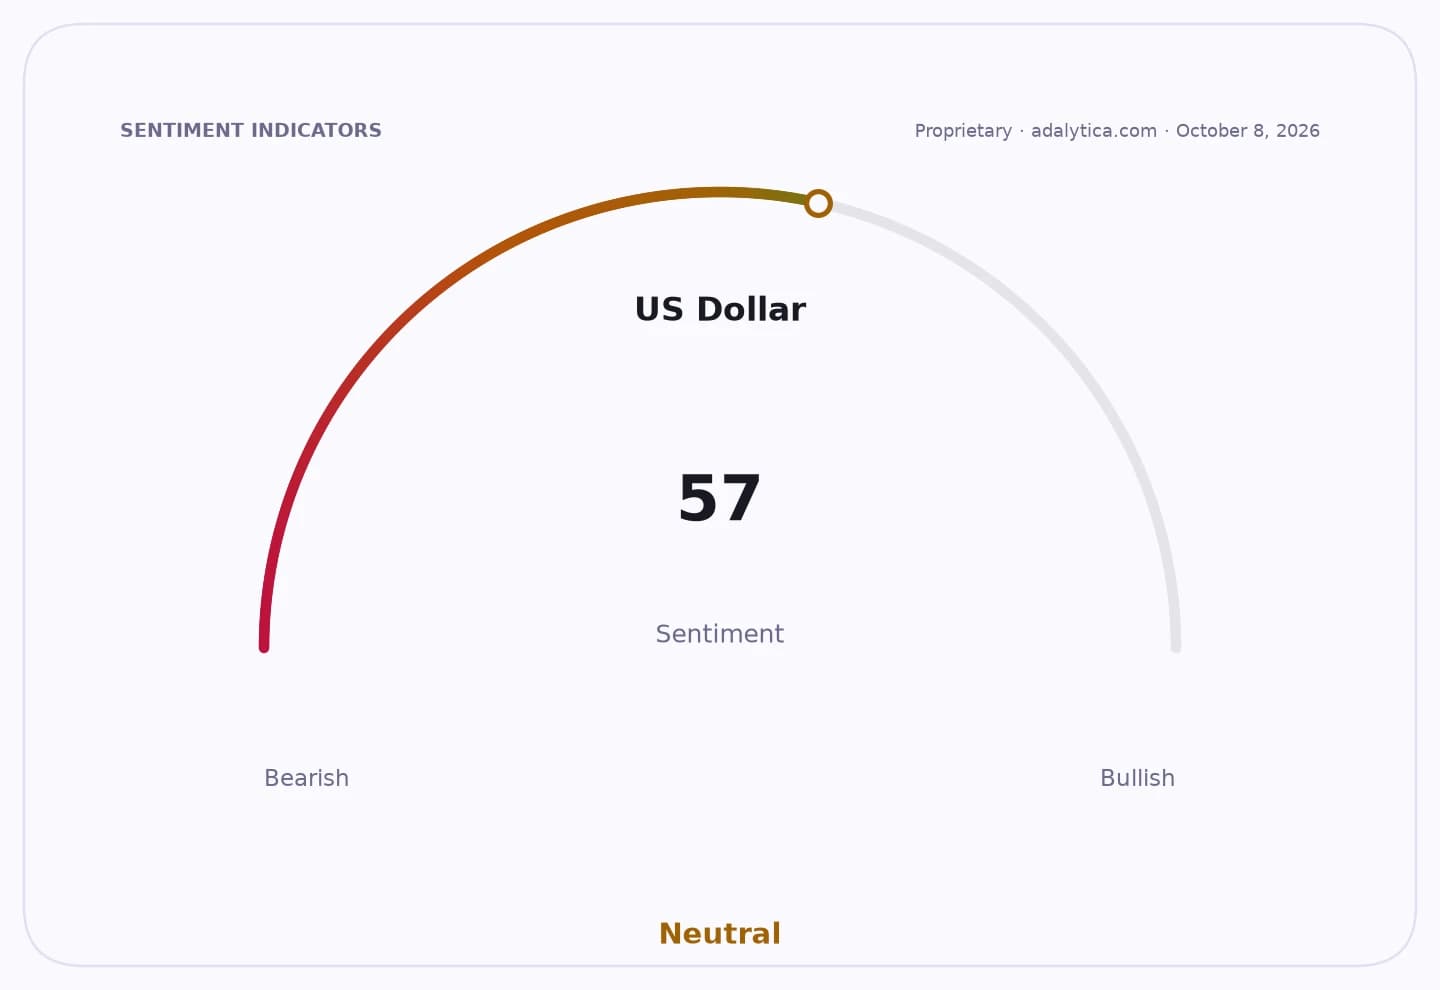
Adalytica’s US Dollar Trade Signals snapshot shows sentiment at 32, neutral, but awareness at 100, a sign the trade is fully on investors’ radar even after a 30-day rise of 31%. FX volatility signals remain subdued, suggesting the market is leaning into the dollar’s strength without yet pricing a disorderly break.
The near-term catalyst is the Fed. If policymakers reinforce a slower easing path or signal concern about sticky inflation, the dollar could extend higher; a more dovish tone would be the clearest risk to the greenback’s current momentum.
| Entity | Gains | Losses |
|---|---|---|
| U.S. dollar | ▲Higher yield support | ▼Importers and multinational earnings |
| U.S. Treasury market | ▲Demand from rate expectations | ▼Bond prices if yields stay elevated |
| Euro and other majors | ▲— | ▼Pressure from wider rate gap |
| Dollar bulls | ▲Carry and momentum | ▼Shorts if Fed stays hawkish |