The U.S. is accelerating its robotics buildout, but the bigger story is that the country still lacks the industrial base to turn AI leadership into large-scale robot production and deployment. That gap is now shaping policy, supply chains and where investors are placing bets.
U.S. Robotics Buildout Lags China in Industrial Scale
America installed about 38,400 industrial robots in 2025, up 12% from a year earlier and second only to China, according to the International Federation of Robotics. China installed 354,200 units, or 59% of global demand, roughly nine times the U.S. total, underscoring how far the world’s largest economy still trails in scale even as it leads in AI software and control systems.
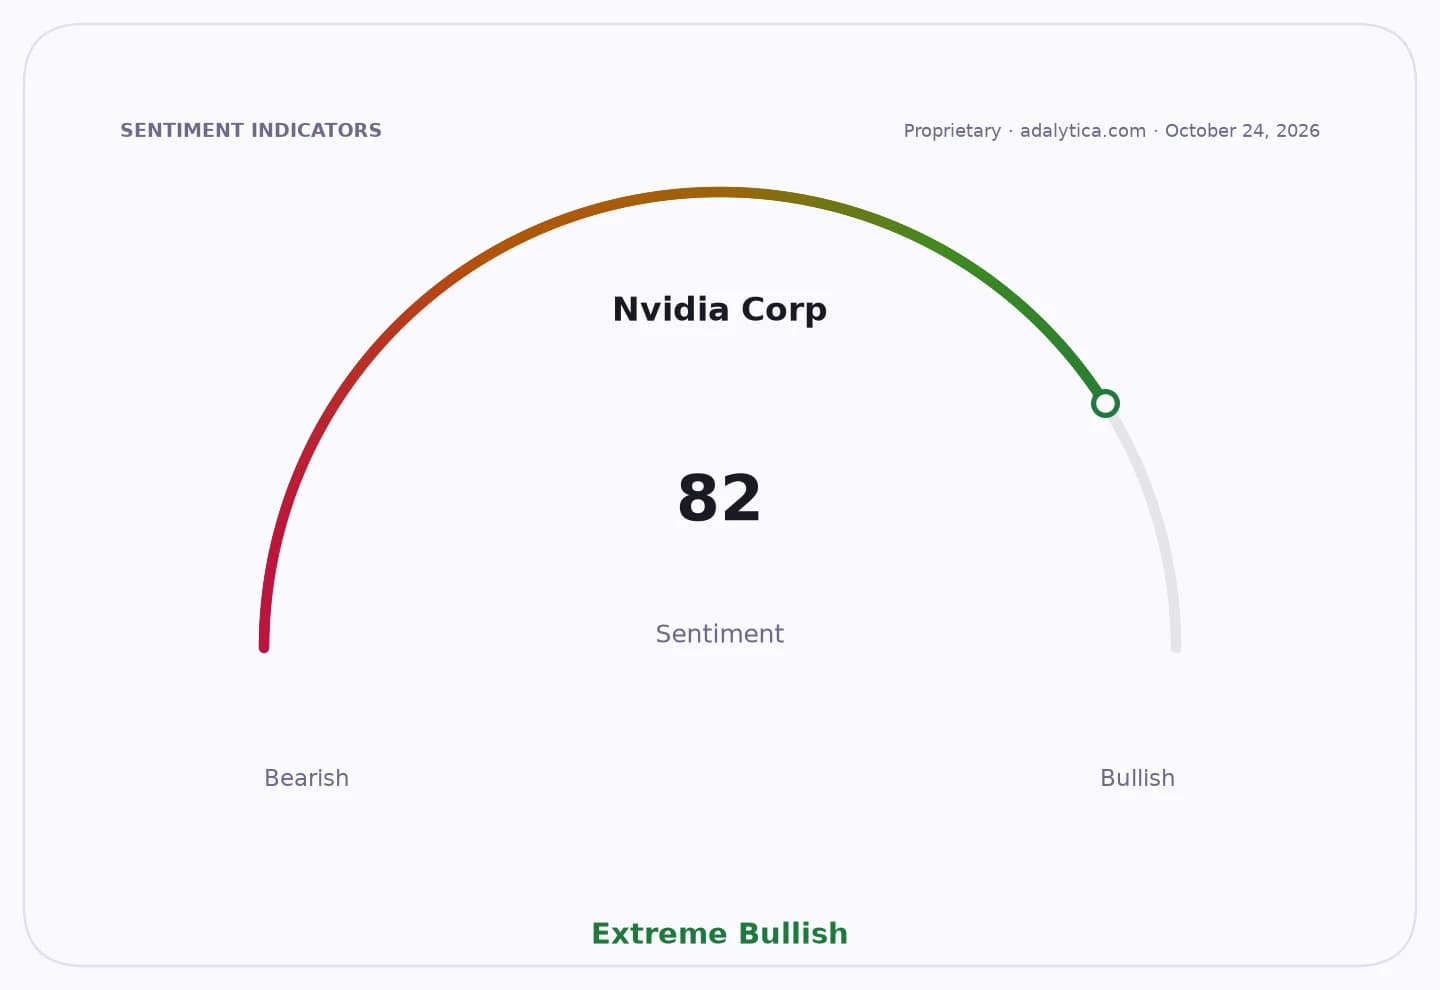
Sentiment Indicators
The mismatch matters economically because robotics is shifting from a technology race to an industrial capacity race. The U.S. has strengths in AI, simulation and control software, but it remains dependent on Japanese and European suppliers for robots and components, limiting how quickly design wins can become factory-floor deployments and productivity gains.
Automotive remains the biggest U.S. customer, with 13,500 robot installations last year, or 35% of the total. Metal fabrication, machinery, food, warehousing and logistics are also adopting more automation as manufacturers seek to offset labor shortages, raise throughput and stabilize margins.
That transition is why humanoid robots and AI-driven systems are drawing so much attention. The next phase is less about pre-programmed machines and more about systems that can perceive their environment, learn and adapt with AI support, a shift that could broaden robotics beyond auto plants into logistics, food processing and healthcare. Nvidia’s GR00T platform is one example of the direction the industry is taking.
Investors are watching because the winners may be less about flashy prototypes and more about the infrastructure around deployment. Companies that supply industrial automation, testing, sensors, integration and maintenance stand to benefit if the U.S. scales real production, while manufacturers that cannot convert AI capability into repeatable factory output risk being left behind.
That is also where policy comes in. A preliminary report released Oct. 14, 2026 by the U.S. National Security Commission on Emerging Biotechnology and Robotics called for closing the gap between AI strength and industrial application through automation incentives, public-sector early adoption, research commercialization, workforce training and stronger safety standards.
The market implication is that robotics is becoming a broad industrial theme rather than a narrow AI side bet. Automation could lift productivity in manufacturing and logistics, but it also increases demand for systems integrators, robotics engineers, technicians and maintenance crews, creating new labor needs even as it displaces some routine tasks.
For Vietnam and other manufacturing economies, the message is similar: the competitive edge will come not from building humanoid robots first, but from adopting automation where it lifts output, quality and local value added. The U.S. lesson is that robotics leadership depends on supply chains, scale and execution as much as software.
The next catalyst is whether U.S. firms can turn AI tools into commercially reliable robots at lower cost, while policymakers and manufacturers build the industrial capacity to support mass deployment.
| Entity | Gains | Losses |
|---|---|---|
| U.S. industrial automation firms | ▲More deployment demand | ▼Prototypes without scale |
| Nvidia and AI platform providers | ▲More robotics use cases | ▼Slower commercialization |
| Japanese and European suppliers | ▲Component export demand | ▼U.S. import substitution over time |
| Labor-intensive manufacturers | ▲Higher productivity | ▼Higher automation pressure |