USD/JPY eased modestly on Wednesday, but the bigger trade remains higher: markets are still leaning toward a stronger dollar and a weaker yen heading into U.S. inflation data that could reinforce Federal Reserve tightening bets.
USD/JPY Holds Near 158 Ahead of U.S. CPI
That matters because the pair is being driven less by day-to-day currency noise than by the widening policy gap between Washington and Tokyo. With traders pricing about a 22% chance of a Fed rate hike this month and an 88% probability of another move in December, the dollar keeps a structural advantage as long as U.S. growth and inflation stay firm enough to keep Treasury yields elevated.
New York Fed President John Williams has already signaled the central bank may need to raise rates once more this year, while Fed Governor Christopher Waller argued the recent rise in bond yields reflects stronger growth rather than a dangerous pickup in inflation expectations. That combination is supporting the greenback even as investors wait for September CPI, followed by PPI and retail sales later in the week.
For investors, the key is that U.S. yields remain the main engine behind the dollar’s strength. The 10-year Treasury yield has hovered around 5.2%, and the 2-year near 4.8%, levels that keep the carry trade attractive versus the yen. That is why the current dip in USD/JPY looks more like a pause than a reversal. The pair has nearby resistance at 158.14, with a break above opening a move toward 159.20, according to technical levels in the market. Support sits around 157.80.
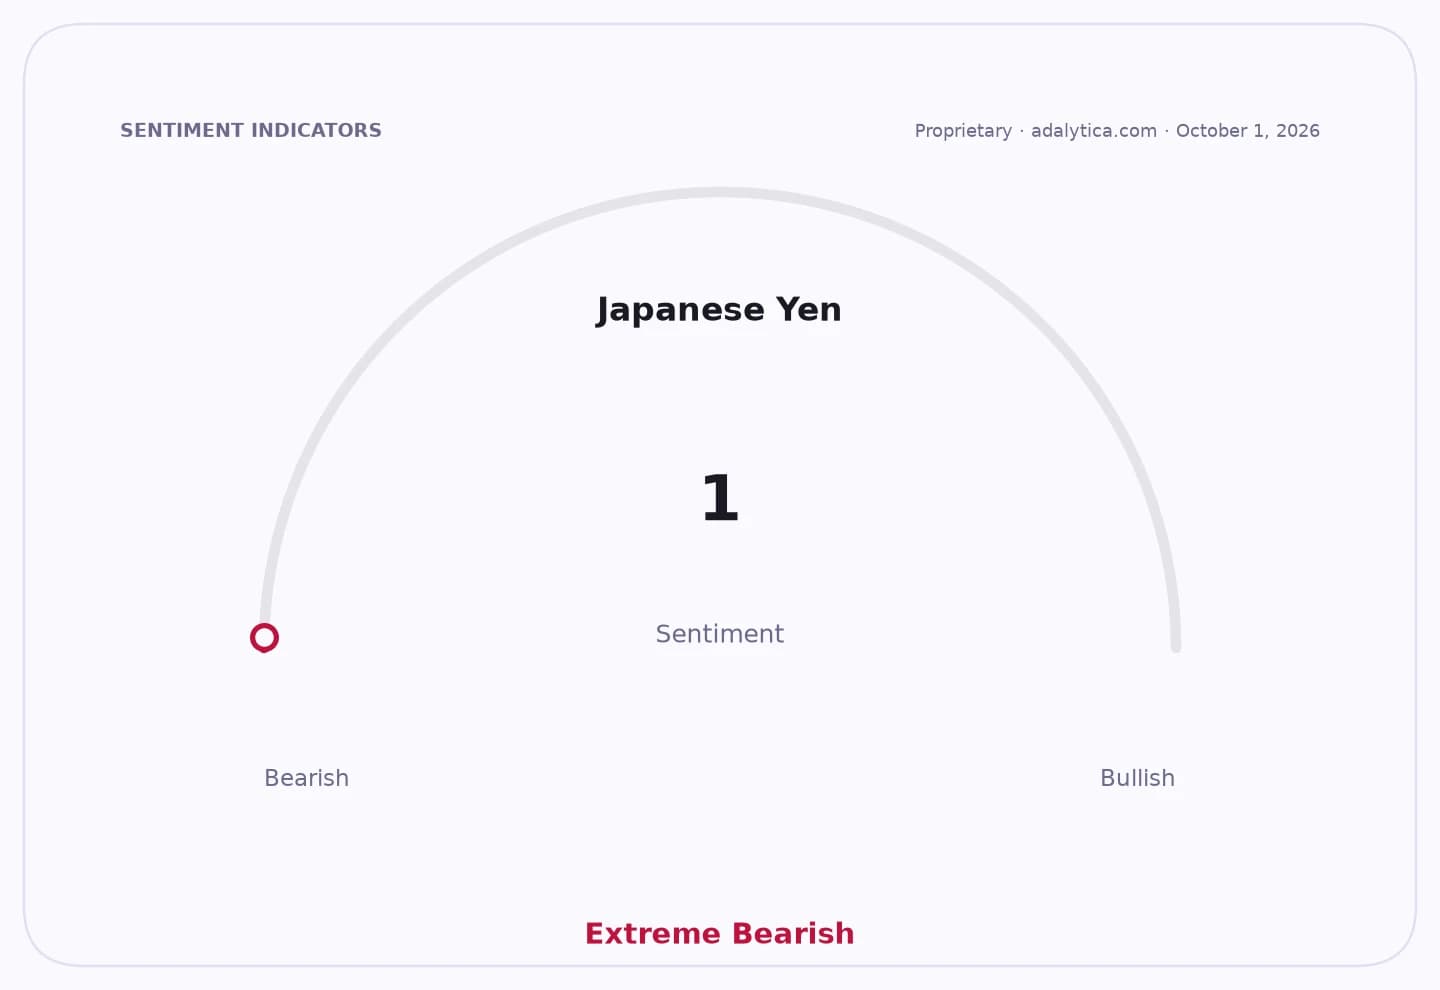
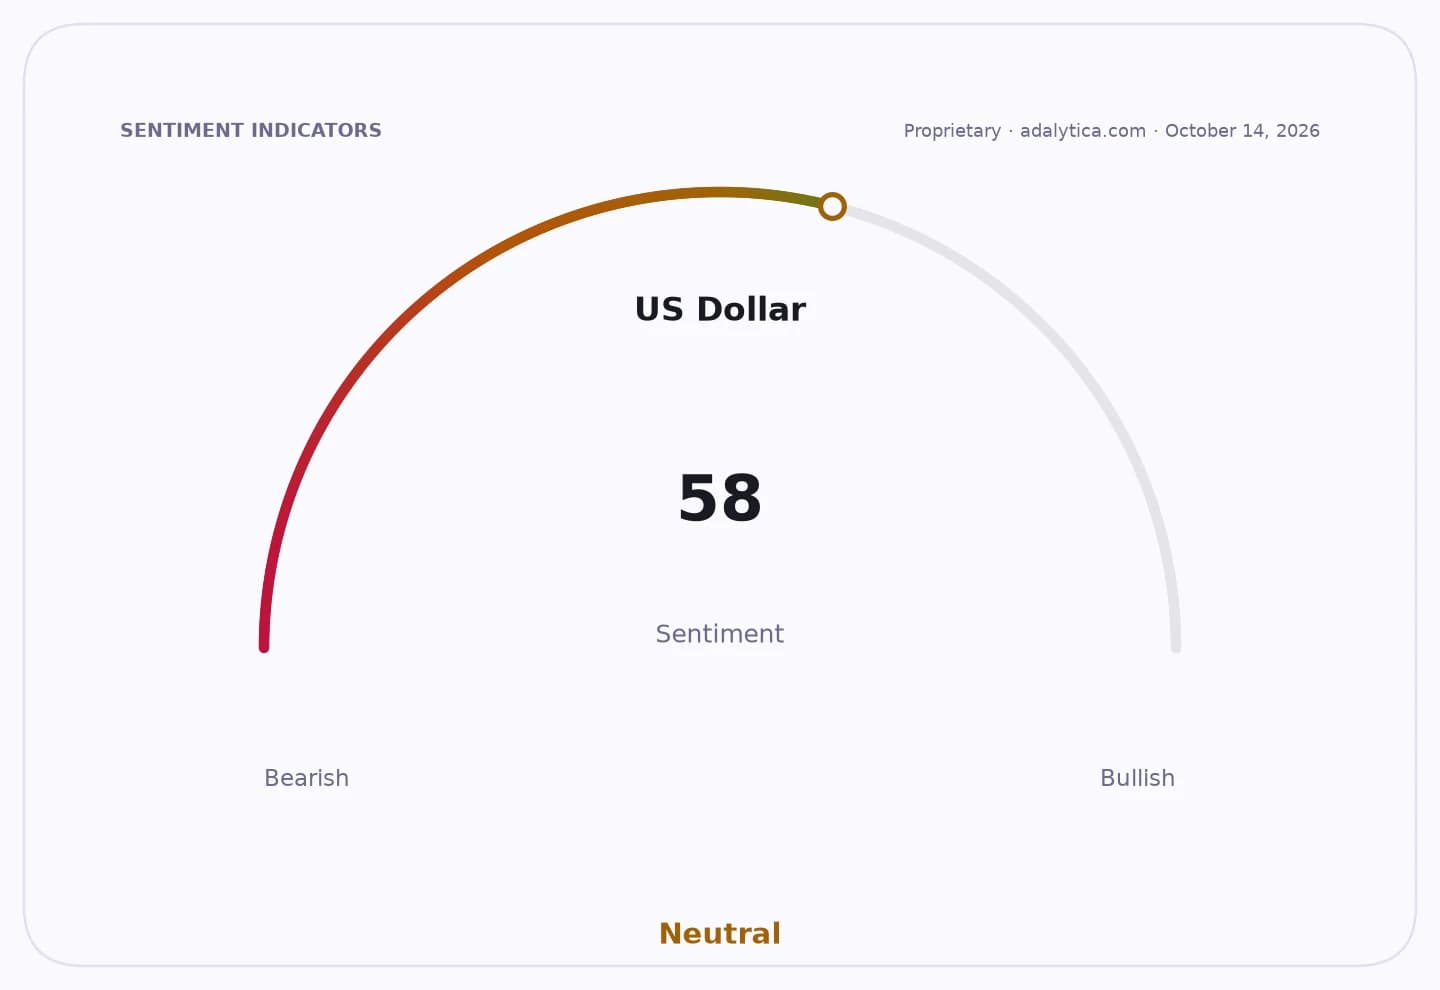
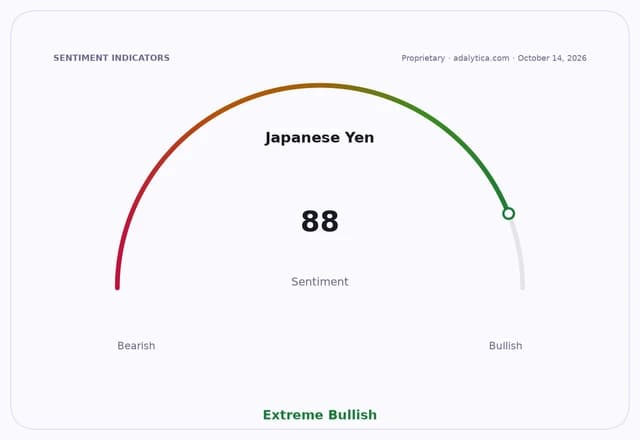
The yen’s weakness is also visible in market positioning. Adalytica’s Japanese yen trade signals show sentiment at 88, an extreme-greed reading, even as awareness remains at zero, underscoring how one-sided the market has become around further yen softness. By contrast, the dollar’s sentiment gauge is neutral, suggesting room for renewed upside if CPI comes in hot enough to revive talk of another Fed hike.
The investment case here is straightforward: the market underestimates how persistent U.S. rate support can be when inflation remains sticky and growth resilient. That keeps pressure on the Bank of Japan to maintain ultra-easy policy for longer, even as yen weakness raises the risk of official intervention. If CPI lands above expectations, the next leg in USD/JPY could come fast.
For traders, this is still a buy-the-dip market around 158, with the real catalyst coming from U.S. data and any further confirmation that the Fed is not done yet. The pair’s path of least resistance remains higher until the policy gap starts to close.
| Entity | Gains | Losses |
|---|---|---|
| U.S. dollar | ▲Higher yield support | ▼Any soft CPI print |
| Japanese yen | ▲Intervention risk support | ▼Carry-trade pressure |
| Fed hawks | ▲Stronger case for more tightening | ▼Easier financial conditions |
| USD/JPY bulls | ▲Breakout potential above 158.14 | ▼Failed resistance move |