The dollar’s surge against the zloty has already pushed USD/PLN above the end-2026 forecasts of every major bank in the latest round of estimates, and traders are now asking whether 3.98 is the next stop.
USD/PLN Tops Bank Forecasts as Dollar Rallies
That matters because foreign exchange is not just a chart to watch — it feeds directly into import costs, inflation, corporate margins and the returns global investors earn when they hold Polish assets. On the NBP’s October 19 fixing, USD/PLN stood at 3.8974 zł, or 2.83% above the median bank forecast of 3.79 zł for year-end, while even Credit Agricole’s most dollar-friendly call of 3.82 zł has already been overtaken by the market.
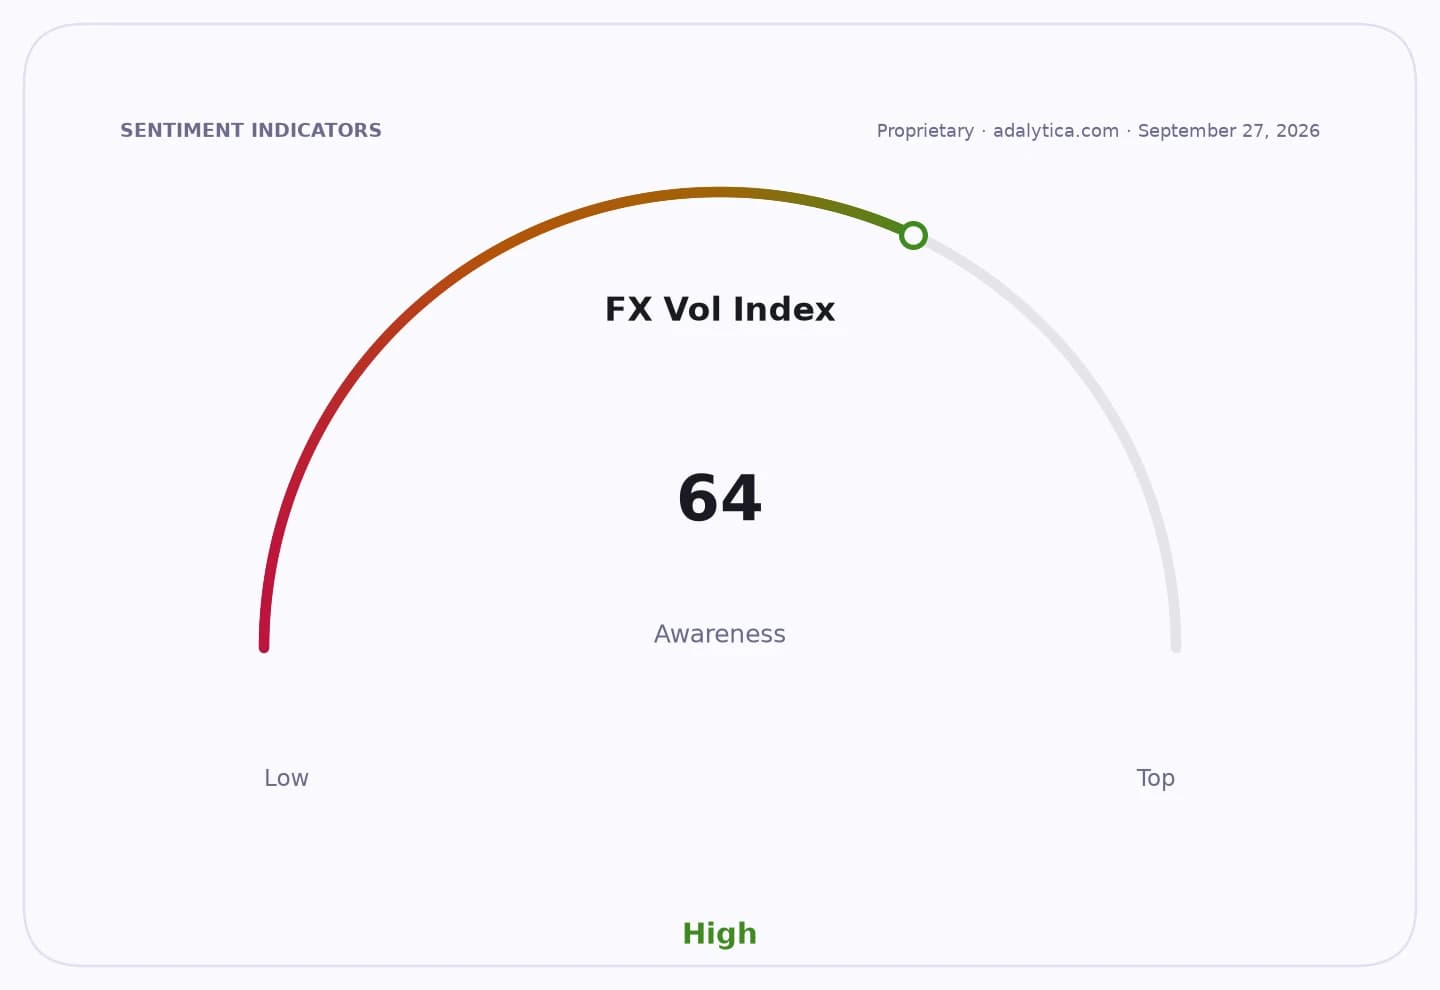
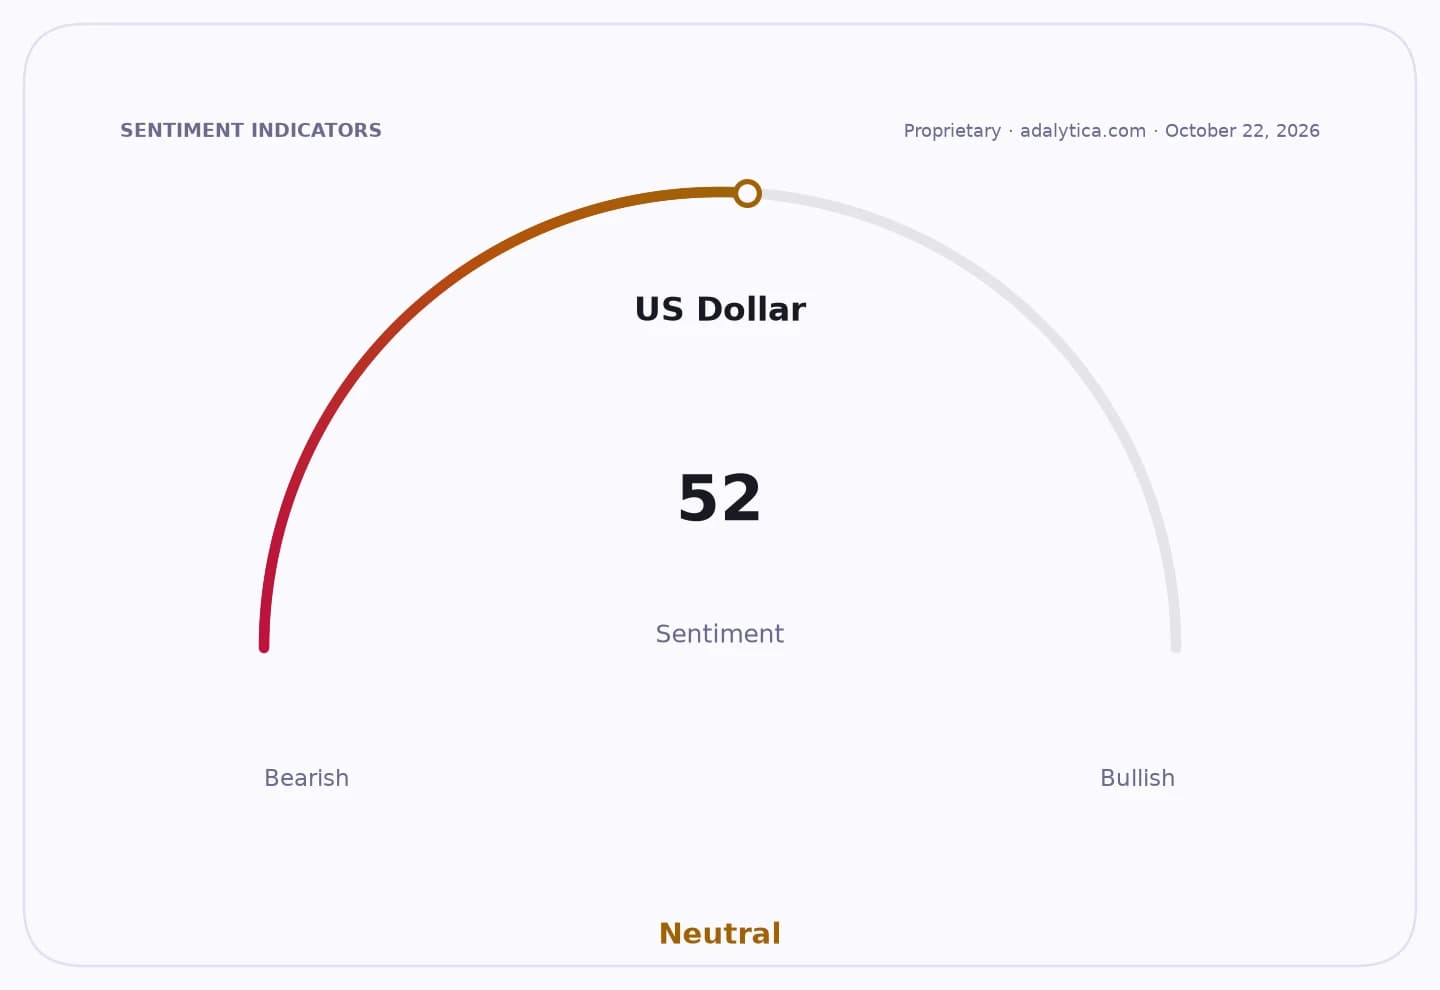
Sentiment Indicators
This is the latest reminder that bank forecasts can lag fast-moving currency cycles. All four institutions cited in the latest batch of projections underestimated the dollar’s strength, and the miss follows a weak third quarter in which every tracked forecast got the direction wrong. Santander Bank Polska was the furthest off, expecting 3.51 zł when the quarter ended at 3.8449 zł, an error of 8.71%.
For investors, the key question is not whether economists were wrong, but whether the move has room to run. Marcin Kiepas of Tickmill sees scope for USD/PLN to advance toward 3.95-3.98 zł, arguing that the pair is being driven largely by EUR/PLN and that the recent pullback looks more like a pause than a reversal. The technical backdrop supports that view: on Oct. 23, USD/PLN traded at 3.93 zł, above both its 50-day and 200-day moving averages, with momentum still positive even after a brief cooling from overbought RSI readings earlier in the month.
The bigger macro story is that the zloty is being pulled around by global risk and geopolitics rather than domestic fundamentals alone. Eryk Szmyd of XTB said the currency is behaving like a leveraged version of the euro-dollar pair, only with sharper swings, as tensions and a tense oil market keep pressure on risk-sensitive assets. That is exactly the kind of environment that can make exchange rates overshoot and stay detached from consensus for longer than investors expect.
For companies and households, a stronger dollar is a mixed blessing. Importers, consumers buying dollar-priced goods and firms with foreign-currency liabilities face higher costs, while exporters and anyone earning revenue in dollars get a lift. For diversified investors, the lesson is simpler: currency forecasts are notoriously unreliable, and in periods of volatility, being too certain is often more dangerous than being late.
The practical takeaway is that USD/PLN near 3.90 zł keeps the door open to another test of 3.95-3.98 zł if dollar demand stays firm and the zloty remains tied to broader European risk appetite. That makes the pair worth watching closely, especially for investors with exposure to Polish equities, bonds or imported costs.
| Entity | Gains | Losses |
|---|---|---|
| Dollar bulls | ▲Higher USD/PLN | ▼Missed bank forecasts |
| Polish importers | ▲— | ▼Higher input costs |
| Exporters earning dollars | ▲Better PLN revenues | ▼Stronger currency hedging costs |
| Long-zloty forecasters | ▲— | ▼Forecast credibility |