The Vietnamese National Assembly is moving to tighten bank oversight and anti-money-laundering rules as lawmakers weigh the fallout from the SCB Bank scandal, a case that exposed the costs of weak supervision in a financial system still heavily reliant on bank credit.
Vietnam Assembly weighs banking rules on Aug. 9
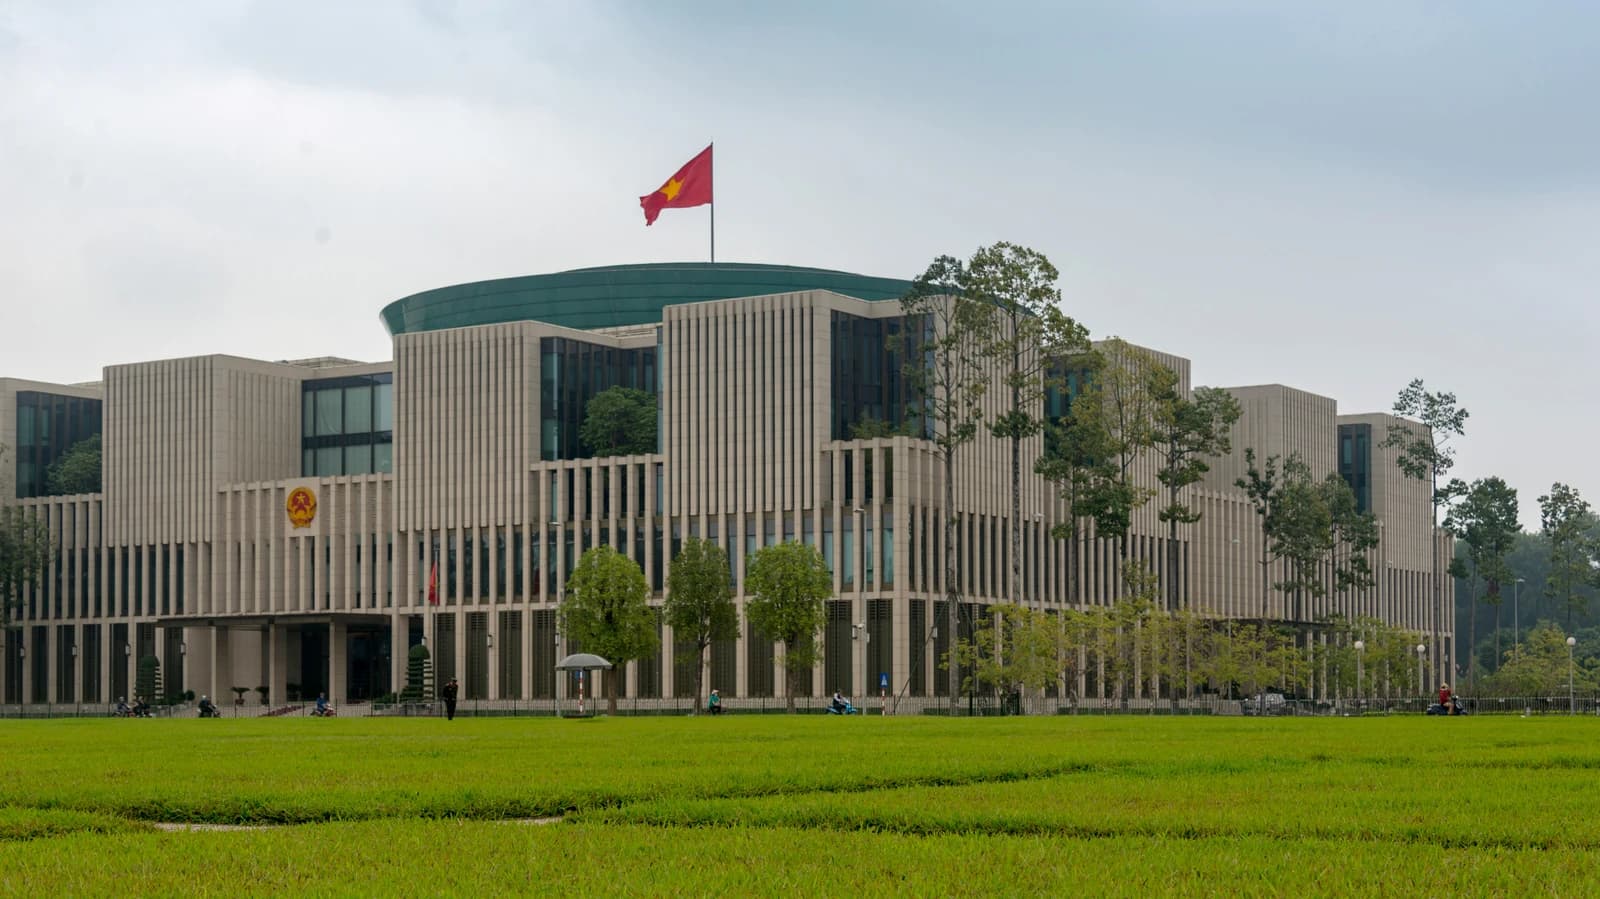
That matters because the legislation goes beyond a technical rewrite of banking laws: it is aimed at restoring confidence in a sector that sits at the center of Vietnam’s growth model. Any failure to improve monitoring of credit institutions, ownership links and suspicious transactions raises the risk of another destabilizing episode that could hit depositors, lenders and the broader economy.
Sentiment IndicatorsⓘProprietary · adalytica.com · August 9, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
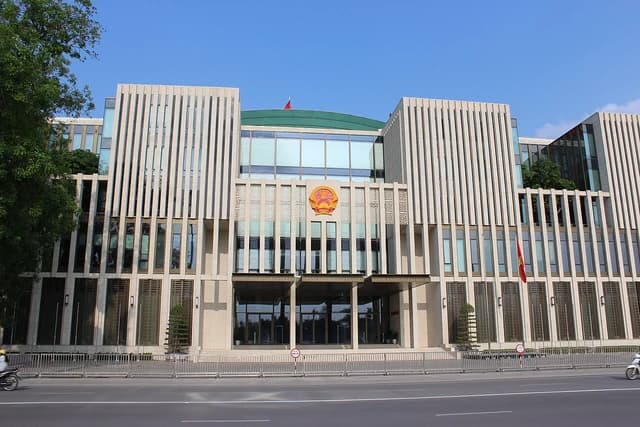
The discussion on Aug. 9 covered amendments to the Law on the State Bank of Vietnam, the Law on Prevention and Combat of Money Laundering and the Law on Credit Institutions, underscoring how lawmakers are trying to close regulatory gaps exposed by the SCB case. The scandal became a cautionary tale for a market where banks remain the main channel for corporate and household financing, and where poor disclosure can quickly spill into liquidity stress and higher funding costs.
For investors, the key question is whether the reforms translate into stronger governance without choking credit growth. Tighter rules on bank ownership, related-party lending and compliance would be positive for long-term system stability and foreign confidence, but they could also increase operating costs and constrain some lenders, especially those with weaker risk controls or opaque balance sheets. In the near term, that tends to favor larger, better-capitalized banks while leaving smaller or more weakly governed institutions under pressure to clean up.
The timing also matters. Vietnam is trying to keep credit flowing to support growth while avoiding another confidence shock in a sector that has already shown it can transmit corporate and property stress into the wider economy. Stronger anti-money-laundering standards would also help align the country with global compliance expectations, reducing the risk that banks face reputational damage or friction with international counterparties.
The broader narrative is straightforward: the SCB affair has become a political and economic test of whether Vietnam can strengthen financial supervision without undermining its credit-led development model. If the Assembly’s amendments are implemented aggressively, they could lower systemic risk and improve the banking sector’s investability over time. If enforcement remains uneven, the reforms may prove more symbolic than structural.
| Entity | Gains | Losses |
|---|---|---|
| Large Vietnamese banks | ▲Stronger trust | ▼Less room for opacity |
| Smaller or weaker lenders | ▲Cleaner market | ▼Higher compliance burden |
| Depositors and borrowers | ▲Better protection | ▼Potentially tighter credit |
| Regulators and lawmakers | ▲More oversight | ▼Higher implementation pressure |




