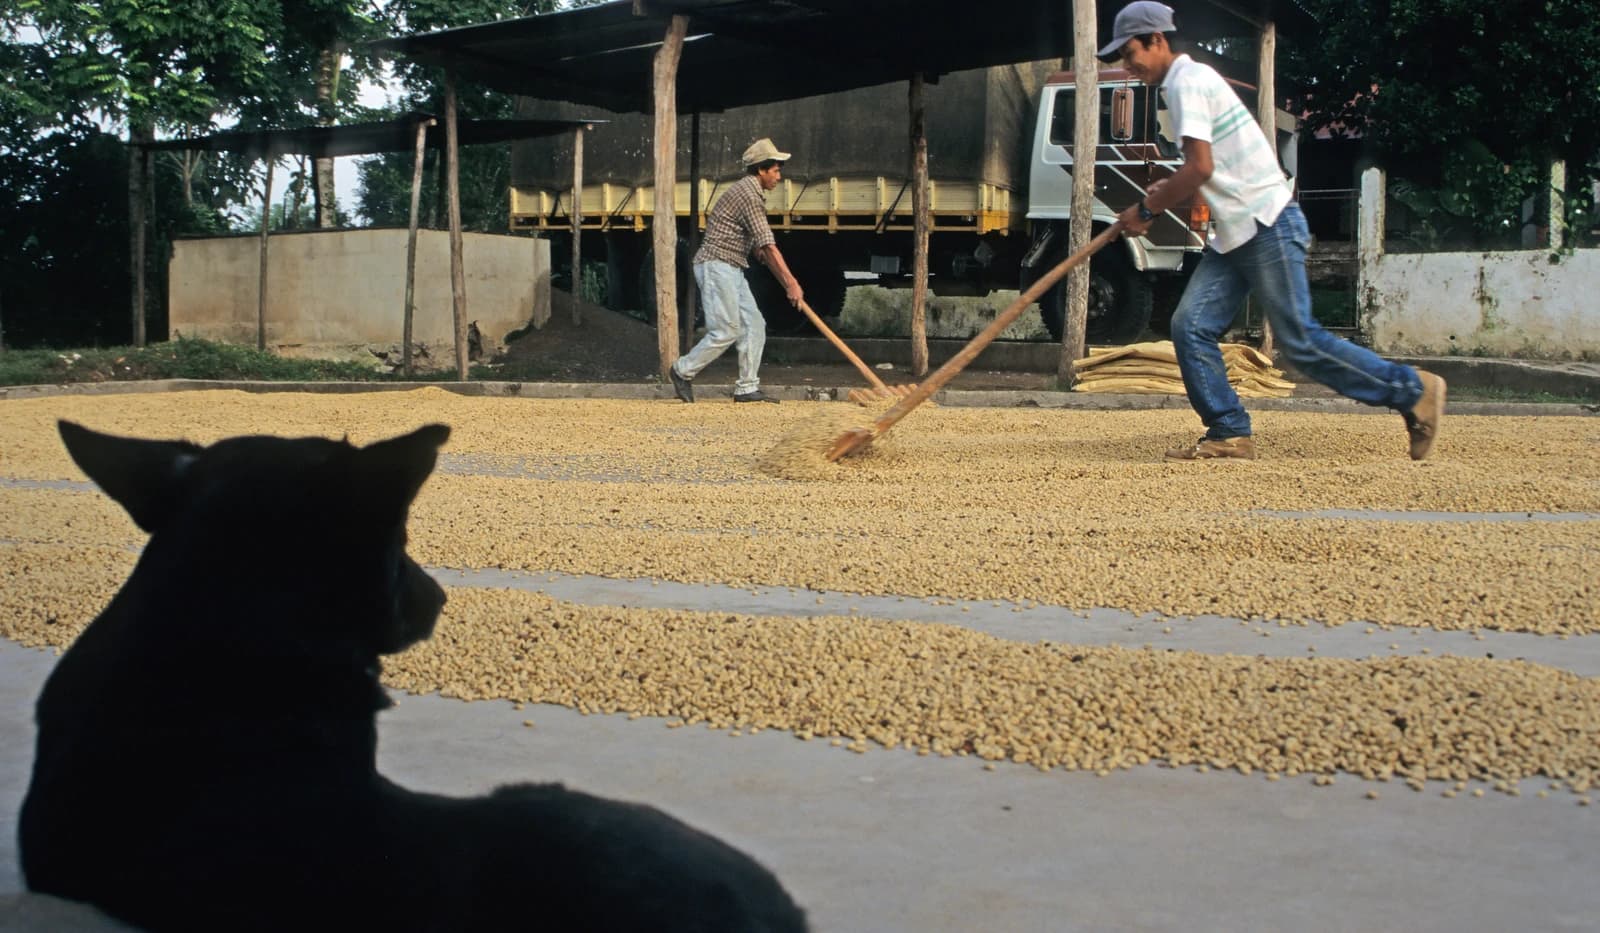
Coffee prices in Vietnam are holding near 83,600-84,500 dong a kilogram as traders look past a modest uptick and focus on the bigger variable: the arrival of the new crop and whether supply outpaces demand into mid-November.
Vietnam coffee prices near 84,000 dong on harvest outlook
That matters because Vietnam is the world’s top robusta producer, and even small shifts in farmgate selling can move the tone of the global market. Local averages rose 100 dong a kilogram on the latest reference table, with three of four buying regions posting gains and Gia Lai unchanged, but the market is still being driven less by today’s quote and more by the pace of harvest sales.
Sentiment Indicators
The domestic spread remains narrow at 900 dong a kilogram, suggesting buyers are not yet paying up aggressively for scarce beans. At the same time, the reference price is being supported by overnight robusta strength, even if the move was modest. That leaves prices vulnerable to a familiar seasonal pattern: early support from external markets, followed by pressure as fresh supply comes off the trees.
Global coffee futures are giving mixed signals. Arabica on ICE has rebounded to 275.1 cents a pound after touching 269.0 cents in the prior session, but it is still well below its 2026 peak and remains under pressure relative to its 50-day moving average of 293.89 cents. The RSI at 24.5 points to deeply oversold conditions, yet the broader technical picture still shows a market that has lost momentum. Robusta, which is more directly tied to Vietnam supply, has also weakened from October levels, reinforcing the view that growers and exporters are waiting for a clearer price floor before selling aggressively.
For investors and food companies, the implication is straightforward: the near-term risk is not a supply shock but a supply wave. If farmer selling accelerates as the harvest deepens, local prices could soften even if global coffee futures stabilize. If exporters and roasters absorb the fresh crop quickly, the current floor may hold. Either way, the market is entering a phase where physical supply dynamics matter more than headline futures moves.
That is why the next few weeks are crucial for café chains, roasters and coffee traders. Starbucks and other buyers remain exposed to volatile green coffee costs, while Vietnamese supply conditions will help determine whether the recent easing in commodity pressure continues or reverses. For now, coffee prices are being held up by a fragile balance: enough demand to prevent a break, but not enough to absorb the new crop without testing that support.
| Entity | Gains | Losses |
|---|---|---|
| Vietnamese growers | ▲Higher farmgate support | ▼Lower prices if harvest selling accelerates |
| Exporters/roasters | ▲More supply to source | ▼Margin pressure if prices rebound |
| Coffee futures traders | ▲Volatility opportunities | ▼Long positions if new crop weighs on prices |
| Consumers/café chains | ▲Potential easing in input costs | ▼Less benefit if support holds and prices stay firm |