Vietnam’s rice export revenue fell more sharply than shipments in the first nine months of 2026, a sign that weaker pricing — not just lower volumes — is eroding earnings for one of the country’s most important farm exports.
Vietnam rice export revenue falls as prices weaken
The country shipped 6.36 million tons of rice worth just over $3.05 billion in the period, according to customs data cited by local media. Export volume declined 6.7% from a year earlier, but turnover dropped 12.3%, implying the average value per ton fell about 5.9%. In plain terms, Vietnam is moving less rice and getting paid less for each ton it sells.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 14, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
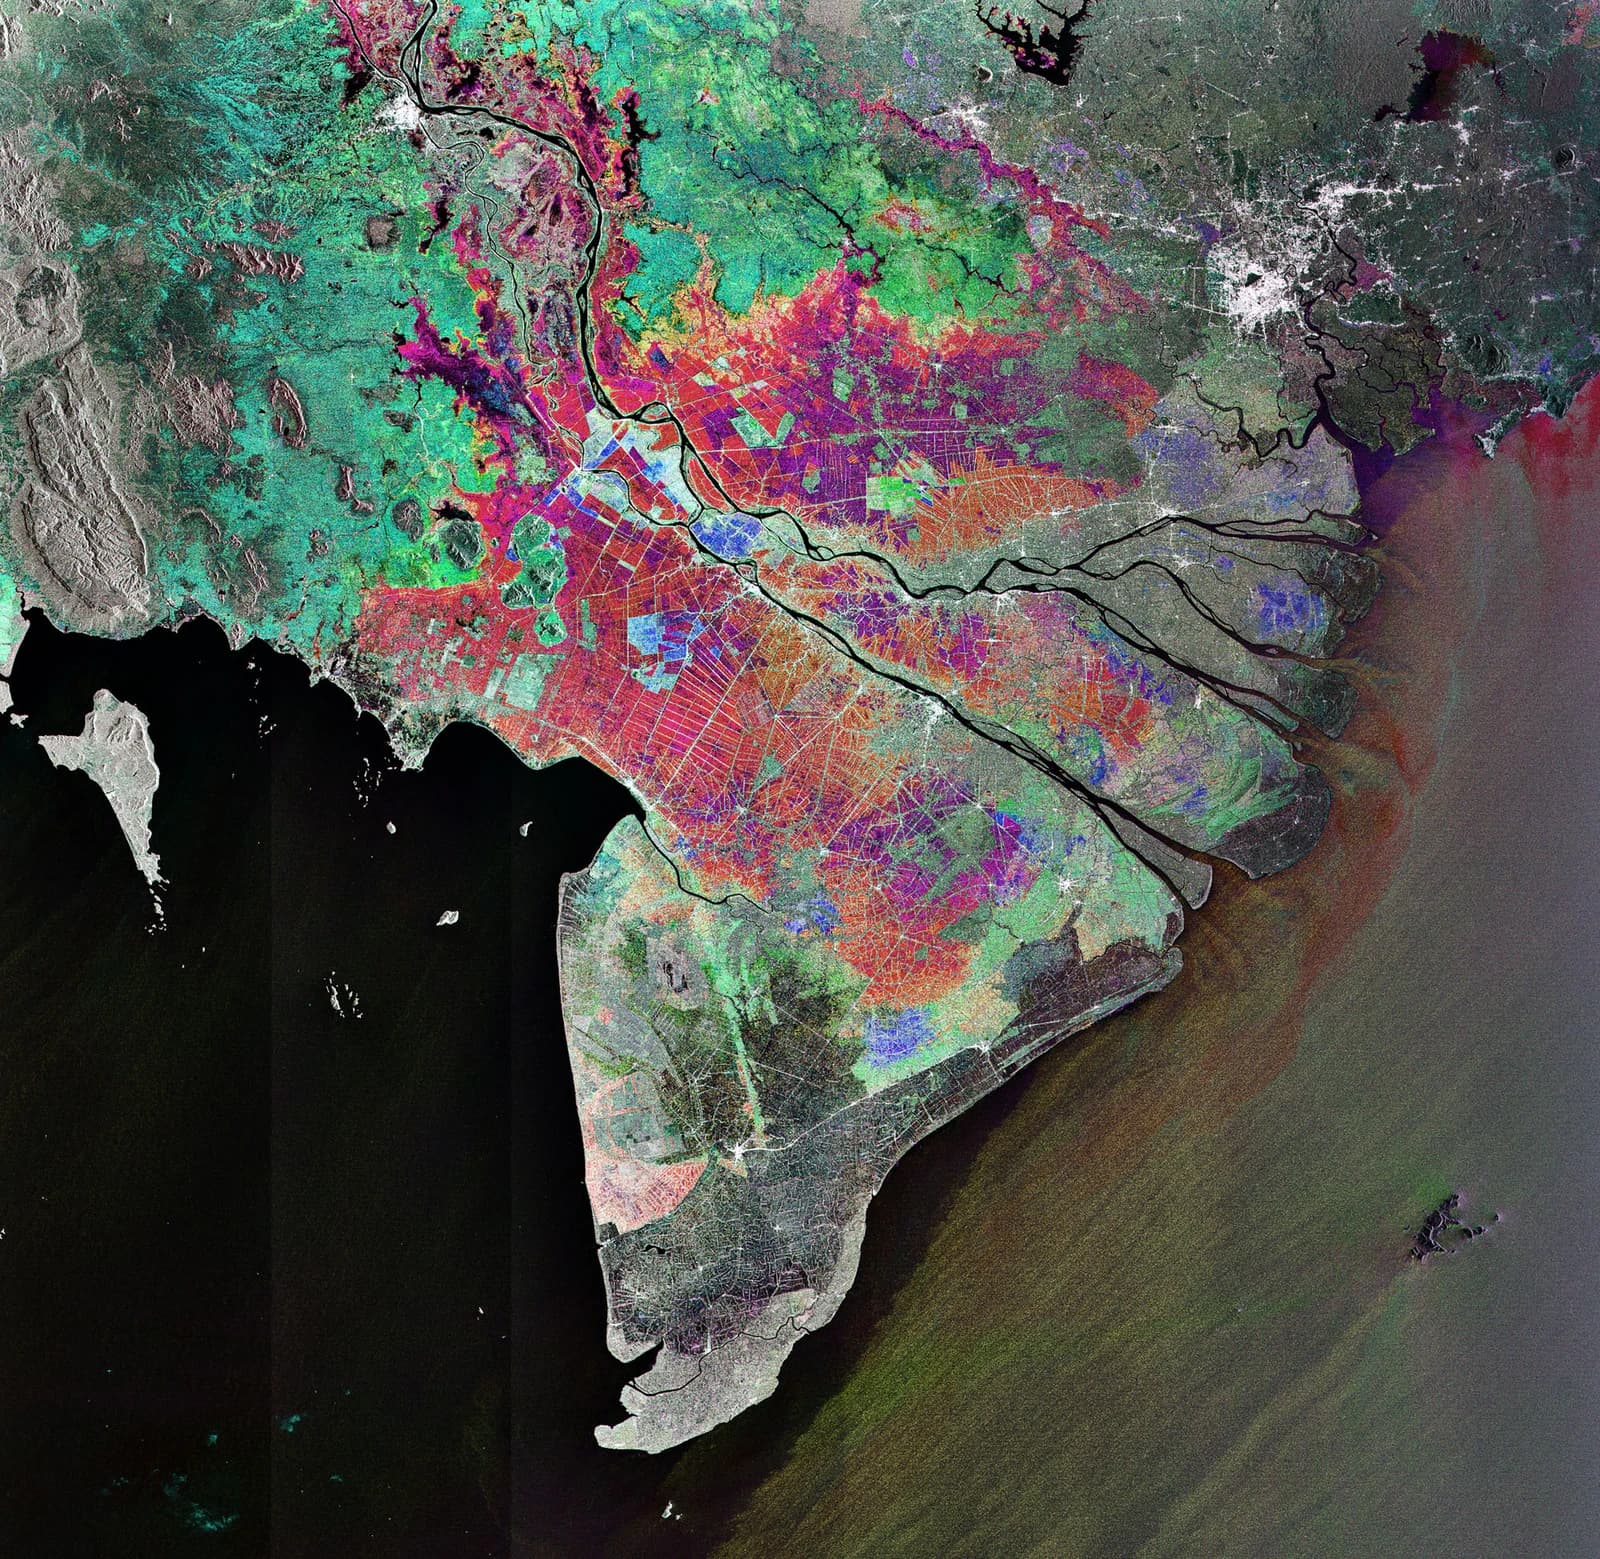
That matters because rice is not just a food staple; it is a key source of foreign exchange for Vietnam and a bellwether for agricultural income across the Mekong Delta. When revenue falls faster than volume, margins compress for exporters, farm-gate prices come under pressure, and the benefit of any global supply tightness is weaker than headline tonnage might suggest.
The monthly trend was even softer. In September alone, exports fell to 433,778 tons worth $223.26 million, down 19.5% in volume and 20.2% in value from August. That shows the pricing squeeze has not yet stabilized, even after recent reports of firmer domestic rice prices in the Mekong Delta on crop-loss worries, higher fuel costs and seasonal supply pressures.
For investors, the message is less about a single weak quarter than about the structure of the market. Vietnam’s rice exporters face a classic mix of lower realized prices, volatile regional supply and uneven demand from Asian buyers. That can hit listed millers, traders and logistics-linked names first, but it also ripples through rural cash flow, working capital needs and export-related foreign exchange receipts.
The key risk is that the market focuses on shipment volumes and misses the bigger drag from price realization. If global rice markets stay soft or buyers keep pushing back on pricing, export turnover can keep lagging output, limiting earnings even if harvest and shipment volumes improve. The near-term opportunity, by contrast, sits with companies that can secure higher-value grades, control input costs and protect margins in a lower-price environment.
| Entity | Gains | Losses |
|---|---|---|
| Vietnamese rice buyers/importers | ▲Lower purchase costs | ▼None |
| Vietnamese rice exporters | ▲Higher volumes if prices stabilize | ▼Revenue and margins |
| Mekong Delta farmers | ▲Better prices if domestic supply tightens | ▼Income if export prices stay weak |
| Global rice consumers | ▲Cheaper supply | ▼Rice-producing exporters |